Porsche: How a Niche Automaker Defies Economics
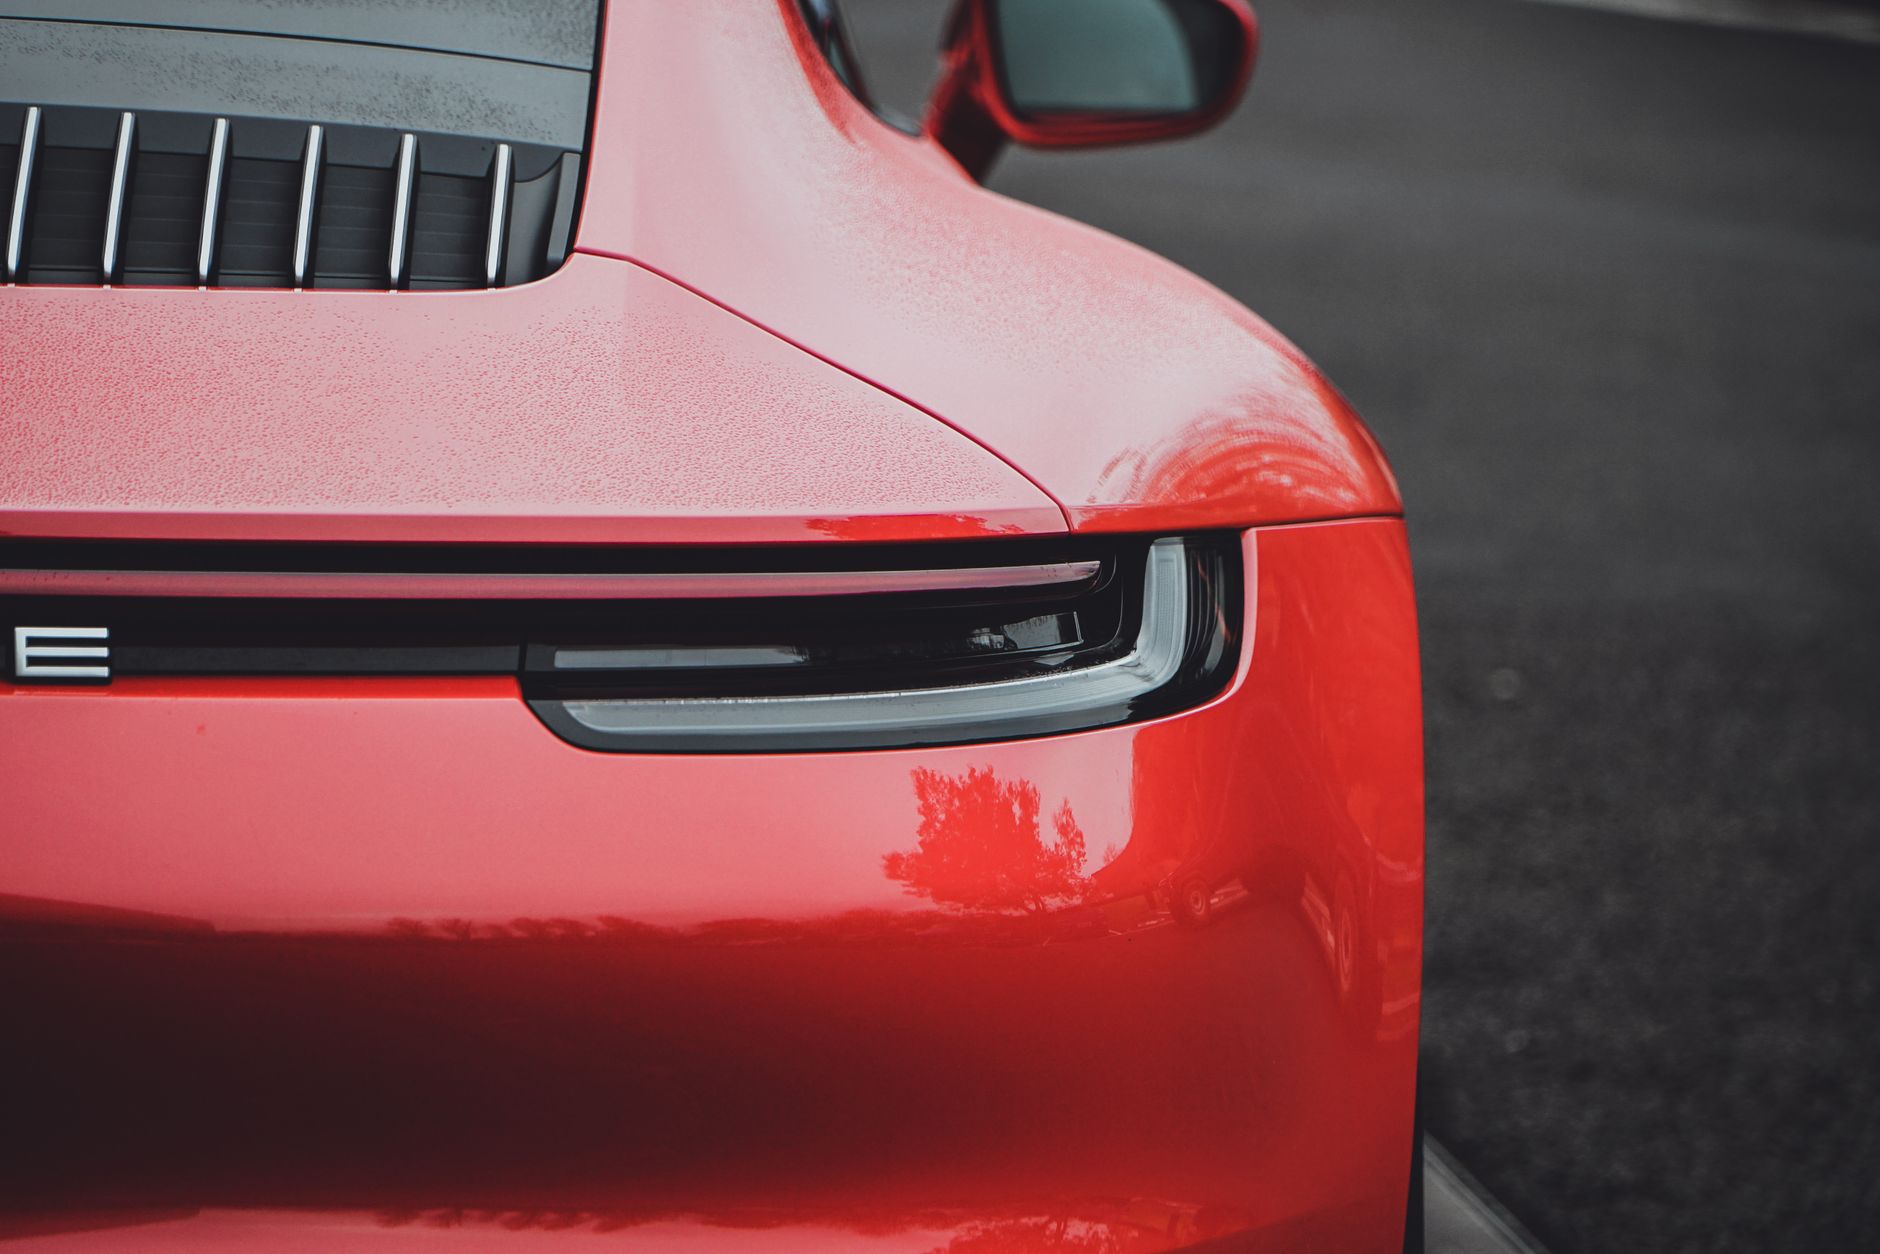
The Pricing Anomaly
There is something economically absurd about Porsche. The company manufactures roughly 350,000 vehicles annually, a volume that places it alongside premium mass-market brands like BMW’s M division or Mercedes-AMG, yet it captures average selling prices of $110,000 and operating margins that luxury conglomerates twice its size cannot match. More peculiar still, half of these vehicles are sport-utility trucks, rchitecturally conventional, front-engine, all-wheel-drive appliances that share showrooms with mid-engine supercars and rear-engine racing homologations.
This should not work. In normal luxury economics, scale and exclusivity operate on an inverse curve. Ferrari sells 13,000 cars a year and maintains pricing power through enforced scarcity. Toyota sells ten million and competes on efficiency. Porsche attempts both simultaneously, producing nearly 500,000 units while insisting that each remains an object of engineering distinction worth six figures. The business model relies on a transference mechanism: the 911, with its fifty-year rear-engine lineage and motorsport pedigree, acts as a credentialing device for the Cayenne and Macan, allowing Porsche to charge Bentley prices for Volkswagen architectures.
The question is not whether this works, it clearly does, but how long the physics of brand thermodynamics permits the transfer of heat from the race track to the school run without equalizing the temperature. Porsche’s entire valuation rests on the assumption that engineering authenticity is a renewable resource, infinitely divisible across expanding production lines. The history of automotive luxury suggests otherwise.
The Mechanics of Transferred Authenticity
The economic engine runs on a specific alchemy: the 911 generates credibility that the SUVs monetize. This is not merely marketing gloss. The 911’s rear-engine configuration, inherited from the 1948 356 and traceable back to Ferdinand Porsche’s design for the Volkswagen Beetle, creates distinct dynamic behaviors, snap oversteer, traction advantages, weight distribution eccentricities, that require genuine engineering investment to manage. When Porsche develops a new 911 GT3, it validates the company’s claim to motorsport heritage. When that same engineering team tunes the suspension kinematics of a Cayenne Turbo, the SUV inherits a halo of technical legitimacy that a BMW X5 or Mercedes GLE cannot claim, despite similar underlying architectures.
This transfer creates pricing power that defies commodity logic. The Cayenne shares platforms with the Volkswagen Touareg and Audi Q7, yet commands premiums of 40 to 60 percent. The Macan rides on architectures common to Audi Q5s, yet Porsche sells them at average transaction prices exceeding $80,000. Customers pay not for the hardware, which is largely interchangeable with mass-market Volkswagen Group engineering, but for the permission to believe they have purchased something technically distinct.
The durability of this mechanism depends on constraints. Ferrari’s foray into SUVs with the Purosangue maintains scarcity through limited production and seven-figure pricing. Lamborghini caps Urus volume to preserve exclusivity. Porsche, by contrast, has committed to industrial scale, pushing annual production toward half a million units while maintaining that each vehicle remains a “sports car” in ethos. This requires a delicate calibration: enough 911s must circulate to maintain the halo, but not so many that they become commonplace; enough SUVs must sell to fund R&D, but not so many that the brand becomes indistinguishable from Audi or BMW.
The fragility lies in the asymptote. At 300,000 units annually, Porsche occupied a unique coordinates in luxury automotive space, xclusive enough to command premiums, large enough to fund technical development. At 500,000 units, with SUVs comprising three-quarters of the mix, the company approaches the event horizon where “luxury” transitions to “premium.” The engineering narrative must work harder to justify the price spread. Eventually, the arithmetic of scale overwhelms the mythology of craftsmanship.
The Stuttgart Moat
Most analyses of Porsche’s competitive position focus on brand equity or engineering heritage, underappreciating the structural advantage of geographic density. Stuttgart and the surrounding Baden-Württemberg region constitute perhaps the world’s most concentrated ecosystem of automotive engineering talent and precision manufacturing. Within a fifty-kilometer radius sit Mercedes-Benz headquarters, Bosch headquarters, and a dense network of Mittelstand suppliers specializing in drivetrain components, precision machining, and composite materials.
This clustering creates economic moats that competitors cannot replicate through capital investment alone. When Porsche engineers a new dual-clutch transmission or carbon-ceramic braking system, they do not source components through global supply chains; they drive twenty minutes to supplier facilities, iterating designs in real-time with technicians who have spent decades refining metallurgical processes specific to high-performance applications. The region’s technical universities, Stuttgart, Karlsruhe, Aachen, feed directly into this pipeline, creating a labor market where powertrain engineers and chassis dynamics specialists change employers without changing zip codes.
Detroit once possessed similar density, but fragmented through decentralization and labor stratification. Stuttgart maintains it through institutional continuity and the peculiar economics of German industrial organization. For a competitor to replicate Porsche’s capabilities, they would need not merely to hire away engineers, a common tactic in the industry, but to relocate entire supplier networks and recreate decades of tacit knowledge embedded in regional manufacturing practices.
This geographic concentration also explains Porsche’s ability to maintain the rear-engine 911 architecture despite its engineering compromises. The layout is thermally inefficient and dynamically challenging, requiring constant innovation in cooling and weight distribution to remain competitive. Only a company with immediate access to the world’s deepest bench of powertrain and chassis specialists could afford the engineering overhead of preserving such an eccentric lineage. In Stuttgart, the abnormal is merely expensive; elsewhere, it would be impossible.
Familial Capital as Competitive Armor
The governance structure functions as an economic variable distinct from operational capability. Porsche AG operates within a labyrinthine ownership construct: the Porsche family and the Piech family, descended from Ferdinand Porsche, control voting rights through layered holding companies, specifically Porsche Automobil Holding SE, which owns 53 percent of Volkswagen Group, which in turn owns Porsche AG. This circular arrangement insulates management from quarterly earnings pressure and activist investor interference.
The economic consequence is patient capital. When Porsche developed the first Cayenne in the early 2000s, the project required betting the company’s balance sheet on a vehicle format that enthusiasts considered brand dilution and analysts considered market suicide. A publicly traded company with dispersed institutional shareholders would likely have faced pressure to cap investment or spin off the sports car division to “unlock value.” The family ownership structure permitted a decade-long horizon, accepting that the Cayenne might destroy brand equity before it generated returns.

This same structure, however, introduces fragility that financial statements do not capture. The intersection of the Porsche and Piech families, linked by marriage but divided by feud, creates succession instability. Ferdinand Piëch, the engineering autocrat who dominated Volkswagen Group and by extension Porsche until his 2015 ouster, represented a governance model of charismatic authority rather than institutional process. His departure created a vacuum, and the subsequent generations lack his technical credibility or ruthless decisiveness.
Should the family coalitions fracture, through generational transfer of voting shares, inter-familial litigation, or the death of key patriarchs, the complex ownership web could unravel. Unlike publicly traded luxury groups where shares trade freely and governance disputes resolve through market mechanisms, Porsche’s ownership requires political negotiation between family factions. A succession crisis would not merely affect board composition; it could freeze strategic decision-making during critical transition periods, particularly the electrification shift that requires capital allocation discipline the families may no longer agree upon.
The Arithmetic of Dilution
The central tension remains mathematical. Porsche’s strategy requires maintaining the exclusivity premium of a low-volume manufacturer while achieving the economies of scale of a mass-market producer. At current trajectories, the company approaches 500,000 annual units, with the Macan and Cayenne contributing roughly 350,000 of those sales. This volume places Porsche in the same manufacturing tier as Jaguar Land Rover or Volvo, rands that struggle to maintain pricing power precisely because their ubiquity erodes scarcity value.
The risk is not immediate brand collapse but gradual margin compression disguised as growth. As SUV volume expands, Porsche must either constrain 911 production to maintain relative scarcity, sacrificing the economies of scale that justify the fixed costs of the 911 platform, or increase 911 output to amortize development costs, diluting the halo that sustains SUV pricing. Currently, the company threads this needle by maintaining lengthy waitlists for 911 GT products while flooding markets with Macan base models.
But markets adjust. When every affluent suburb features multiple Cayennes in school drop-off lines, the vehicle transitions from status signal to mere transportation. Porsche’s response, emphasizing customization and “bespoke” options, attempts to manufacture artificial scarcity within mass production. Yet there are limits to how many $110,000 vehicles a market can absorb before the price itself becomes the differentiator rather than the engineering. At that point, Porsche competes directly with Range Rover and Mercedes-Benz on feature sets rather than heritage, a competition where its rear-engine mythology provides no advantage.
The electric transition intensifies this pressure. The Taycan, Porsche’s electric sedan, sells well but lacks the 911’s mechanical distinctiveness, lectric motors and battery packs are commodity components, interchangeable across manufacturers. Without the idiosyncratic engineering of the 911 to generate authenticity, Porsche’s electric SUVs will struggle to justify premiums over Tesla, Rivian, or Mercedes EQ products. The transfer mechanism breaks when the source loses its specificity.
The Contingent Liability of Origins
Beneath the engineering narratives lies a historical contingency that functions as an unquantified liability. Ferdinand Porsche did not merely design the Beetle; he was a member of the SS, used forced labor in his factories, and accepted contracts from the Nazi regime that built the Volkswagen works using concentration camp prisoners. The company’s post-war existence depended on a British military officer, Major Ivan Hirst, who overrode his government’s assessment that the Beetle was “not commercially viable” and placed an order for 20,000 units, effectively restarting the industrial apparatus that would fund Porsche’s early years.
This history is not merely academic. Porsche AG operates under a social license that requires continuous maintenance. The company’s survival depended on post-war Allied forbearance and the deliberate obscuring of its founder’s war crimes. While German industry has largely integrated its Nazi history into corporate narratives of repentance, Porsche’s specific dependencies, forced labor in its Austrian sawmill operations, Ferdinand Porsche’s personal SS membership, the British military orders that provided initial capital, create vulnerabilities should historical accountability standards shift.
The risk is not litigation per se; the statutes of limitations on wartime reparations have largely expired. Rather, it is the revocation of the narrative that permits Porsche to occupy the cultural space it does. The “German engineering” premium relies on a post-war story of rehabilitation through technical excellence. Should contemporary movements revisit corporate WWII accountability with renewed vigor, Porsche’s origins could shift from historical footnote to operational drag. Younger consumers in key growth markets, China, North America, may prove less willing to separate the 911’s aesthetics from its provenance than previous generations who accepted the separation of product from producer.
When the Halo Fades
The bear case for Porsche is not bankruptcy or operational failure but slow-motion brand commoditization. The assumption that the 911’s authenticity can indefinitely transfer to expanding SUV volume ignores the saturation point where “Porsche” becomes merely another luxury badge, interchangeable with BMW M or Mercedes-AMG. At 500,000 units annually, with electric drivetrains eliminating the mechanical distinctiveness that justified premiums, the company risks becoming a high-margin Volkswagen division rather than a distinct luxury house.
This transition would not appear on balance sheets immediately. Margins would compress gradually as transaction prices soften and incentive spending rises. The Cayenne would remain a competent luxury SUV, but competent luxury SUVs sell for $70,000, not $110,000. The delta represents the value of the halo; when the halo dissipates, Porsche retains the cost structure of a low-volume manufacturer with the pricing power of a mass-market brand: structurally untenable position.
The defense against this outcome requires constraints that the current ownership structure may no longer tolerate. To maintain authenticity, Porsche must cap SUV volume and accept lower growth rates, a decision that families dependent on dividend income may resist. Alternatively, it must invest in new distinctiveness, autonomous capabilities, materials science, manufacturing processes, that competitors cannot replicate, requiring capital commitments that strain the governance structure.
The company’s history suggests it recognizes the precipice. The development of the Carrera GT, 918 Spyder, and forthcoming hypercar projects represent attempts to regenerate the engineering credibility that mass-market SUV production consumes. But each halo car costs hundreds of millions to develop while contributing negligible revenue. The SUVs pay the bills; the supercars justify the bills’ size.
This balance has held for two decades. Whether it survives the transition to electric propulsion, the death of the internal combustion engine’s sensory feedback, and the arithmetic of half-million-unit production remains the central question. Porsche’s economic engine is ingenious but thermodynamically unusual: it creates heat through scarcity, then distributes that heat through mass production, hoping the source never cools. In physics, such systems eventually reach equilibrium. In business, equilibrium is another word for commoditization.
The Voltage Transition
The internal combustion engine provided the perfect substrate for Porsche’s authenticity transfer. The 911’s flat-six is objectively wrong for the vehicle’s layout, hanging behind the rear axle, creating pendulum physics that engineers have spent fifty years mitigating, yet this wrongness generates narrative value. It requires specialized knowledge to manage, creates distinct sensory signatures that cannot be synthesized, and demands manufacturing tolerances that mass-market engines ignore. When Porsche translates this expertise to an SUV, even if the hardware differs, the organizational capability to manage thermal loads and vibration harshness supposedly transfers, justifying the price spread through demonstrated technical mastery.
Electric propulsion eliminates this differentiation substrate. Electric motors are commodities, otating magnetic fields operating at 95+ percent efficiency regardless of manufacturer. The Taycan illustrates the flattening effect. Technically accomplished, it offers 800-volt architecture enabling rapid charging, yet this advantage is replicable; Hyundai and Kia now offer similar voltage systems at half the price. The driving dynamics impress, but the hardware, a battery pack mounted beneath the floor, front and rear axle motors, differs little from a Tesla Model S or Mercedes EQS beyond calibration parameters.
What remains is tuning, the coding of throttle response and regenerative braking algorithms. But tuning is software, and software scales without Stuttgart’s geographic moat. A team in California or Shanghai can achieve damper calibration that matches Porsche’s ride quality given sufficient telemetry data and computing power. The mechanical distinctiveness that justified the “German engineering” premium: he specific sand-casting techniques for engine blocks, the proprietary forging processes for connecting rods, the acoustic engineering of intake manifolds, ecomes irrelevant when the powertrain contains twelve moving parts rather than twelve hundred.
This threatens the transfer mechanism at its root. The Cayenne could inherit credibility from the 911 because both contained engines, transmissions, and chassis architectures sharing developmental DNA. The upcoming Macan EV and electric Cayenne will migrate to the PPE (Premium Platform Electric) architecture, a Volkswagen Group standard shared with Audi, Bentley, and potentially Lamborghini. The differentiation becomes skin-deep: body panels, interior materials, and user interface skins over identical battery cells and motor assemblies. In this environment, Porsche competes not on engineering heritage but on software iteration speed and brand cachet, ompetencies where Tesla and Chinese manufacturers often move faster.
The risk is a rapid collapse of the pricing structure. Currently, Porsche commands a $30,000-$50,000 premium over equivalent Audi or BMW products. In electric vehicle markets, where range and charging speed dominate purchasing decisions and where performance metrics have been democratized by instant torque, such premiums require justification beyond heritage. Porsche must convince buyers that its electric Macan merits $90,000 when a Genesis GV60 or Tesla Model Y offers similar utility for $60,000. Without the mechanical mystique of the 911 to provide cover, this becomes a marketing exercise rather than an engineering argument, and marketing exercises rarely sustain six-figure price points against competent competition.
The Succession Threshold
The familial governance structure that enabled long-term thinking carries a timing device. Ferdinand Piëch died in 2019, but the power transition he represented, charismatic, technically dominant, ruthlessly decisive, remains unresolved. His cousin, Wolfgang Porsche, chairs the supervisory board, but lacks Piëch’s engineering credibility and autocratic temperament. The next generation, Piëch’s children and the various Porsche grandchildren, holds voting rights through complex trust structures, yet lacks the cohesion of the founding generation.
The economic risk manifests in capital allocation paralysis. Electrification requires betting billions on battery technology, charging infrastructure, and new manufacturing processes while maintaining the internal combustion engine lineup that generates current profits. A fragmented family ownership could produce governance gridlock: faction A demanding immediate dividends from SUV cash flows, faction B pushing for aggressive EV investment, faction C advocating for asset sales to realize liquidity. Unlike publicly traded companies where such disputes resolve through proxy battles and share price signals, Porsche’s ownership structure requires consensus among family branches with divergent financial needs and strategic visions.
Historical precedent suggests the fragility. The 2008 financial crisis nearly destroyed Porsche SE (the holding company) due to speculative options trading intended to acquire full control of Volkswagen: strategy driven by family ambition rather than operational logic. Only Volkswagen’s counter-takeover of Porsche AG prevented collapse. This episode revealed that family control, while providing long-term patience, can also generate catastrophic risk-taking when personal rivalries override institutional caution. The current generation lacks the technical confidence to engineer such speculative coups, but also lacks the unity to navigate the industry transition.
The specific trigger for governance crisis likely arrives with the death of current family patriarchs and the distribution of voting shares to fourth-generation members. German corporate law and the Porsche/Piech family protocols create overlapping vetoes and blocking minorities. Should one branch decide to liquidate holdings to cover estate taxes or personal liabilities, the carefully balanced control structure could unravel, exposing Porsche AG to activist investors or strategic acquirers who would demand the profit maximization that the family structure previously prevented. The patient capital becomes impatient, and the strategic timeline compresses to quarterly horizons.
The Gmund Calculation
The historical contingency extends beyond Ferdinand Porsche’s SS membership to the specific circumstances of the company’s survival. In 1947, Ferry Porsche and a team of engineers built the first 356 prototypes in a sawmill in Gmund, Austria, using repurposed Volkswagen Beetle parts and a supercharged engine designed during Ferdinand’s imprisonment. This origin story, ingenuity amid scarcity, provides the moral foundation for the company’s post-war narrative. Yet the sawmill operation depended on laborers including forced workers and prisoners of war, a detail that complicates the foundation myth.
More critically, the company’s existence required the specific decision of Major Ivan Hirst, a British Royal Electrical and Mechanical Engineers officer, to restart Volkswagen production in Wolfsburg in 1945. The British occupation government had assessed the Volkswagen works as valueless, intending to dismantle the factory for reparations. Hirst, recognizing utility in the Beetle design for occupation transport, placed an order for 20,000 vehicles. This order provided the revenue stream that allowed Volkswagen to survive, which in turn provided the parts and engineering employment that allowed Porsche to transition from sawmill fabrication to industrial production.
The economic significance is that Porsche’s entire capital base traces to a single British officer’s procurement decision and the subsequent forgiveness of war crimes. Ferdinand Porsche and his son-in-law Anton Piech were imprisoned as war criminals for two years; Ferry Porsche for six months. Their release and the company’s rehabilitation required Allied political calculations about German industrial reconstruction rather than any judicial exoneration.
This creates a latent liability that differs from standard corporate historical reckoning. Unlike companies that profited from slavery or colonialism in the distant past, Porsche’s survival is temporally proximate to its moral crimes and directly contingent on specific Allied forbearance. Should contemporary political movements demand re-examination of corporate WWII accountability, particularly regarding the use of concentration camp labor at Volkswagen and Porsche facilities, the company’s ability to claim “German engineering” purity becomes legally and culturally complicated. The risk is not merely reputational damage but potential asset seizures or operating restrictions in key markets where WWII accountability remains politically salient, particularly as Holocaust education intensifies in American and Asian markets where Porsche seeks growth.
The Depreciation Firewall
A hidden economic variable in Porsche’s pricing power is the secondary market behavior of its vehicles, particularly the 911. Unlike mass-market luxury cars that depreciate 50 percent in three years, air-cooled 911s and even recent 991-generation models often appreciate or hold steady. This unusual depreciation curve creates a “wealth effect” for primary buyers: they pay high prices not merely for transportation but for call options on future asset appreciation. The $150,000 Carrera S becomes a stored value instrument, reducing the effective cost of ownership and justifying the initial premium through expected residual strength.
The mechanism relies on artificial scarcity and generational cohort effects. Porsche carefully manages 911 production volumes relative to demand, creating waiting lists for GT3 and Turbo models that extend two to three years. This constraint generates secondary market premiums, uyers pay $50,000 over MSRP for immediate delivery, establishing a price floor that supports new car residuals. The SUV strategy threatens this firewall. As Cayenne and Macan volumes expand, their depreciation curves behave like standard luxury vehicles, teep declines in years one through three, flooding used car markets with supply that competes against new models and depresses trade-in values.
When the SUV flood reaches critical mass, it potentially contaminates the brand’s residual value mathematics. Currently, a buyer rationalizes the $110,000 Cayenne purchase knowing that Porsche ownership provides access to 911 allocation rights at MSRP rather than market premiums: bundled value proposition. If Cayennes depreciate like BMW X5s (losing $40,000 in value over three years), the total cost of ownership calculation shifts. The brand becomes expensive to own rather than expensive to buy but prudent to hold.
Moreover, the enthusiast community that sustains the 911’s secondary market, the collectors, track-day participants, and club members who treat the vehicles as cultural objects, represents the authenticating constituency. These buyers accept eccentric maintenance costs and impracticality because the vehicles promise community belonging and asset preservation. They are the “true believers” whose enthusiasm provides the credibility transfer to SUV buyers. Should the SUV volume drive these enthusiasts to Ferrari, McLaren, or emerging analog specialists (Singer, Ruf), the 911’s secondary market softens. The depreciation curve steepens. The $150,000 new Carrera becomes a $90,000 used car in two years rather than a $140,000 asset, breaking the financial logic that supports the brand’s pricing architecture.
The Allocation Valve
Porsche manages the exclusivity-mass scale tension through a specific production control mechanism: the allocation system. Rather than building to forecast and discounting excess inventory, a standard automotive practice, Porsche produces to order for high-margin sports cars, creating artificial scarcity that masks the SUV volume expansion. When a dealer receives three 911 GT3 allocations annually for customers with established relationships (previous purchases, service history, club participation), they create a ritual of exclusivity that compensates for the twenty Macans sitting on the lot available to any buyer with credit approval.
This valve requires precise calibration. Too few allocations, and high-value customers defect to competitors; too many, and the secondary market premiums collapse, removing the asset-appreciation narrative. Currently, the valve functions because Porsche maintains roughly 20 percent sports car production against 80 percent SUVs. As the company approaches 500,000 units, maintaining the allocation scarcity for 911s while feeding volume demand for Macans becomes mechanically difficult. The factories face pressure to convert sports car lines to SUV production, or to increase 911 output to justify fixed costs, either of which breaks the scarcity calculus.
The allocation system also creates dealer network dependencies that introduce fragility. Porsche dealers operate on thin new-car margins for volume models, surviving primarily on service revenue and used-car operations. The 911 allocations represent their profit centers, arking up limited-production models or bundling them with high-margin options. If SUV volume saturates markets and 911 allocations increase to support dealer profitability, the scarcity premium evaporates. The dealer network then faces the same margin compression as mainstream luxury brands, potentially triggering network consolidation or discounting wars that destroy pricing discipline across the portfolio.
The Tacit Density
The Stuttgart advantage deserves deeper examination as a specific form of industrial organization. When Porsche engineers the cooling system for a new 911 Turbo, they do not send specifications to a global bidding process; they drive to Mahle’s headquarters in Stuttgart-Bad Cannstatt, where engineers have collaborated on Porsche piston designs since 1920. For transmission components, they consult ZF Friedrichshafen, two hours away, where the specific metallurgical recipes for gears subject to 911 torque loads reside in institutional memory rather than patents.
This creates what economists call “tacit knowledge”, apabilities that cannot be codified in manuals or transferred through hiring individual engineers. A rival could hire away a Porsche chassis engineer, but that engineer cannot replicate the supplier relationships, the apprenticeship pipelines, or the testing facilities (Weissach, the R&D center, sits on ancestral Porsche land). The cluster generates a 15-20 percent efficiency advantage in development costs and a time-to-market advantage that compounds over product cycles.
However, this moat faces erosion from two directions. First, electrification shifts the critical engineering competencies from mechanical to electrochemical and software domains. Battery chemistry expertise concentrates in Asian suppliers (CATL, LG Chem) and Silicon Valley, not Stuttgart. Second, the talent pipeline depends on Germany’s vocational education system, which faces demographic decline and competition from tech industries. If the next generation of engineering talent prefers coding applications to calibrating dampers, the cluster
If the next generation of engineering talent prefers coding applications to calibrating dampers, the cluster degrades into a museum. The tacit knowledge that currently allows Porsche to resolve thermal management issues in rear-engine configurations, knowledge embedded in the specific heuristics of Stuttgart machinists who have worked only on performance powertrains, dissipates when the powertrain becomes a battery pack and inverter sourced from CATL or Samsung SDI. The geographic moat remains, but the water drains; the suppliers remain physically proximate, yet their relevance diminishes as the critical path shifts from Stuttgart to Shanghai and Silicon Valley.
This transition exposes the fragility of the authenticity transfer mechanism. The 911’s rear-engine layout, for all its dynamic compromises, required continuous innovation in casting techniques, cooling channel geometry, and vibration dampening, ngineering challenges that kept Porsche’s mechanical competence sharp and distinguishable. When that competence migrates to battery management software and user interface latency, Porsche competes against Tesla’s over-the-air update cycles and Apple’s UX design studios, battlegrounds where German engineering hierarchies move too slowly and Stuttgart’s cluster provides no advantage. The Cayenne and Macan can no longer inherit mechanical credibility because the mechanical era has ended; they become electric appliances differentiated only by interface design and charging network access, commodities wearing heritage badges.
The bear case sharpens here. Porsche’s pricing power assumes that “German engineering” remains a differentiable luxury attribute through the electric transition, but the transition may render German engineering irrelevant. When acceleration becomes instant and silent, the specific harmonics of a flat-six engine, carefully tuned over decades to produce a signature wail at 7,000 RPM, become nostalgic artifacts rather than functional advantages. The SUV buyer, previously willing to pay $30,000 extra for the inherited confidence of Stuttgart’s chassis tuning, discovers that electric torque vectors handle identically across brands, that one-pedal driving feels similar in a Taycan and a Model X, that the specific granular feedback through the steering wheel matters less when the vehicle drives itself through highway traffic.
At this inflection point, the volume strategy becomes a trap. With 500,000 units annually dependent on engineering distinctions that no longer exist, Porsche faces the worst of both worlds: the cost structure of a low-volume manufacturer, unionized German labor, expensive regional suppliers, heritage facility maintenance, without the pricing power of scarcity. The SUVs, stripped of their transfer halo, compete as premium products in a market where premium electric vehicles commoditize rapidly. The 911, neutered by electric mandates into a silent performer, loses the sensory signature that justified its existence as an irrational object; it becomes a styling exercise, a retro design wrapped around battery architecture shared with Audi e-trons.
The family ownership structure, previously the guardian of long-term thinking, may accelerate rather than prevent this decline. As the Piech and Porsche generations diversify their holdings and face estate liquidity needs, pressure mounts to maximize current cash flows from SUV volume before the depreciation curves flatten. This creates a perverse incentive: push Macan production higher, extract maximum margin during the transition window, accept brand dilution that manifests five years hence when those vehicles flood secondary markets and destroy residual values. The patient capital becomes impatient harvesting, recognizing that the engineering moat has dried and the premium era has peaked.
In this scenario, Porsche does not collapse; it simply normalizes. It becomes Audi-plus, a well-engineered Volkswagen Group brand commanding modest premiums for design and handling but not the extraordinary $110,000 average prices sustained by transferred authenticity. The factories remain in Stuttgart, but they produce expensive commodities rather than objects of cultural distinction. The 911 continues production as a heritage model, like the Jeep Wrangler or Ford Mustang, trading on nostalgia rather than technical supremacy, while the SUVs compete on lease rates with BMW and Mercedes. The pricing anomaly resolves into ordinary luxury economics, and the business that once defied the inverse curve between scale and exclusivity finally surrenders to the gravity that governs all manufactured goods.