Airbnb: How Inefficiency Became Fortune
Housing Insecurity as Business Model
In 2007, when Brian Chesky and Joe Gebbia inflated an air mattress in their San Francisco apartment and charged eighty dollars for the privilege, they stumbled upon a structural inefficiency that the hotel industry had spent a century ignoring. Hotels cannot scale to meet peak demand. During South by Southwest, the Oscars, or Apple’s developer conferences, nightly rates in desirable cities spike past one thousand dollars not because service improves, but because physical inventory hits a hard ceiling. Convention centers do not expand for single weekends; hotel towers cannot materialize for three-day events. The result is a predictable economic rupture: acute shortage, price gouging, and thousands of travelers priced out of the market or forced into distant suburbs.
Airbnb’s engine runs on converting this rupture into a marketplace. The supply side relies on financial necessity rather than commercial hospitality expertise. Hosts list spare rooms not because they aspire to hotelier careers, but because mortgage payments loom, rent consumes fifty percent of income, or economic precarity demands the monetization of every underutilized square foot. The 2008 financial crisis provided the perfect petri dish: suddenly, millions of homeowners faced negative equity and job loss, while travelers saw disposable income evaporate. Hotels remained expensive; spare rooms became necessary income. Airbnb did not create the housing crisis, but it built a thirty-eight-billion-dollar booking volume by instrumentalizing it.
The unit economics depend on this specific motivation. Unlike hotel development, which requires capital expenditure, zoning approvals, and construction timelines measured in years, Airbnb’s supply appears overnight. A host with a spare bedroom adds inventory without permits, architectural plans, or upfront investment beyond fresh linens. The platform extracts value through transaction fees, typically split between guest and host, while carrying none of the fixed costs of real estate ownership or maintenance. When demand spikes during peak events, the supply elasticizes upward as dormant rooms activate; when demand falls, the supply simply disappears back into residential use, leaving Airbnb with no stranded assets. It is a hotel chain without hotel risk, a real estate play without real estate debt.
The Payment Layer and the CouchSurfing Precedent
What separates Airbnb from the graveyard of failed hospitality marketplaces is not the concept of staying in strangers’ homes, CouchSurfing proved that desire existed, but the insertion of a centralized payment layer into the trust equation. CouchSurfing operated on verification fees alone, never capturing the transaction itself. Without payment processing, the platform could not algorithmically match supply and demand, could not monetize the exchange meaningfully, and ultimately could not sustain operations. It remained a nonprofit curiosity, unable to fund the safety infrastructure or customer service required at scale.
Airbnb’s decision to centralize payments created a data moat that competitors cannot easily replicate. By handling the financial transaction, the company captures granular intelligence on cancellation patterns, pricing elasticity, seasonal demand curves, and fraud markers. This data feeds the matching algorithm, which optimizes for conversion rates and minimizes the friction that plagued earlier attempts at peer-to-peer lodging. More importantly, the payment system creates switching costs. Hosts accumulate reviews and payment histories within Airbnb’s infrastructure; migrating to a competitor means abandoning that reputational capital and starting with zero verification. Guests, meanwhile, trust the platform’s escrow mechanisms and refund policies in ways they would not trust a direct bank transfer to a stranger.
The durability of this advantage lies in its self-reinforcing nature. Because Airbnb controls the transaction layer, it can insure stays, mediate disputes, and standardize the financial experience across 220 countries. Competitors entering today face a chicken-and-egg problem: without transaction volume, they cannot build the fraud detection systems necessary to convince users to pay through the platform; without those systems, users default to off-platform cash deals, depriving the competitor of both revenue and data. The payment layer is not merely a revenue mechanism; it is the architectural foundation upon which the trust infrastructure rests.
When Spare Rooms Become Shadow Hotels
Yet the marketplace faces an existential drift. Early growth relied on individuals renting spare rooms, uthentic, idiosyncratic, genuinely local. As the platform matured, professional operators with multiple listings began capturing disproportionate share of bookings and revenue. These are not homeowners monetizing surplus space; they are unlicensed hoteliers arbitraging regulatory gaps, leasing apartments specifically to sublet them on the platform. In major markets, a significant percentage of “hosts” now control dozens of listings, using dynamic pricing software and professional cleaning crews.
This professionalization threatens the structural differentiation that separates Airbnb from HomeAway or traditional hotels. The platform’s brand promise rests on authenticity: he unique, the local, the non-hotel experience. Professional operators erode this promise while simultaneously increasing regulatory scrutiny. A homeowner renting a spare room represents genuine sharing of existing resources; a real estate entrepreneur leasing twenty units to convert into short-term rentals represents something closer to a hotel chain, complete with the externalities, housing stock removal, neighbor disruption, safety concerns, that hotels are regulated to manage.
The tension is economic, not merely aesthetic. Professional operators are more price-sensitive and regulatory-aware than casual hosts. They calculate margins against hotel rates and are quicker to move inventory off-platform to avoid fees if take-rates rise. They also attract political opposition. When cities ban short-term rentals or impose registration requirements, they target the professional operators first, but the regulatory dragnet often captures the entire platform. If Airbnb evolves into a distribution channel for shadow hotels, it loses the political cover provided by the “sharing economy” narrative while retaining all the vulnerabilities of an unlicensed hospitality sector.
The Tax of Trust
The platform attempts to manage this drift through standardization, andatory safety features, enhanced cleaning protocols, algorithmic ranking systems that favor “Superhosts.” But standardization kills the magic that attracted early adopters. The appeal of Airbnb originally lay in its irregularity: the breakfast cooked by the host, the neighborhood recommendations unavailable in guidebooks, the architectural quirks of a real home. As the platform imposes operational rules to ensure quality and safety, it converges toward the hotel model it supposedly disrupted, yet without the regulatory compliance or liability structures that legitimate hotels maintain.
This creates a second tension between monetization and supply growth. Higher take-rates fund the safety infrastructure and customer service required to manage millions of listings, but they reduce host earnings and incentivize direct booking arrangements. A host paying a mortgage can absorb a thirteen percent platform fee; a professional operator running thin margins on multiple units will eventually build a direct relationship with repeat guests, bypassing Airbnb’s payment layer and eroding the data moat. The company must balance extracting sufficient value to justify its public valuation against preserving the incentive structure that motivates hosts to list exclusively.
The fragility is circular. To attract guests, Airbnb needs professional-quality photos, instant booking, and hotel-like reliability; to achieve this, it needs professional operators or professionalized casual hosts; but professionalization drives regulatory crackdowns and host defection. The platform is slowly taxing its own authenticity to pay for the scale required to justify its valuation.
Regulatory Arbitrage at Global Scale
The global expansion, 220 countries, 100,000 cities, with eighty-six percent of hosts outside the United States, exposes the business to regulatory fragmentation that the platform architecture cannot easily accommodate. Short-term rental laws vary not just by country but by municipality: Paris requires registration numbers, Berlin bans entire-home rentals without permits, New York has effectively prohibited most short-term listings through strict enforcement of existing housing codes. Each jurisdiction represents a potential supply shock.
Unlike technology platforms that can fragment by region, offering different content libraries in different countries, Airbnb’s value depends on network density. A fragmented platform, where listings disappear in Berlin or Barcelona due to local bans, degrades the experience for global travelers and reduces the cross-border network effects that justify the company’s premium. Yet the company cannot easily adapt its model without breaking the unit economics. If it complies with hotel tax regimes and safety inspections in major markets, costs rise toward hotel levels; if it ignores local laws, it risks sudden supply destruction when enforcement arrives.
The regulatory risk is asymmetric. A city council vote can eliminate thousands of listings overnight, as happened in New York in 2023. The company has no countermeasure beyond lobbying and public relations campaigns emphasizing host economic dependency. But political sentiment shifts with housing affordability crises. As cities confront shortages, Airbnb’s inventory, particularly the professional operator segment, presents a tempting target for politicians seeking to return housing stock to residential use. The supply is not durable; it exists at the pleasure of regulators who increasingly view the platform as a contributor to housing scarcity rather than a solution to travel accommodation.
The Designer’s Eye for Economic Friction
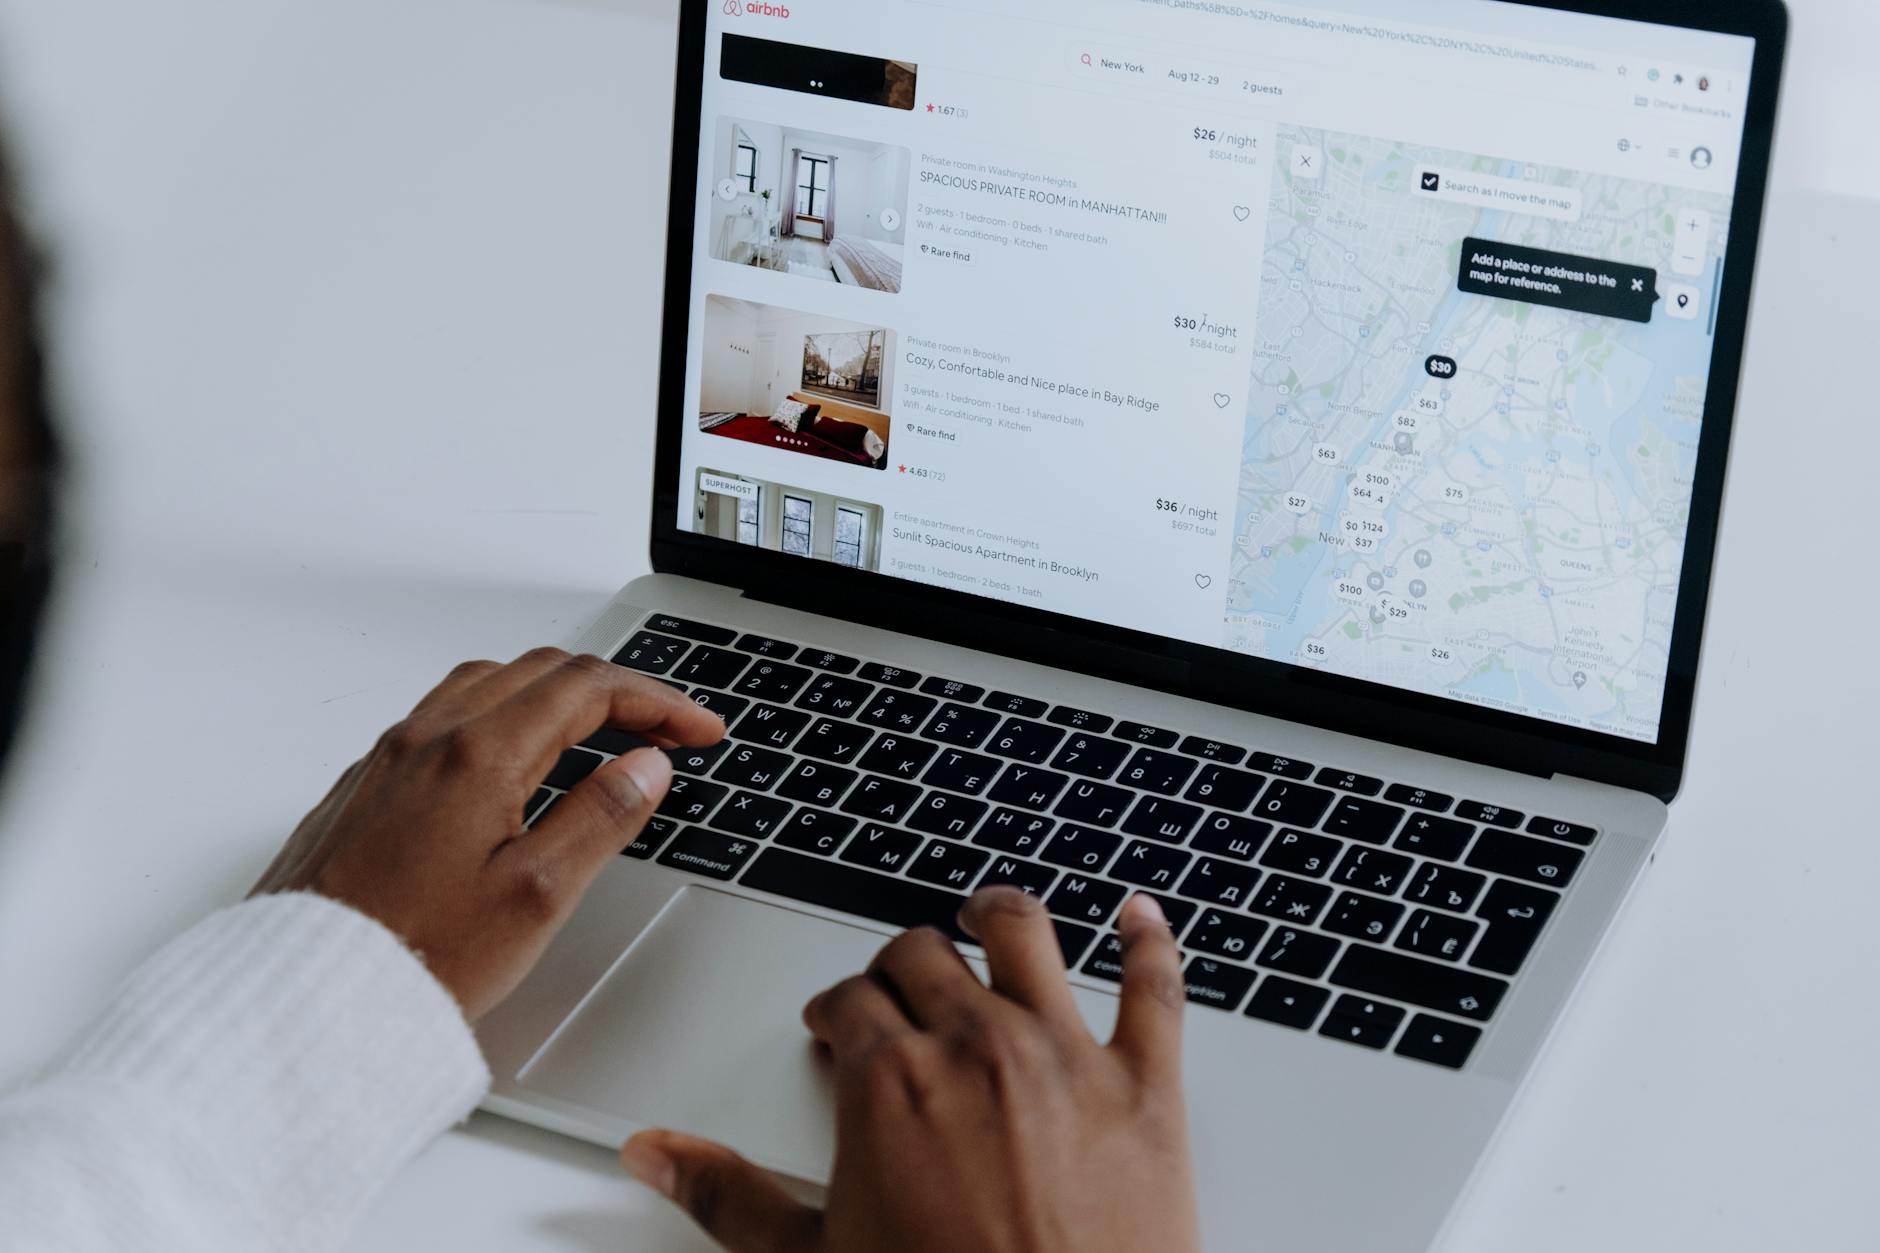
The company’s survival through these tensions owes something to the specific cognitive framework of its founders. Chesky and Gebbia graduated from the Rhode Island School of Design, not business schools or computer science programs. This background functioned as an economic variable in ways that traditional venture capital narratives often miss. When Paul Graham suggested they “go to New York” to meet their earliest users, the founders discovered through direct observation that poor photography, not location or price, was the primary constraint on bookings. They rented a camera and manually shot hosts’ apartments, realizing that trust in hospitality requires visual verification.
This insight, that friction in peer-to-peer markets is often perceptual rather than functional, shaped the platform’s architecture. The review system, the identity verification badges, the professional photo standards: these were design solutions to economic problems. They reduced the cognitive load required to transact with strangers, lowering the barrier to entry for mainstream travelers who would never have considered CouchSurfing’s unverified model.
The cereal box episode, selling limited-edition “Obama O’s” and “Cap’n McCain’s” to stay alive before Y Combinator, similarly demonstrated operational grit translated into economic survival. When Sequoia invested $585,000 for twenty-four percent of the company in 2009, they were not merely buying into a marketplace concept; they were buying into a team that had demonstrated the ability to manufacture liquidity events from absurd constraints. That small bet, representing just 0.1 percent of Sequoia’s fund, returned multiples because the founders treated survival as a design problem rather than a funding problem.
This design-centric approach continues to shape capital allocation. The company spends heavily on user experience improvements, photography tools, smart pricing algorithms, guest matching systems, that professional operators value more than casual hosts. The economic consequence is a platform increasingly optimized for the professionalized supply that threatens its regulatory position, because professionals generate the transaction volume required to amortize these technology investments.
The Maturation Assumption
Which brings the analysis to the fragile assumption underlying the business model: that host supply will remain elastic and politically defensible even as the platform matures and professionalizes. The bull case assumes that experiential travel trends will persist, that homeowners will continue monetizing spare capacity regardless of housing market conditions, and that regulatory fragmentation can be managed through local compliance teams without fragmenting the global platform.
But the data suggests a maturation trap. Bookings growth has decelerated from exponential to linear while costs balloon at accelerating rates. The company is spending heavily to acquire marginal growth, subsidizing supply acquisition in new markets while defending regulatory turf in established ones. If growth slows further and the cost structure does not adjust, the business faces a profitability cliff. The IPO valuation assumed continued network expansion; if that assumption breaks, the stock becomes difficult to defend.
More fundamentally, the model assumes that the housing insecurity that generates supply is a permanent feature of the economic landscape rather than a cyclical or politically contingent condition. If mortgage rates stabilize, if housing supply increases, if cities enforce rental laws strictly, the spare rooms that power the platform may simply return to being bedrooms. The business extracts rent from a structural mismatch between housing costs and wages; if that mismatch narrows, the engine stalls.
Airbnb built a global hospitality empire without laying a single brick, converting the financial precarity of homeowners into travel accommodation for the price-sensitive. It solved the trust problem that killed its predecessors by controlling the payment layer, creating a data moat that competitors struggle to cross. Yet the platform now navigates a narrowing corridor: professionalizing to satisfy growth expectations while maintaining the authentic, local character that differentiates it from hotels; extracting fees sufficient to justify public market valuations while keeping hosts from defecting to direct bookings; expanding globally while surviving regulatory assaults in its most profitable markets. The spare room was always a temporary asset, activated by economic necessity. The question is whether Airbnb can transition to a sustainable model before the necessity that created it subsides, or before the regulators who tolerated it during scarcity decide that housing stock belongs to residents, not to travelers.
The spare room was always a temporary asset, activated by economic necessity. The question is whether Airbnb can transition to a sustainable model before the necessity that created it subsides, or before the regulators who tolerated it during scarcity decide that housing stock belongs to residents, not to travelers.
The Professional Operator’s Arithmetic
To understand the compression facing the platform, examine the specific economics of the host who lists not a spare bedroom but a portfolio of units acquired specifically for short-term rental. In Barcelona’s Gothic Quarter or Lisbon’s Alfama, these operators lease apartments under standard residential contracts, typically twelve months with renewal options, then immediately list them on Airbnb at triple the daily rate required to cover rent, utilities, and platform fees. A two-bedroom apartment leasing for €1,800 monthly generates approximately €60 per night in fixed costs; at average daily rates of €180 during peak season and €120 during troughs, the operator clears margin while carrying vacancy risk that hotels manage through revenue management systems far more sophisticated than Airbnb’s host-facing tools.
This arbitrage depends on regulatory asymmetry. The professional operator extracts hotel economics while avoiding hotel taxes, safety inspections, commercial insurance requirements, and zoning restrictions. They also avoid the capital intensity that constrains traditional hospitality; no construction loans, no franchise fees, no property management agreements with asset owners. The inventory appears and disappears with lease cycles, creating a floating supply of pseudo-hotels that can retreat to long-term residential markets when short-term demand falters, or conversely, flood the short-term market when long-term rental demand softens.
Airbnb’s algorithm recognizes and rewards this behavior. Professional operators achieve “Superhost” status faster than casual hosts because they optimize for the metrics the platform prioritizes: response time under an hour, acceptance rates near one hundred percent, cancellation rates near zero. They invest in professional photography, dynamic pricing software, and automated messaging systems. The algorithm, trained on conversion data, surfaces their listings higher in search results because they convert browsers to bookers more reliably than the casual host who might decline a request due to a family visiting that weekend. The platform becomes a selection mechanism for professionalization, accelerating the very drift that threatens its regulatory position.
The economic consequence is a concentration of supply that behaves differently than the platform’s origin myth suggests. When cities impose registration requirements or booking caps, professional operators calculate the cost of compliance against the cost of exit. A host with a single spare room might absorb the friction of registration, background checks, and safety inspections to preserve supplemental income; a professional operator with twenty units facing twenty separate compliance processes, potential fines, and the risk of lease termination by landlords discovering the subletting simply shifts inventory to other platforms or returns units to the long-term market. The supply that drives volume is also the supply most likely to evaporate under pressure, leaving Airbnb with the high-fixed-cost infrastructure of customer service, trust and safety teams, and technology development amortized over a shrinking transaction base.
The Take-Rate Tightrope
The platform’s extraction mechanism, the combined service fee typically ranging from fourteen to sixteen percent split between guest and host, sits at the center of a tension that grows more acute as the supply base professionalizes. For the casual host monetizing spare capacity, the fee represents found money; for the professional operator running spreadsheet models, the fee represents a variable cost that competes with direct booking channels.
Consider the host with a cabin in Gatlinburg, Tennessee, or a beach condo in Destin, Florida, arkets where Airbnb dominates awareness but where repeat guests are common. The first transaction occurs through the platform: the guest discovers the property, pays the service fees, and the host pays the three percent host fee. The experience satisfies. For the second booking, the host and guest face a coordination problem. If they transact directly, the host captures the full nightly rate without the three percent haircut; the guest avoids the guest service fee, often six to twelve percent of the booking subtotal. The savings for a week-long summer rental can exceed $400. The only barrier is trust, an the guest verify the host’s legitimacy without the platform’s identity verification and payment protection?
As professional operators dominate, they build brand equity that reduces this barrier. The Gatlinburg cabin becomes “Mountain View Lodge” with its own Instagram presence, its own booking website, its own Stripe payment processing. The host still lists on Airbnb to fill shoulder-season gaps, but peak bookings migrate to direct channels where the take-rate is zero. Airbnb becomes expensive customer acquisition, not a transaction infrastructure. The data moat that once protected the platform, reviews, payment histories, verification badges, erodes as hosts accumulate reputation that transcends the platform.
The company faces a strategic trap. Lowering take-rates to prevent defection compresses margins and reduces the capital available for the safety and verification infrastructure that justified the fees initially. Raising take-rates to fund growth accelerates the professional host migration to direct booking. The equilibrium depends on maintaining sufficient friction in direct coordination, eeping the trust infrastructure valuable enough that even sophisticated hosts prefer the fee-laden certainty of the platform to the fee-free uncertainty of independent transactions. But as professional operators accumulate review volume and invest in their own credibility systems, that friction diminishes.
The Geography of Enforcement
Regulatory fragmentation presents not merely a political risk but an operational complexity that strains the platform’s centralized architecture. In Barcelona, enforcement relies on a registration number system where hosts must display city-issued permits in listings; algorithms scrape Airbnb for unregistered properties, and fines flow to hosts rather than the platform. In Paris, the “120-day rule” caps entire-home rentals at four months annually, enforced through tax data cross-referencing utility bills and platform reports. In Amsterdam, the “30-day rule” operates similarly but with different caps and different verification mechanisms. New York’s Local Law 18 effectively requires hosts to be present during stays, eliminating entire-home rentals, enforced through a registration portal that Airbnb must verify against.
Each jurisdiction creates a distinct compliance surface. The platform cannot simply apply a global standard; it must geofence restrictions, build location-specific user flows, and maintain legal entities capable of absorbing local liability. The operational cost scales with regulatory complexity while the revenue from these markets risks step-function declines when enforcement tightens.
The specific mechanics of enforcement reveal the fragility of supply. When Barcelona cracked down in 2016 following mass tourism protests, supply did not gradually decline; it collapsed in specific neighborhoods as professional operators moved inventory to long-term rentals or sold properties. The platform’s network effects work in reverse: as listings disappear in the Gothic Quarter, the guest searching for “Barcelona” sees higher prices and fewer options, converting instead to hotels or choosing different destinations. The density that creates liquidity also creates vulnerability; remove twenty percent of listings in a concentrated geographic area and the remaining eighty percent lose the cross-booking effects that made the platform attractive.
The regulatory risk is compounded by the company’s public market status. As a private company, Airbnb could absorb market closures as cost-of-doing-business, retreating from jurisdictions while maintaining growth narratives. As a public company with quarterly disclosure requirements, sudden supply destruction in major markets creates immediate valuation pressure. The stock trades on growth assumptions; a regulatory decision in Berlin or Tokyo that eliminates thousands of listings translates directly into guidance revisions and multiple compression.
The Trust Infrastructure Under Load
The platform’s central claim, that it has solved the stranger danger problem through reviews, identity verification, and secure payments, faces scaling pressures that manifest in subtle but economically significant ways. As the platform grows from thousands to millions of listings, the review system experiences inflation. Hosts understand that a single negative review can reduce occupancy rates by twenty percent; they respond by screening guests more aggressively, offering refunds for negative reviews, or simply refusing to review guests who might retaliate. The information content of the average review declines as the social pressure to be “nice” increases. A five-star rating system where the modal experience receives 4.8 stars loses discriminatory power; guests cannot distinguish adequate properties from exceptional ones, and the algorithm loses the granular data required for effective matching.
Simultaneously, the cost of maintaining trust infrastructure grows non-linearly. Identity verification, background checks, and fraud detection require human review at scale. The company employs thousands of trust and safety agents to mediate disputes, verify documentation, and investigate incidents. As professional operators generate more transactions per host, the platform achieves some economies of scale in verification, but as the geographic footprint expands into jurisdictions with limited digital identity infrastructure, verification costs increase. A host in rural Montana might verify through standard credit checks; a host in Jakarta or Nairobi requires alternative data sources, manual document review, and higher fraud detection margins.
The specific failure modes reveal the brittleness of the trust layer. When a high-profile incident occurs, a hidden camera discovered, a assault during a stay, a property destroyed during a party, the platform’s response must balance host privacy against guest safety, often with incomplete information. Each incident generates regulatory scrutiny and civil liability exposure. The company maintains liability insurance for hosts, but the claims experience affects renewal rates and coverage limits. If the actuarial data reveals that short-term rentals generate higher incident rates than hotels, insurance costs rise, compressing host margins and potentially forcing fee increases that accelerate the defection described earlier.
The algorithmic matching that substitutes for brand reputation in traditional hospitality also creates concentration risks. When the algorithm identifies a “perfect match” between guest preferences and property characteristics, it surfaces that property repeatedly, creating winner-take-all dynamics within micro-markets. A specific cabin in Lake Tahoe might capture thirty percent of algorithmic impressions for “family-friendly” searches, while an adjacent property with nearly identical characteristics receives five percent. This concentration benefits the platform through higher conversion rates but increases the systemic risk when that high-performing property experiences a safety incident or regulatory removal. The algorithm’s optimization for efficiency reduces redundancy in the supply network.
Hotels and the Counter-Attack
The traditional hospitality industry’s response to Airbnb’s growth reveals the durability of the hotel model despite the platform’s apparent advantages. Rather than simply lobbying for regulatory restrictions, though they have done that, major hotel chains have launched their own “home rental” platforms. Marriott’s Homes & Villas, Hyatt’s partnership with Oasis, and independent platforms like Sonder and Blueground represent the professionalization of alternative lodging under hotel regulatory frameworks.
These competitors operate with explicit hotel licenses, paying occupancy taxes, maintaining commercial insurance, and adhering to safety codes. They offer the standardization that Airbnb struggles to impose without alienating its host base. For business travelers, who represent higher daily rates and more predictable demand than leisure travelers, the hotel-branded alternative lodging provides expense report compatibility, loyalty program integration, and corporate liability coverage that Airbnb’s heterogeneous supply cannot match.
The competitive dynamic shifts as Airbnb moves upmarket. The platform’s early growth relied on price-sensitive leisure travelers comparing Airbnb rates against mid-market hotels. As fees, cleaning charges, and service costs accumulate, often making an Airbnb more expensive than a comparable hotel for short stays, the value proposition relies increasingly on space (multiple bedrooms, kitchens) and location (residential neighborhoods rather than commercial districts). But business travelers, who drive weekday occupancy in major markets, prioritize location near convention centers, consistent service standards, and seamless check-in over residential amenities. The hotel chains’ entry into the home rental space captures this segment with regulatory compliance that Airbnb cannot easily replicate without alienating its core host supply.
The Online Travel Agency (OTA) dynamics further complicate the competitive landscape. Booking Holdings and Expedia Group control the dominant hotel distribution channels and have integrated alternative lodging into their metasearch algorithms. When a traveler searches for “Amsterdam hotel,” they now see traditional hotels alongside Airbnb-style listings, often with price parity or hotel discounts that reflect the hotels’ direct booking campaigns. Airbnb’s growth required capturing travelers before they reached the OTA search phase; as the platform matures and prices converge with hotels, that capture becomes more expensive, requiring higher marketing spend per booking acquired.
The Cyclical Sensitivity
The platform’s performance exhibits high correlation with macroeconomic conditions that affect both supply and demand simultaneously. During economic expansions, housing prices rise, increasing the mortgage pressure that motivates casual hosting while disposable income growth drives travel demand. During contractions, the supply of desperate hosts increases, foreclosure threats activate dormant listings, while demand collapses as corporate travel freezes and leisure trips postpone. But the specific nature of the 2008 crisis that birthed Airbnb, simultaneous housing crash and travel demand shock, may not repeat; future recessions might feature different correlations.
Rising interest rates present a specific threat to the professional operator model. As mortgage rates increase, the arbitrage between long-term rental yields and short-term rental yields narrows. A property that cash-flowed positively as an Airbnb but not as a long-term rental at three percent mortgage rates might negative-carry at seven percent rates. Professional operators facing refinancing pressure must either increase nightly rates, reducing occupancy against hotel competition, or exit the market, reducing supply precisely when economic uncertainty might otherwise drive demand for cheaper accommodation alternatives.
The casual host supply also exhibits interest rate sensitivity, but inversely. As home equity lines of credit become more expensive and household budgets tighten under inflation, the supplemental income from hosting becomes more necessary, not less. However, if housing prices decline significantly, homeowners facing negative equity might sell properties rather than rent them short-term, removing supply permanently. The platform’s supply curve slopes upward with economic distress only to a point; beyond that point, asset liquidation removes inventory entirely.
The Design Constraint on Operations
The founder’s design background continues to shape operational decisions in ways that create both competitive advantage and structural cost. The emphasis on photography, user interface elegance, and the “magical” aspects of discovery, curated wish lists, experiential categories like “OMG!” or “Treehouses”, drives marketing efficiency but also operational complexity. Each new category requires algorithmic tagging, quality control, and merchandising effort. The focus on high-quality creative assets creates a content production burden that scales with listing growth.
This aesthetic imperative also influences the company’s approach to regulation. Rather than presenting itself as a utility infrastructure for lodging transactions, dry, functional, standardized, Airbnb markets the “community” and “belonging” aspects of the platform. This narrative served well during growth phases, attracting hosts who might not have listed on a purely commercial platform. But during regulatory conflicts, the narrative becomes a liability. Cities find it easier to ban “community” platforms that violate housing codes than to regulate “infrastructure” platforms that facilitate commerce. The company’s brand positioning as a community rather than a marketplace creates cognitive dissonance when the economic reality, transaction fees, professional operators, commercial-scale hosting, becomes apparent to regulators.
The specific allocation of capital reflects this tension. The company invests heavily in product and engineering, roughly forty percent of operating expenses, while underinvesting in regulatory technology relative to the risk exposure. The platform can detect fraudulent payments with sophisticated machine learning but struggles to detect illegal listings in jurisdictions with complex housing codes. This misallocation stems from the design-centric culture that prioritizes user experience over compliance automation, assuming that user experience will generate political capital sufficient to defer regulatory enforcement.
The Endurance Test
The fundamental question facing the business is whether the network effects, once established, prove durable enough to survive the maturation of both supply and demand. The platform has achieved sufficient density in major markets that guests default to Airbnb as a search behavior, reducing customer acquisition costs through brand recognition. Hosts, even professional ones, find that Airbnb’s organic traffic exceeds what they can generate through independent marketing, justifying the take-rate as a marketing expense rather than a transaction tax.
But this endurance depends on the absence of superior alternatives. If hotel chains successfully integrate home rentals into their loyalty ecosystems, or if a consortium of professional operators launches a cooperative platform with lower fees, the switching costs that appear substantial for casual hosts might prove trivial for professionals. The data moat, the historical reviews, the preference algorithms, the fraud patterns, has value only if the underlying transaction volume justifies the infrastructure costs required to maintain it.
The platform’s ultimate fate may hinge on its ability to transition from a marketplace matching spare capacity with price-sensitive travelers to a infrastructure layer for professional lodging operators, accepting the regulatory compliance and standardization that such a transition requires. This would mean abandoning the “spare room” mythology, embracing hotel-like regulation, and competing directly with Booking.com and Expedia on distribution efficiency rather than on authenticity and community. Such a transition would validate the early investors who saw the platform’s potential but would represent the final commoditization of the model, reducing Airbnb to a high-fee OTA with better photography.
Alternatively, the platform might retreat to a niche position, ominant in true vacation rental markets (beach houses, mountain cabins) where the hotel alternative never existed, while ceding urban short-term rentals to hotels and regulated professional operators. This would stabilize the business but at a fraction of the current valuation, accepting that the original vision of democratized hospitality cannot survive contact with municipal housing politics.
The economic engine continues to run on housing insecurity and regulatory arbitrage, converting the spatial surplus of the asset-poor into travel accommodation for the experience-seeking middle class. Whether that engine can be retrofitted for sustainability, hether the take-rate can fund compliance, whether the algorithm can maintain liquidity as professional supply fragments, whether the brand can survive its own standardization, emains the open question. The spare room was a temporary solution to a permanent problem of urban scarcity; the platform must now prove it is more than a cyclical beneficiary of housing crises, or it will follow the trajectory of earlier marketplace experiments that mistook macro tailwinds for structural moats.