British American Tobacco: When Sin Stocks Make Sense

Clearing the Air
In the winter of 2024, British American Tobacco offered investors something that should not exist in efficient markets: a ten percent dividend yield from a business converting eighty-eight percent of its operating income into free cash flow, with a gross margin of eighty-three percent. These are figures associated with software monopolies or patent-protected pharmaceuticals, not a two-hundred-year-old industry selling a product that has been banned from advertising for half a century and carries explicit death warnings on every package. The valuation, six times earnings, suggested the market had priced the enterprise as a liquidation candidate, a melting ice cube destined to return capital to shareholders until the last smoker extinguishes their final cigarette. Yet BTI is not liquidating. It is building. Behind the combustible cash engine that generates GBP 9.2 billion in annual operating cash flow against a mere GBP 500 million in capital expenditure, the company is constructing a parallel nicotine business, heated tobacco, vapor, and modern oral pouches, that grew thirty-five percent in European markets last year. The question is not whether BTI can pay its dividend next year. The question is whether this is a company transitioning from tobacco to nicotine, or simply the most efficient extraction mechanism ever devised for a declining natural resource. The answer depends on whether management can cannibalize its own eighty-three-percent-margin business before volume declines accelerate beyond the point where price increases can compensate, while preventing Philip Morris from capturing the reduced-risk market entirely.
### The Oligopoly That Regulators Built
The modern cigarette industry is a creature of litigation. The 1998 Master Settlement Agreement between major tobacco companies and forty-six U.S. states did more than impose a perpetual liability of roughly $9 billion annually across the industry; it erected a regulatory barricade so high that no rational capitalist would attempt to scale it. The MSA effectively taxes new entrants at the same rate as incumbents while denying them the decades of brand equity and retail shelf positioning that allow price increases to pass through to consumers. When combined with comprehensive advertising bans that prevent the creation of new consumer brands, the regulatory environment has transformed combustible tobacco from a competitive market into a static oligopoly.
BTI operates within this structure as the second-largest player in the United States, controlling Newport, Camel, Kent, Dunhill, Pall Mall, and Lucky Strike. These are not merely product names; they are leaseholds on finite retail space. A convenience store has limited room behind the counter, and the brands occupying that space have remained essentially unchanged for generations. The economic moat is not technological or operational; it is legal and psychological. The law prevents new competitors from speaking to consumers, while nicotine dependency ensures that existing consumers remain price-inelastic. This allows BTI to implement what the industry calls “price-pack architecture”, aising prices faster than volumes decline, thereby maintaining or growing revenue even as the number of cigarettes sold shrinks by two to four percent annually.
The mechanics are stark. In 2024, BTI generated GBP 24 billion from combustible tobacco. With gross margins of eighty-three percent and operating margins holding steady at forty percent, the business requires virtually no reinvestment. Factories depreciate; brands do not. The cash conversion cycle is immediate. Unlike industrial manufacturers who must fund working capital and capital expenditures from operating cash flow, BTI’s tobacco operation throws off cash that can be directed elsewhere immediately. This is the economic engine: a legally protected ability to raise prices on an addicted customer base, with no threat of new entry, minimal maintenance requirements, and a cost structure frozen by the symmetric burden of the MSA.
### Depreciating Assets, Appreciating Brands
The acquisition of R.J. Reynolds between 2004 and 2017 cost BTI roughly GBP 50 billion and loaded the balance sheet with debt. For most industrial companies, such leverage would constrain strategic flexibility, forcing a choice between deleveraging and investing for growth. BTI has done both simultaneously. The company has reduced its debt burden while maintaining a GBP 5 billion annual dividend, funded entirely by free cash flow that exceeds ninety percent of operating profit. This is not financial engineering; it is the structural reality of a business that sells a consumable with no research and development requirements, no inventory obsolescence, and no manufacturing innovation.
The capital allocation discipline required to manage this transition is the primary economic function of BTI’s leadership. In a business with excess cash, the temptation is always to reinvest in empire-building, o chase growth in adjacent markets or overbuild manufacturing capacity. The dividend serves as a commitment device, forcing management to distribute cash that cannot be profitably reinvested in the core business. Simultaneously, the gradual paydown of acquisition debt reduces the cost of capital and insulates the company against refinancing risk in an era of higher interest rates. The GBP 50 billion Reynolds purchase was expensive, but it consolidated the oligopoly, giving BTI control of Newport, the leading menthol brand, and the associated logistics network that now serves as the distribution spine for next-generation products.
This cash generation is durable precisely because it is boring. Cigarette manufacturing involves no breakthroughs. The product today is materially identical to the product of twenty years ago, meaning capital equipment purchased decades ago continues to generate returns without replacement. The only significant capital requirement is the leaf inventory, which turns rapidly. The result is a business that can fund both a double-digit dividend yield and a parallel corporate build-out without straining its balance sheet, rovided the core combustible franchise does not collapse faster than the historical rate of two to four percent annual volume decline.
### The Geography of Nicotine Transformation
While BTI extracts cash from the American and European combustible markets, it is constructing a very different company in other geographies. In Japan, thirty percent of BTI’s revenue already comes from heated-tobacco products, primarily through its Glo device. In Scandinavia, particularly Sweden and Norway, the company dominates the modern oral category with its VELO brand, which grew thirty-five percent in Europe last year. These markets represent a proof of concept for the harm-reduction thesis: that smokers will switch to reduced-risk products if the products are available, culturally accepted, and sufficiently satisfying to replace combustibles.

The geographic divergence is crucial because it reveals BTI’s underappreciated structural advantage. While Philip Morris International has captured the American oral market with ZYN, distributed through a partnership that gives PM control of the fastest-growing nicotine segment in the United States, BTI owns the equivalent position in Europe. VELO is the category leader across Scandinavia and much of the continent, providing BTI with a revenue stream that is growing rapidly while the U.S. oral market remains contested. This geographic diversification creates optionality. If the U.S. Food and Drug Administration delays or rejects approval for VELO 2.0: he company’s next-generation pouch product designed to compete with ZYN, TI can still fund its global transition through European profits. Conversely, if VELO 2.0 gains U.S. approval, BTI has a product that has already proven its manufacturing and marketing efficacy in Scandinavia, ready to challenge ZYN’s dominance.
The strategic map is bifurcated. In the United States, BTI is playing defense, trying to maintain pricing power in combustibles while disposables and ZYN erode market share. In Europe and Japan, it is playing offense, converting smokers to heated tobacco and oral pouches at rates that suggest these markets will eventually be majority next-generation. The company reports twelve percent of total revenue from reduced-risk products today, compared to Philip Morris’s thirty percent. Closing that gap is the explicit strategic priority, but doing so requires resources that must be diverted from the dividend or debt paydown, r extracted from the combustible business at an accelerated rate.
### Cannibalizing the Eighty-Three Percent Margin
Here lies the defining structural constraint. BTI cannot grow into the future without destroying the economics of the present. Every smoker who switches from a Newport cigarette to a VELO pouch moves from an eighty-three-percent-margin product to a product with significantly lower margins, ossibly half, possibly less, depending on regulatory taxation and manufacturing scale. The transition is not revenue-neutral; it is margin-destructive in the short term. Yet if BTI delays the transition to protect its combustible margins, Philip Morris captures the switching consumers entirely, leaving BTI with neither the old business nor the new one.
The tension is temporal. BTI needs the combustible business to decline slowly enough that price increases can offset volume losses for another decade, generating the cash required to build out next-generation manufacturing, marketing, and regulatory compliance. But if the company markets next-generation products too aggressively, it risks accelerating the decline of its high-margin business before the new products achieve equivalent profitability. Philip Morris has accepted this trade-off more readily, guiding for sixty percent of its volume to come from next-generation products and watching IQOS recently surpass Marlboro as its largest brand. BTI, with its heavier debt load and higher dividend yield, has less room to absorb the margin compression that comes with rapid transition.
The arithmetic is unforgiving. If BTI maintains its current twelve-percent next-generation revenue mix while the combustible business shrinks at historical rates, the company remains a cash cow. If combustible volumes decline ten percent annually, as they did in the United States in 2023, the price-volume ratchet breaks. BTI cannot raise prices fast enough to compensate for that rate of volume loss without driving remaining consumers to black markets or alternative products. The entire valuation thesis assumes that the 2023 U.S. volume decline was an anomaly, not a new baseline. If ten percent becomes the norm, the dividend becomes a return of capital rather than a return on capital, and the debt paydown stalls.
### When Volume Breaks the Price Ratchet
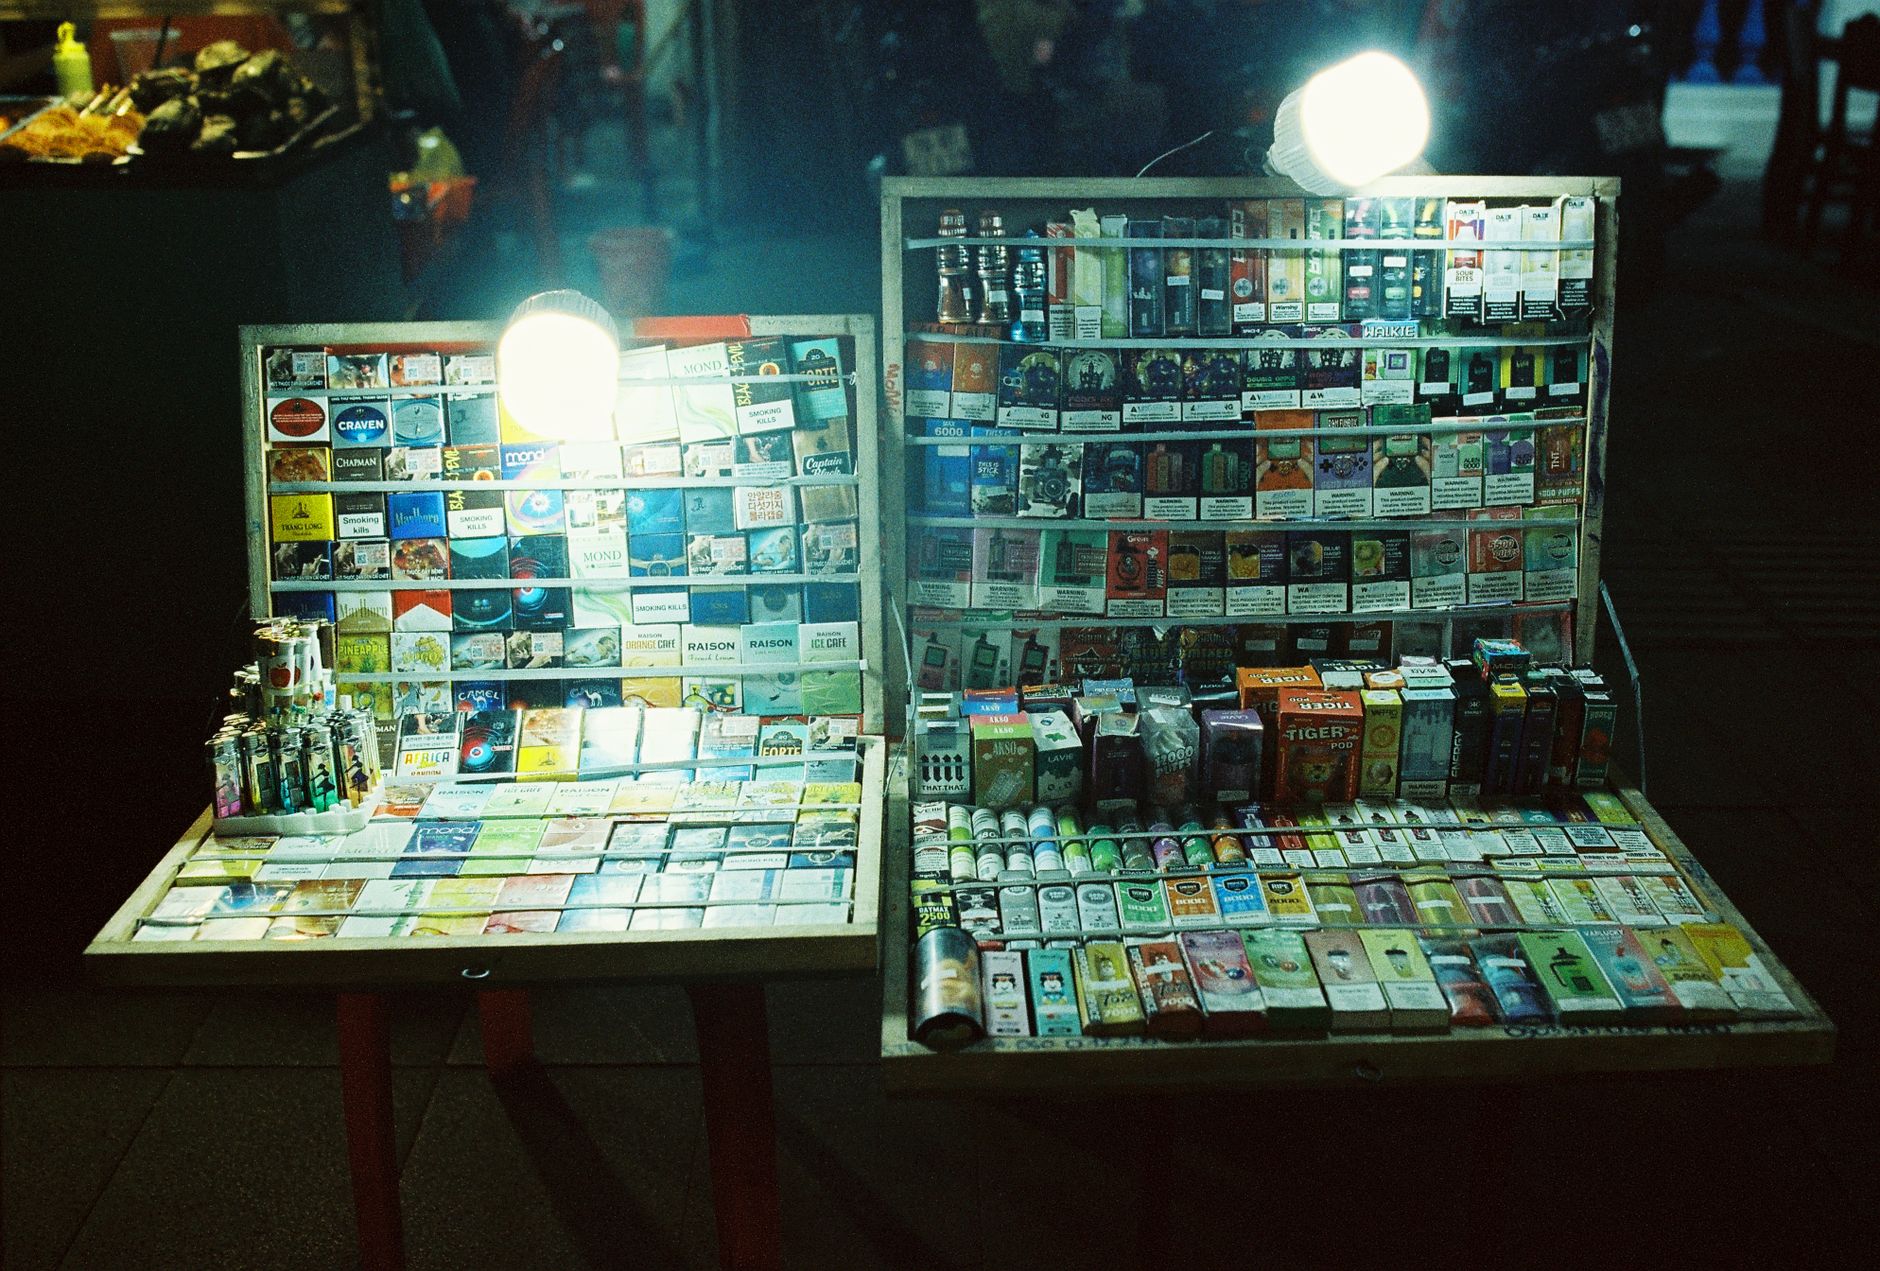
The acceleration risk in the United States is not merely a matter of consumer preference shifting gradually toward health consciousness. It is being driven by a regulatory blind spot that threatens the oligopoly’s pricing power. Approximately half of the U.S. vapor market consists of untracked, non-FDA-approved disposable devices sold in flavors and at price points that bear no relation to the taxed, regulated cigarette market. These products, largely manufactured in China and distributed through channels outside traditional tobacco retail, are capturing price-sensitive consumers, particularly younger demographics, at a rate that disrupts the industry’s ability to manage decline.
If a smoker switches from Marlboro to a five-dollar disposable vape, BTI loses the customer. If a smoker switches from Marlboro to Newport because Newport raised prices slightly less, BTI retains the customer in the oligopoly. But if the smoker leaves the regulated tobacco ecosystem entirely for the gray-market vape economy, the price discipline of the oligopoly ceases to function. The historical model assumes that nicotine consumers have limited alternatives; the proliferation of disposable vapes breaks that assumption. BTI needs regulation to crush the disposable market, through flavor bans, marketing restrictions, or enforcement actions, while simultaneously hoping that regulation does not extend to its own next-generation products. It is a delicate position: the company requires a stricter regulatory environment to protect its combustible margins, but not so strict that it cannot launch VELO 2.0 or maintain flavored offerings that differentiate modern oral products from traditional tobacco.
### The FDA and the Multiple Expansion
Beyond the immediate cash flows, the next-generation transition represents a bet on narrative rehabilitation. BTI trades at six times earnings, a multiple that reflects its status as an ESG pariah, xcluded from many institutional portfolios, shunned by sustainability mandates, treated as a secular decline story regardless of its cash generation. Philip Morris, with thirty percent of revenue from reduced-risk products, commands a multiple roughly twice as high, fourteen times earnings, as investors begin to price in the possibility that nicotine companies can become harm-reduction companies rather than tobacco companies.
For BTI to re-rate from six to twelve or fourteen times earnings, the market must accept that the company is transitioning from a manufacturer of carcinogenic combustibles to a supplier of regulated recreational nicotine products with significantly lower health risks. This narrative shift depends entirely on regulatory validation. VELO 2.0 must receive FDA approval as a Modified Risk Tobacco Product, allowing BTI to market it as a safer alternative to cigarettes. Flavor bans must be targeted narrowly enough that modern oral products retain their appeal compared to combustibles. And critically, the public health community must accept that reduced-risk products reduce population-level harm rather than merely maintaining nicotine addiction in a different form.
If these conditions are met, BTI’s valuation could double even if earnings remain flat, as the terminal risk premium compresses. If they are not met, f the FDA delays VELO 2.0 indefinitely, or if flavor bans eliminate the product category’s growth driver, or if anti-tobacco advocates successfully argue that nicotine pouches represent a new gateway to addiction, hen BTI remains trapped at six times earnings, a cash flow vehicle with no growth story and a declining terminal value. The harm-reduction narrative is not merely public relations; it is the mechanism by which the company escapes the valuation gravity of the cigarette business.
### The Dividend as a Prison and a Compass
In this environment, capital allocation becomes the primary strategic variable. The management team faces constant pressure to either accelerate next-generation investment, potentially sacrificing the dividend to fund a rapid transition, or to harvest the combustible business aggressively, milking the cash cow until it dies. The ten percent yield serves as a commitment to a middle path: maintaining shareholder returns while funding the transition organically through free cash flow. This discipline is fragile. If the board cuts the dividend to fund a desperate catch-up in next-generation marketing, the stock collapses and the cost of equity rises. If the board maintains the dividend while underinvesting in VELO and heated tobacco, Philip Morris locks up the market.
The GBP 50 billion Reynolds acquisition taught BTI the cost of overpaying for growth. The current strategy reflects a contrarian patience: using European and Japanese markets to refine next-generation products and manufacturing efficiency while waiting for U.S. regulatory clarity on VELO 2.0, rather than burning cash on a marketing war against ZYN that it cannot win without FDA approval. This is leadership functioning as an economic variable: he ability to resist the pressure to “do something” visible while maintaining the financial flexibility to scale rapidly once the regulatory path clears.
Yet patience assumes time. The 2023 U.S. volume data suggests the clock may be running faster than anticipated. If disposable vapes and oral pouches continue to capture volume outside the tracked, taxed, oligopolistic cigarette market, BTI’s ability to raise prices erodes. The company then faces the worst of both worlds: declining combustible volumes that cannot be offset by price, and next-generation products that lack the scale to replace the lost profit. The dividend, currently covered by free cash flow, would then require debt financing or payout cuts.
British American Tobacco is therefore a leveraged bet on the slope of decline. If the historical two-to-four-percent annual volume reduction in combustibles holds, and if next-generation products can capture fifty percent of revenue within a decade at margins approaching forty percent, then the company is absurdly cheap, offering a ten percent yield while building a growth business in parallel. If volume declines have structurally accelerated to high-single-digits or worse, or if next-generation margins remain permanently depressed by regulation and competition, then the enterprise is indeed a melting ice cube, returning capital to shareholders until the physics of demand destruction overwhelm the pricing power of the oligopoly.
The air is clearing, but not in the way public health advocates intended. The smoke is being replaced by vapor and pouches, by VELO in Stockholm and Glo in Tokyo, by a company trying to transform itself from a pariah into a utility. Whether BTI succeeds depends on whether it can maintain the cash extraction from its legacy business long enough to complete the transition, without being undercut by gray-market alternatives or outrun by competitors who accepted the margin pain of cannibalization earlier. The ten percent dividend is not a gift; it is a reminder of the cost of time.
The Japanese market offers the clearest evidence of what happens when the transition succeeds, and why success there does not guarantee success elsewhere. In Tokyo and Osaka, heated-tobacco devices have captured thirty percent of the nicotine market not because of marketing brilliance, but because of infrastructure density. The convenience stores, Seven-Eleven Japan, Lawson, FamilyMart, dedicate significant counter space to Glo and IQOS consumables, creating a distribution intensity that mirrors the cigarette displays of the twentieth century. The Japanese consumer did not abandon combustibles because of health warnings; they switched because the alternative was equally available, socially acceptable, and delivered the same pharmacological effect without the ash. This suggests that the reduced-risk transition is not primarily a story of consumer education or moral awakening, but of shelf space and regulatory permission. Where regulators permit next-generation products to occupy the same physical and cultural space as cigarettes, substitution occurs at remarkable speed. Where they restrict them to vape shops or online channels, the products remain niche.
The Scandinavian experience with oral pouches reinforces this point with different variables. Sweden’s snus culture provided a pre-existing behavioral template, nicotine consumption without smoke, that modern oral products merely updated for a global palate. VELO’s thirty-five percent growth in Europe is concentrated in markets where oral tobacco was already normalized, not in markets where BTI must invent the category. This geographic unevenness creates a strategic problem: BTI’s next-generation revenue is currently dominated by markets with unique cultural or regulatory preconditions that do not export easily. Japan’s heated-tobacco success depends on a convenience-store density and urban compactness that characterize East Asian cities but not the sprawling exurbs of the American South. Scandinavia’s oral acceptance depends on a historical tolerance for smokeless tobacco that does not exist in Mediterranean or Anglo-Saxon markets. The company is not building one next-generation business; it is managing several distinct regional experiments, each requiring different regulatory outcomes, consumer education budgets, and manufacturing configurations.
The manufacturing economics of these products reveal why margin compression is structural rather than temporary. Combustible cigarettes are essentially commodity products with brand premiums. The tobacco leaf is sourced globally, blended to consistent specifications, and rolled into paper tubes with filters. The capital equipment is paid for, the processes are optimized over decades, and the scale efficiencies are massive. Heated-tobacco sticks, such as the Neo sticks consumed in Glo devices, require precise temperature-control engineering, specialized paper substrates that heat without burning, and complex flavor encapsulation that survives thermal stress. The manufacturing yield rates are lower, the raw material specifications are tighter, and the capital intensity is higher. Modern oral pouches involve pharmaceutical-grade nicotine extraction, food-safe pouch materials, and flavor stability challenges that cigarette manufacturers never faced. These are not merely different products; they are different industries, closer in operational profile to consumer packaged goods or over-the-counter pharmaceuticals than to traditional tobacco.
This operational complexity interacts dangerously with the regulatory timeline. VELO 2.0 represents BTI’s attempt to leapfrog ZYN in the American market, using a different nicotine delivery mechanism that the company claims produces faster satisfaction. But the product remains under FDA review, trapped in the pre-market tobacco application process that can extend for years without definitive guidance. Every month of delay allows ZYN to deepen its distribution relationships with American convenience stores, creating shelf-space inertia that becomes difficult to overcome even with a superior product. Philip Morris’s partnership with U.S. distributors gives ZYN preferential placement and promotional support that VELO cannot match without FDA authorization to market. The regulatory moat that protects BTI’s combustible business, preventing new cigarette entrants, now operates in reverse, preventing BTI from entering the fastest-growing nicotine category in its most important market.
The financial implications of this asymmetry are severe. If VELO 2.0 fails to gain approval, or if approval is delayed until 2026 or beyond, BTI’s next-generation strategy in the United States collapses. The company would be left with vapor products in a market where disposables dominate, and combustibles in a market where volumes are declining at ten percent annually. The cash flow that currently funds the dividend would then face a strategic fork: maintain the payout while the business contracts, or cut the dividend to fund a desperate attempt to acquire distribution share in oral products through pricing subsidies: war of attrition against Philip Morris that BTI is ill-equipped to win given its higher leverage and lower cash reserves.
The debt structure amplifies these risks in ways that the headline numbers obscure. While BTI has reduced the GBP 50 billion Reynolds acquisition debt significantly, the remaining obligations concentrate in specific maturity windows that coincide with the next-generation transition timeline. The company must refinance or repay substantial tranches of debt in the 2026-2028 period, precisely when the combustible cash flow may be peaking or declining, depending on volume trends. If the credit markets tighten, if tobacco ESG exclusions deepen or if recessionary conditions raise corporate borrowing costs, BTI could face a refinancing cliff that forces asset sales or dividend suspension regardless of operating performance. The current ten-year Treasury yield environment has already raised the cost of new issuance; a sustained period of higher rates would make the historical model of borrowing to acquire, then paying down with operating cash flow, prohibitively expensive for any future strategic moves.
Consider the specific mechanics of a bear case that remains underweighted in most analyses. Assume that U.S. combustible volumes continue declining at eight to ten percent annually, driven by disposable vape penetration and ZYN conversion. Assume further that FDA approval for VELO 2.0 is delayed until 2027, by which time ZYN has captured sixty percent of the oral market with exclusive distribution contracts. In this scenario, BTI’s U.S. revenue falls by forty percent over five years, while the next-generation products that might have offset this decline remain marginal. The pricing power in combustibles breaks down because the remaining smokers are increasingly price-sensitive, ither older consumers on fixed incomes or younger consumers comparing cigarettes to three-dollar disposables. The company cannot raise prices fast enough to offset the volume loss, and the operating margin compresses not merely because of mix shift, but because fixed manufacturing overhead is spread across fewer units.
Under this stress test, the GBP 5 billion dividend becomes uncovered by free cash flow by 2028. The company faces a choice between cutting the dividend, triggering a fifty percent stock price decline and potential index exclusion, or maintaining the payout through debt issuance, effectively returning capital to shareholders while increasing enterprise risk. The credit rating agencies, currently sanguine about BTI’s cash generation, downgrade the debt to junk status, raising refinancing costs and triggering covenants that restrict operational flexibility. The next-generation business, starved of marketing capital, becomes irrelevant. BTI transforms from a transition story into a liquidation story, harvesting cash until the final factory closes.
This scenario is not a prediction, but it is a possibility that the current valuation implies is probable. The six-times-earnings multiple suggests the market is already pricing in some version of this collapse. The question for analysts is whether the probability is accurately calibrated. If there is a thirty percent chance of the bear case and a seventy percent chance of a successful transition to a fifty-percent-next-generation business with stable cash flows, the stock is cheap. If the bear case probability is sixty percent, the stock is fairly valued or expensive. The uncertainty centers on regulatory velocity, whether the FDA moves faster than the combustible decline, and on the ultimate margin structure of next-generation products.
The margin question deserves deeper scrutiny because it challenges the fundamental assumption that next-generation products can ever replace combustibles profitably. Current heated-tobacco and oral pouch margins are obscured by transfer pricing, regional tax variations, and marketing investment phases. But the underlying economics suggest permanent disadvantage. Combustibles benefit from a century of manufacturing optimization and a regulatory structure that taxes competitors symmetrically while allowing incumbents to price as an oligopoly. Next-generation products compete in fragmented markets, apor against disposables, oral against pharmaceutical nicotine replacement therapies, heated tobacco against both. They face higher manufacturing costs, higher regulatory compliance costs per unit, and intense competition from players not bound by the MSA’s cost structure. A Chinese disposable vape manufacturer does not pay nine billion dollars annually to American states; BTI does, whether it sells cigarettes or vapes.
Furthermore, the harm-reduction narrative that BTI needs for multiple expansion contains the seeds of margin destruction. If reduced-risk products succeed in reducing health risks sufficiently to satisfy regulators and public health authorities, they also become candidates for lighter taxation and looser distribution restrictions. This invites precisely the competitive entry that the combustible oligopoly prevents. In a world where nicotine pouches are recognized as ninety-five percent safer than cigarettes, they become candidates for sale in pharmacies, supermarkets, and online channels, ot just behind the tobacco counter. In that world, BTI competes not with Philip Morris and Altria, but with every consumer packaged goods company and pharmaceutical manufacturer capable of manufacturing a simple pouch or device. The regulatory moat dissolves precisely when the health claim is validated.
The Japanese and Scandinavian markets currently support BTI’s margins because those markets maintain strict tobacco-style regulation on next-generation products despite the reduced risk. Japan taxes heated tobacco at rates comparable to cigarettes; Scandinavia restricts oral nicotine sales to licensed tobacco retailers. This regulatory continuity preserves BTI’s distribution advantage. But if the harm-reduction narrative succeeds in its most ambitious form, convincing regulators that these products are genuinely medicinal or benign, the regulatory framework could shift to one of general consumer goods, destroying the barriers to entry that make the tobacco oligopoly profitable.
This is the paradox at the heart of BTI’s strategy: to achieve valuation re-rating, the company must convince investors and regulators that it is transitioning to a less harmful business. But if it succeeds too completely in this argument, it may destroy the regulatory protection that makes the business profitable. A nicotine pouch recognized as harmless becomes a caffeine gum competitor, not a cigarette replacement. The forty-percent operating margin requires the forty-percent to be protected by prohibitionary barriers that do not apply to safe products.
The leadership challenge is to navigate this paradox while managing the cash flow timing. Tadeu Marroco, who took the helm in 2023, inherited a balance sheet shaped by Reynolds and a strategic landscape shaped by Philip Morris’s head start in next-generation products. His decision to maintain the dividend while paying down debt reflects a bet that time is available, hat the combustible business will decline slowly enough to fund the transition without crisis. But the 2023 volume data suggests this bet is increasingly precarious. The ten percent U.S. decline may represent a structural break, the moment when disposable vapes and oral pouches reached sufficient penetration to disrupt the oligopoly’s pricing power irreversibly.
If this is the case, BTI’s capital allocation discipline becomes not a virtue but a trap. The dividend commitment that keeps management honest may prevent the aggressive investment required to catch Philip Morris in next-generation markets. The debt paydown that strengthens the balance sheet may represent opportunity cost, apital that should have been deployed to acquire vape manufacturers or oral pouch startups before the FDA regulatory window closed. The conservative strategy works only if the historical decline rate reasserts itself. If the decline has accelerated, conservatism becomes complacency.
The final tension concerns the nature of nicotine demand itself. BTI’s transition thesis assumes that total nicotine consumption remains stable, hat smokers switch to pouches and heated tobacco, but do not quit nicotine entirely. This assumption underlies the revenue replacement math: if fifty percent of revenue shifts to next-generation at lower margins, but total nicotine volumes grow slightly as harm reduction brings new consumers into the market, the business stabilizes. Altria’s data showing one percent annual growth in cigarette-equivalent volumes supports this view.
But this assumption faces challenges from two directions. Public health advocates argue that reduced-risk products expand the nicotine market by addicting new users who would never have smoked, eenagers using flavored pouches, former smokers returning to nicotine through supposedly safe alternatives. If this expansion narrative prevails, regulators will crack down on marketing, flavors, and accessibility, crushing the growth trajectory. Conversely, if the products genuinely reduce harm and addictiveness, they may enable genuine cessation at higher rates than combustibles, gradually shrinking the total nicotine market even as BTI captures share. Either outcome, regulatory prohibition of next-generation growth or genuine market contraction through successful cessation, destroys the transition economics.
The bear case is therefore more coherent than the bull case. It requires no regulatory miracles, no margin recovery, no assumption that consumers will prefer BTI’s products to competitors’. It simply requires the continuation of current trends: accelerating combustible decline, FDA delay, Philip Morris dominance in oral, and Chinese dominance in vapor. In this world, BTI is not a value stock with a ten percent yield; it is a distressed equity with a deteriorating asset base and a dividend that will be cut. The market’s six-times-earnings valuation may not be a discount to intrinsic value, but a realistic assessment that the terminal value is zero.
The air clears slowly, if at all. BTI stands at the intersection of regulatory protection and regulatory threat, of cash extraction and reinvestment, of oligopoly and fragmentation. The dividend continues, for now, a distribution of capital from a business that may be worth more dead than alive, ore valuable as a cash flow stream to be harvested than as an enterprise to be grown. The question is not whether BTI can pay its shareholders next year. The question is whether it is paying them with the principal of a dying business or the income of a transforming one. The ten percent yield says the market has decided. The management’s task is to prove the market wrong before the volume data makes it right.