Building Systems: The Hidden Operating Cost

The Specification Game
In the basement of a commercial high-rise, the chiller hums for twenty-five years. The building owner will spend roughly ten cents of every lifetime dollar on the machine itself. Seventy to eighty cents will disappear into the meter, fed to the local utility in exchange for the energy required to push heat against entropy. Maintenance will consume the remainder. The equipment, in other words, is almost an accounting footnote: capital expenditure so small relative to operating costs that it barely registers in the net present value calculation. Yet Trane Technologies has built a $30 billion enterprise by dominating this sliver of the cost structure, not by selling cheaper metal, but by ensuring that when engineers specify the system, they specify Trane before anyone else sees the request for proposal.
This is the basis-of-design business. In commercial heating, ventilation, and air conditioning, where Trane earns sixty percent of its revenue, the economic engine runs not on manufacturing scale, but on temporal advantage. Trane’s sales force operates twelve to eighteen months upstream of the competitive bid, embedding itself in the design phase where mechanical engineers model loads, simulate energy consumption, and select equipment catalogs. By the time a general contractor solicits prices, the “or equal” clause in the specification has already been written around Trane’s performance curves. Competitors are welcome to bid, but they are bidding to displace a decision that has already been rationalized on twenty-five-year energy economics rather than unit price.
The mechanism is precise. Trane’s direct sales force, one hundred percent commission-based, technically trained, enjoying top-decile retention, does not wait for RFPs. They cultivate relationships with specifying engineers, building owners, and contractors during the schematic design phase, translating thermal requirements into product selections. Because the sales cycle in applied HVAC mirrors the construction timeline, these relationships compound. An engineer trained on Trane’s equipment specifications in 2014 is likely specifying Trane in 2024. The switching cost is not contractual; it is the friction of redesigning a system around unfamiliar performance data when the project timeline allows no such luxury.
The Commissioned Constraint
The same force that erects Trane’s moat in commercial HVAC becomes a millstone when the company turns to residential markets or light commercial projects. The direct sales model is expensive. One hundred percent commission structures attract talent and align incentives, but they create fixed cost rigidity. A commissioned salesperson earning six figures cannot be deployed profitably to sell residential units where margins are thinner and purchase decisions are made in hours, not months. Trane’s commercial prowess depends on this priesthood of technically literate representatives; its residential growth depends on a two-step distribution model that pushes product through dealers, half of them company-owned, half independent, using a multi-brand portfolio, premium Trane for the high end, Ameristar and Oxbox for the value segment, to prevent dealer defection.
This tension is structural, not incidental. Over-invest in the direct channel for residential, and margins erode in a market where price sensitivity is acute. Under-invest in commercial, and Trane loses the design-phase influence that captures seventy percent of the lifetime value of a building’s climate system. The company has threaded this needle by maintaining strict separation: the commissioned force handles commercial applied HVAC exclusively, while residential relies on distributor relationships. But the constraint remains. Trane cannot scale its commercial sales methodology downmarket without destroying the economics, nor can it fully mechanize the high-touch consultative selling that wins the basis of design in skyscrapers and hospitals.
The fragility lies in the fixed cost nature of this advantage. When construction cycles turn, the sales force does not automatically shrink. Retention rates are high because the compensation structure rewards tenure and technical depth; these are not seasonal hires. In a downturn, Trane carries the overhead while competitors with lighter distribution models flex downward. The company grew at six percent compounded annually over the past decade, roughly two to three times the rate of peers, by expanding share in commercial markets. If that share growth stalls, if engineers begin to view Trane’s specifications as proprietary rather than optimal, the fixed cost structure becomes a liability of the first order.
The Hidden Standard
Buried in this commercial engine is an underappreciated asset that appears nowhere significant on the income statement yet shapes billions in capital allocation decisions. TRACE, Trane’s load and energy simulation software, is the industry standard for HVAC engineers modeling building thermal behavior. It is taught in universities, expected by building owners, and used to justify energy efficiency certifications. Crucially, it arrives pre-populated with Trane’s product catalog. Competitors’ equipment can be manually entered, but the friction is real: different performance curves, unfamiliar nomenclature, the risk of error when deviating from the default library.
TRACE functions as a hidden tariff on specification. It appears neutral, a technical tool, a rounding error in Trane’s revenue, but it biases the design phase toward Trane equipment before any competitive analysis occurs. The software creates network effects: the more engineers trained on TRACE, the more buildings specified through TRACE, the more essential the software becomes to professional practice. Competitors face a brutal substitution problem. They must either build equivalent simulation platforms, a capital-intensive undertaking with uncertain adoption curves, or accept that their equipment will consistently be harder to specify, relegated to “or equal” substitutions that require engineering review and owner approval.
The durability of this advantage depends on opacity. As long as TRACE is viewed as a technical utility rather than a competitive weapon, it avoids regulatory scrutiny. Should antitrust authorities or industry consortia begin to view pre-populated catalogs as anti-competitive, or should open-source simulation tools gain traction among engineers, Trane’s hidden moat becomes a target. The software is a moat precisely because it is invisible to the end user; if it becomes visible as a restraint on competition, the advantage evaporates. For now, it remains the unseen architecture of commercial HVAC specification, a twenty-first-century equivalent of the proprietary engineering manuals that once locked industrial customers into equipment ecosystems.
The Service Compounding
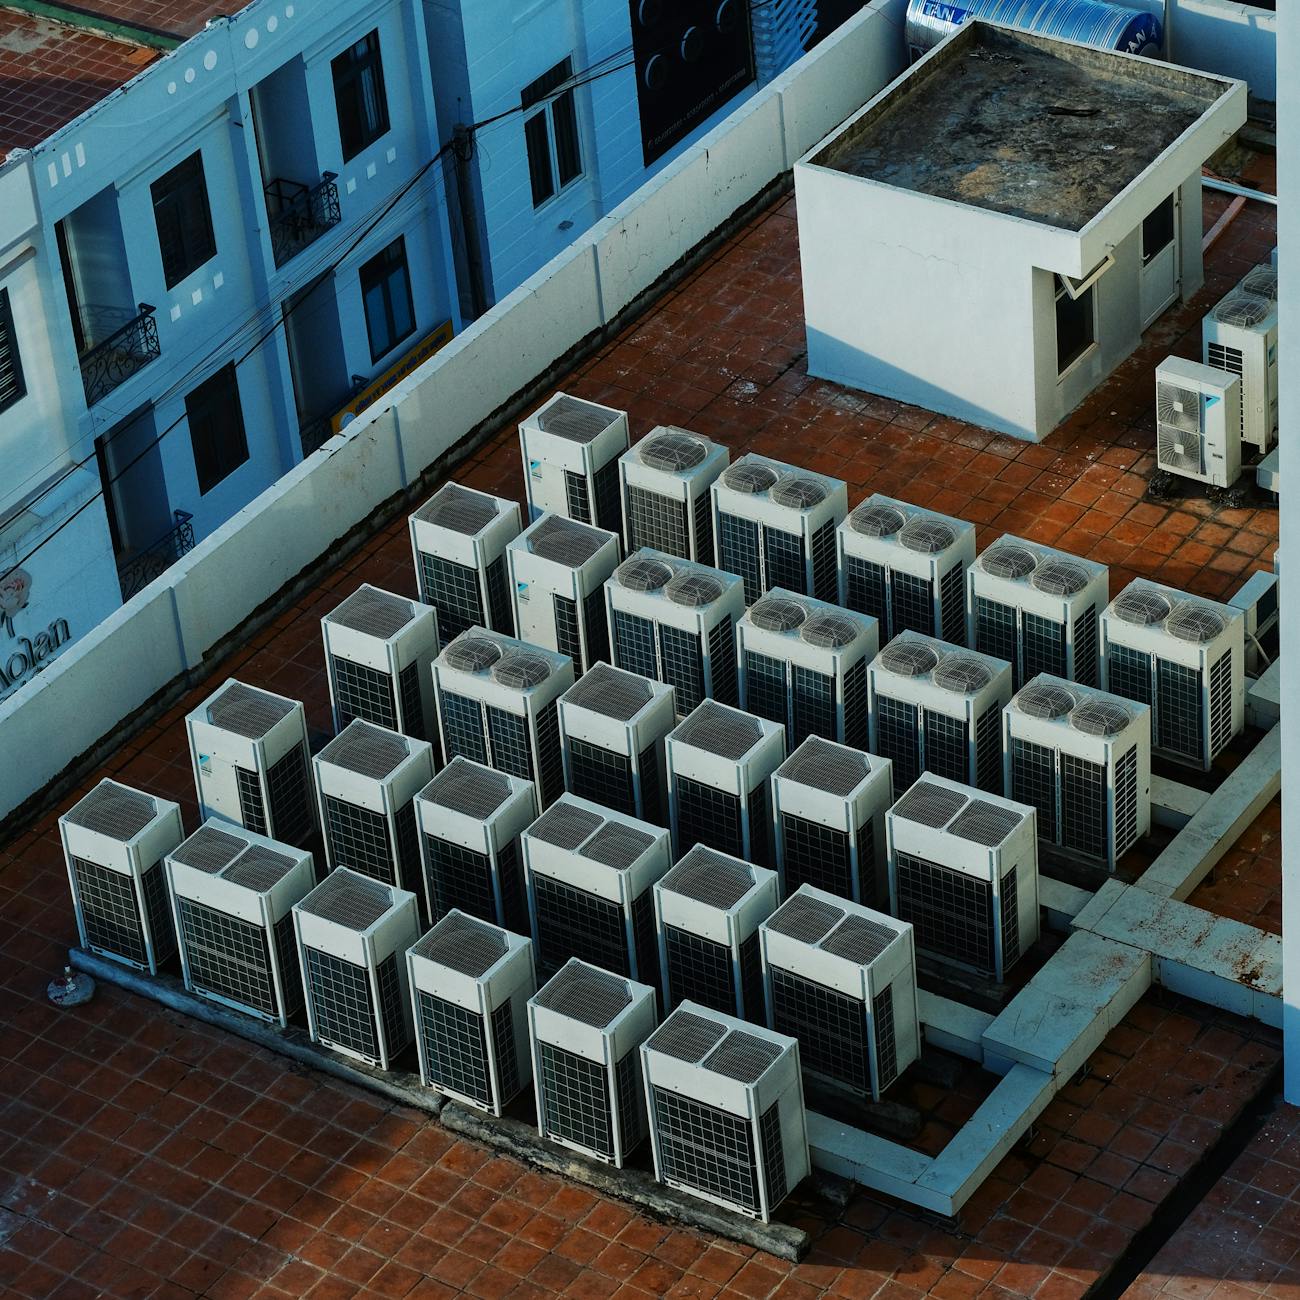
Once Trane equipment is installed, the economic logic shifts from specification to capture. Aftermarket service now represents thirty-two percent of company revenue, up one thousand basis points since the global financial crisis, growing at high single digits with margins that accreted disproportionately to the bottom line. The thesis is straightforward: equipment generates data, data enables predictive maintenance, and predictive maintenance locks out fragmented independent service providers who lack visibility into machine performance.
Trane has invested heavily in digital connectivity, sensors, monitoring platforms, analytics, to ensure that when a chiller begins to vibrate outside tolerances or a refrigerant loop approaches inefficiency, Trane knows before the building engineer does. This visibility allows proactive service scheduling, parts replacement, and system optimization that independents cannot match. The economic capture is elegant: Trane sells the equipment on efficiency, then captures the maintenance value through data monopolies, extending the customer relationship across the twenty-five-year lifecycle where the real money, seventy to eighty percent of lifetime spend, flows through energy and maintenance rather than capital equipment.
The fragility here is competitive and technological. Trane’s aftermarket growth assumes that competitors will not build equivalent digital platforms, and that independent service providers will remain fragmented and data-blind. But the infrastructure Trane builds, IoT sensors, cloud monitoring, predictive algorithms, can be replicated. Carrier, Johnson Controls, and emerging building automation players can invest in similar visibility. Moreover, Trane’s installed base is, in some sense, a public good for competitors. A competitor can free-ride on Trane’s physical presence in buildings, offering service on Trane equipment using aftermarket parts and reverse-engineered diagnostics. If aftermarket service growth slows from high single digits to low single digits, the margin expansion narrative collapses. The business model assumes Trane can outrun the independents indefinitely, capturing an ever-larger share of the service revenue pool while competitors remain disorganized. This is a bet on execution speed and technological investment that must be remade quarterly.
The Regulatory Wager
Trane’s growth acceleration, six percent annually against an industry growing at half that rate, depends on a tailwind that is political, not mechanical. Regulatory pressure on building efficiency, refrigerant phase-outs, and the Inflation Reduction Act’s incentives for electrification and decarbonization have compressed replacement cycles and shifted mix toward higher-efficiency, higher-margin equipment. Trane has pledged to reduce one gigaton of carbon emissions from its customer base by 2030, a commitment that aligns the company’s marketing with the policy zeitgeist while accelerating the obsolescence of legacy installed base.
This is a wager on permanence. The economic payback on high-efficiency HVAC runs three to five years on a twenty-five-year system: calculation that assumes stable energy prices, continued carbon pricing or regulatory pressure, and available incentives. Should political priorities shift, should IRA incentives expire without renewal, or should a recession prompt building owners to defer capital replacement and accept higher operating costs, Trane’s secular growth narrative reverts to cyclical behavior. The company is currently insulated by an abnormal backlog, most of 2024 equipment was sold by early 2023, against a normal six-month horizon, but backlogs are temporary reservoirs, not permanent streams.
When the current construction cycle normalizes, when supply chains clear and lead times contract, Trane will face the underlying volatility of the commercial real estate market. The direct sales force that drives specification becomes a fixed cost anchor in a downturn. The aftermarket growth that masks cyclicality in equipment sales depends on continued building occupancy and capital availability for efficiency upgrades. If regulatory momentum stalls, if the decarbonization imperative fades, Trane’s premium valuation assumes a permanence that the historical record of building efficiency standards does not guarantee. The business has bet that policy will continue to accelerate replacement demand; it is a bet on the political durability of climate regulation.
The Backlog Mirage
The current visibility into Trane’s revenue is historically anomalous. Most of 2024’s HVAC equipment sits in backlog, booked and scheduled, a consequence of supply chain constraints and construction delays that extended lead times to twelve or eighteen months. In normal conditions, backlog hovers around six months, nough to smooth production scheduling, insufficient to mask underlying demand signals. Today’s backlog creates an illusion of stability. It allows Trane to plan production with certainty, to lock in component pricing, to manage the commissioned sales force without the quarterly anxiety of empty pipelines.
But backlogs clear. When supply normalizes, when construction projects that were delayed by material shortages finally come online, the order book will shrink to historical levels. At that point, Trane’s true cyclical exposure will become visible. The company grew through the 2015-2016 construction slowdown at low single digits; it is not immune to macroeconomic headwinds. The risk is that investors and management have begun to treat the current visibility as structural rather than temporal. When the abnormality ends, Trane will face the classic industrial dilemma: fixed sales costs against variable demand.
The clearing of backlog will also test the aftermarket assumptions. Service contracts are easier to sell when equipment is being installed; the replacement cycle drives the attachment rate of monitoring and maintenance agreements. If equipment sales fall when backlog normalizes, the service growth engine must accelerate to compensate, requiring Trane to capture share from independents at an even faster rate. The current backlog is a buffer that hides the business model’s sensitivity to construction cycles. When it disappears, the tension between the fixed-cost commercial sales force and the variable revenue environment will tighten.
The Portfolio Defense
In residential HVAC, where Trane holds roughly a high-teens share of a market eighty-five percent controlled by four players, Carrier, Goodman, Trane, and Lennox, competition operates through dealer relationships rather than direct sales. Trane deploys a multi-brand strategy: the premium Trane badge for homeowners seeking reliability and status, the Ameristar and Oxbox labels for price-sensitive replacements. This portfolio prevents dealer defection. A contractor carrying Trane and Ameristar can serve any customer segment without losing the sale to a competitor; if Trane offered only premium products, dealers would switch to Carrier or Goodman for value-line coverage.

The durability of this advantage depends on manufacturing execution and regulatory navigation. Dealer relationships are sticky but not unbreakable. In 2018, a tornado damaged Lennox’s manufacturing facility, forcing production prioritization that left dealers without inventory for months. Competitors captured that share; Lennox never fully recovered its prior market position. Trane’s share gains over the past decade, growing two to three times faster than the industry, assume flawless execution in manufacturing, logistics, and refrigerant transition management. One product recall, one supply chain disruption, one failure to meet a regulatory deadline for new refrigerant standards, and the sticky dealer relationships become unstuck. In a consolidated oligopoly, share is hard-won and easily lost.
The Execution Premium
Driving Trane’s outperformance is an organizational structure that treats product development as a profit-center rather than a cost-center. Product growth teams are accountable for both share capture and margin expansion within specific customer segments, ommercial offices, healthcare facilities, residential retrofits. This is not marketing segmentation; it is economic accountability. These teams own the P&L for their verticals, forcing trade-offs between volume and price, between specification investment and profitability, that might otherwise be lost in functional silos.
This cultural variable, execution discipline embedded in organizational design, has allowed Trane to outgrow peers without sacrificing returns. But it is a fragile capability. The product growth team model depends on talent retention, on data infrastructure that allows granular segment reporting, and on a corporate tolerance for internal competition that can erode as the company scales. If execution falters, f a product launch misses a refrigerant transition window, if a quality issue forces a recall, if the commissioned sales force experiences unexpected turnover: he share gains reverse quickly. Trane’s historical growth is a sequence of correct decisions made under uncertainty; the organization that made them is the asset, but organizations are permeable. In a business where specification happens eighteen months before revenue recognition, execution errors today do not appear in financials until tomorrow’s gaps.
The economics of Trane Technologies rest on this sequence: software shapes specification, sales force locks relationships, equipment creates the installed base, data captures the aftermarket, and regulation accelerates the replacement cycle. Each link reinforces the next, creating a compounding machine that has delivered superior returns. Yet the model depends on the assumption that the abnormal backlog will not reveal cyclicality, that regulatory tailwinds will not reverse, that TRACE will remain the unchallenged standard, and that the commissioned priesthood will retain its influence without becoming a fixed-cost burden. Trane does not sell air conditioners; it sells the engineering decision to buy Trane air conditioners, then collects rent on that decision for twenty-five years. It is a brilliant mechanism, provided the engineering profession continues to specify, and the building owners continue to build.
The Cold Chain Divergence
While the commercial HVAC business operates on the logic of specification and twenty-five-year energy economics, Trane’s transport refrigeration division, Thermo King, acquired in 1997 and representing roughly twenty percent of revenue, follows a different rhythm. Here, the equipment moves. Refrigerated trailers, shipping containers, and rail cars do not sit beneath buildings accumulating service contracts; they traverse highways and oceans, subject to vibration, weather, and the irregular maintenance schedules of trucking fleets. The economic engine is not basis-of-design software but uptime guarantees. When a refrigerated trailer fails en route from Nogales to Chicago, the cargo, often worth multiples of the refrigeration unit itself, spoils within hours. The customer buys reliability under duress, not efficiency over decades.
This divergence creates a portfolio effect that stabilizes Trane’s aggregate revenue but complicates the organization’s strategic coherence. Thermo King’s customers are fleet operators, third-party logistics providers, and shipping lines, not specifying engineers. The sales cycle is transactional and replacement-driven, with equipment lifecycles of seven to twelve years rather than twenty-five. The aftermarket opportunity exists, breakdowns are expensive, and preventive maintenance is essential, but the digital connectivity that enables Trane’s HVAC service expansion is harder to implement in mobile assets subject to cellular dead zones and harsh operating environments.
Moreover, the transport refrigeration market faces electrification pressure that differs qualitatively from building HVAC. As logistics fleets transition to electric tractors, the auxiliary power units that drive refrigeration must evolve from diesel-powered to electric or hybrid systems. This requires not merely product adaptation but infrastructure coordination, harging protocols, battery management, integration with vehicle power systems. Trane has invested in electric trailer units, but the competitive set includes not just traditional HVAC competitors but specialized transport refrigeration providers and emerging electric vehicle component suppliers. The moat here is narrower, built on brand reputation for reliability rather than specification lock-in. If Trane’s HVAC business depends on the inertia of engineers trained on TRACE, its transport business depends on the risk aversion of fleet managers who remember which brand failed during the cherry harvest of 2019. The memory is long, but the switching cost is low.
When Software Becomes a Target
The durability of TRACE as a competitive weapon depends on its continued invisibility to antitrust authorities and its technical superiority to open-source alternatives. For two decades, the software has occupied a gray zone: it is marketed as a neutral engineering tool, yet its architecture, pre-populated with Trane’s product library, formatted around Trane’s performance nomenclature, creates friction for competitors that approaches the definitional threshold of tying arrangements. If engineers using TRACE must manually enter competitor data while Trane data loads automatically, the effective cost of specifying non-Trane equipment increases.
This advantage persists because HVAC engineering remains a fragmented profession, and because building owners have not demanded interoperability. But pressure is building. Large real estate investment trusts, managing portfolios of Class A office towers, increasingly mandate that new construction specify equipment from multiple qualified vendors to ensure competitive bidding and supply chain resilience. If these owners begin to require that simulation software present neutral product comparisons, or worse, if they mandate the use of open-source building energy modeling tools like EnergyPlus or emerging interoperable platforms, TRACE’s pre-population advantage becomes a liability. Trane would face a choice: open the software to competitor products, erasing the specification bias, or risk exclusion from projects with strict vendor-neutrality requirements.

The regulatory risk extends to the European Union and other jurisdictions with aggressive digital competition policies. If TRACE is deemed an essential facility or a de facto industry standard, regulators could mandate data portability and interoperability requirements similar to those imposed on financial messaging systems or mobile operating systems. For Trane, this would represent an expropriation of a valuable intangible asset without compensation. The software costs little to maintain relative to its strategic value; forced opening would convert a moat into a public utility. The company’s defense, that TRACE merely offers convenience, not constraint, grows thinner as the software’s market share approaches monopoly levels in North American commercial HVAC specification. At some point, ubiquity becomes vulnerability.
The Service Wars
The aftermarket service growth that has transformed Trane’s margin profile, from twenty-two percent of revenue before the financial crisis to thirty-two percent today, assumes a specific competitive dynamic: that Trane can outrun not just independent service contractors but also the service arms of its major competitors. Currently, the independent service market remains fragmented, populated by regional contractors with limited digital capabilities, unable to offer predictive maintenance or system optimization. Trane’s IoT infrastructure, sensors on chillers, connected rooftops, cloud-based analytics, allows the company to identify degradation before failure and intervene before the customer calls a competitor.
But this advantage is infrastructural, not proprietary. Johnson Controls, Carrier, and Honeywell possess equivalent or superior digital capabilities in building automation and controls. If these competitors choose to invest aggressively in service platform integration, connecting their equipment directly to their own service networks, bypassing the independent channel, Trane’s growth in aftermarket capture becomes a zero-sum battle for market share rather than a secular expansion. The risk is particularly acute in the chiller market, where Trane holds strong positions but faces sophisticated competitors with deeper controls expertise.
Consider the mechanics of a service capture. A building engineer notices reduced cooling capacity and calls a local contractor. If the chiller is connected to Trane’s monitoring platform, Trane’s service center detects the anomaly simultaneously, dispatches a technician with the correct parts, and intercepts the call. The independent contractor arrives to find Trane already on site. This requires continuous investment in monitoring infrastructure, call centers, and technician training. If Carrier deploys similar predictive capabilities across its installed base, the market bifurcates: buildings with integrated manufacturer service contracts versus those served by independents. Trane’s growth assumes it can capture the former faster than competitors; if the competitive set consolidates its digital service offerings, Trane’s thirty-two percent service mix may represent a ceiling rather than a waypoint.
The free-rider problem compounds this tension. Competitors can service Trane equipment using aftermarket parts, reverse-engineered control sequences, and third-party refrigerants. While Trane’s digital connectivity creates switching costs for the building owner, who values the predictive capability, the physical equipment is serviceable by any competent technician. Trane must maintain a price and service quality differential sufficient to justify proprietary contracts against lower-cost independents. If the differential narrows, if Trane’s service prices rise to cover digital infrastructure costs while independents offer adequate reactive maintenance at lower rates, the aftermarket growth story stalls.
The Tornado and the Share
The fragility of residential market share reveals itself not in the aggregate statistics but in specific moments of operational failure. In July 2018, an EF3 tornado struck Lennox’s manufacturing facility in Marshalltown, Iowa, halting production of residential air conditioning units for months. The facility produced roughly one-third of Lennox’s North American volume. Faced with scarce inventory, Lennox prioritized premium products and direct customers, leaving value-line dealers without equipment. Contractors who had built businesses around Lennox’s brand suddenly faced empty warehouses during the peak summer season.
The competitive response was immediate and brutal. Carrier, Goodman, and Trane diverted inventory to Lennox’s orphaned dealers, offering temporary distribution relationships and aggressive financing. By the time Marshalltown resumed full production, dozens of Lennox dealers had signed exclusive or primary agreements with competitors. Lennox’s market share, which had hovered around eighteen percent, dropped to the mid-teens and never fully recovered. The company spent years rebuilding dealer relationships, but the stickiness of HVAC distribution cuts both ways: once a contractor learns a new product line, sources parts from a new supplier, and trains technicians on new diagnostics, the cost of switching back becomes prohibitive.
This episode illuminates the execution risk embedded in Trane’s residential strategy. Trane has gained share over the past decade through operational reliability, onsistent delivery across its two-step distribution network, balanced inventory between premium and value lines, and avoidance of the manufacturing stumbles that plagued competitors. But the Lennox tornado demonstrates that share is stored in dealer relationships that can be vaporized by a single supply chain disruption. Trane’s multi-brand portfolio (Trane, Ameristar, Oxbox) provides some buffer, if one brand faces shortage, dealers can substitute another, but the underlying manufacturing concentration remains. A fire at a critical compressor supplier, a refrigerant transition misstep, or a quality defect requiring mass recall could trigger the same dealer defection that benefited Trane in 2018.
The residential market’s consolidation, four players controlling eighty-five to ninety percent of North American volume, creates an oligopolistic stability that masks individual vulnerability. Because the market is sticky, share shifts happen infrequently but violently. Trane’s growth has been steady, not episodic, suggesting superior execution. But the steady state assumes continued perfection. In a business where contractors install the equipment they can obtain, not necessarily the equipment they prefer, manufacturing reliability is the primary competitive variable. Trane has won by not losing; it must continue to not lose for decades to justify current valuations.
The Refrigerant Transition
Beneath the macroeconomic tailwinds of decarbonization and efficiency regulation lies a specific technical transition that will test Trane’s product development and regulatory navigation. The phasedown of hydrofluorocarbon (HFC) refrigerants, particularly R-410A, the standard for residential and light commercial systems, requires a shift to lower global warming potential (GWP) alternatives such as R-32 or R-454B. This transition is not merely a product line adjustment; it requires redesign of compressors, heat exchangers, and control systems to handle the thermodynamic properties and safety characteristics (flammability, toxicity) of new refrigerants.
The regulatory timeline creates a competitive window. The Environmental Protection Agency’s phasedown schedule, aligned with the American Innovation and Manufacturing (AIM) Act, mandates production and import limits on high-GWP refrigerants, with significant reductions beginning in 2024 and accelerating through 2036. Equipment manufacturers must certify new products using alternative refrigerants while maintaining service capabilities for the installed base of R-410A systems that will require maintenance for another fifteen years.
Trane’s advantage lies in its applied commercial expertise, large chillers have operated with low-GWP refrigerants for years, but its residential and light commercial portfolios face retooling challenges. If Trane’s product growth teams miss the certification deadlines, or if their R-32 systems underperform in field conditions relative to Carrier or Lennox offerings, the share gains of the past decade reverse. The transition also creates inventory risk: manufacturers must manage the phase-out of R-410A equipment while ensuring adequate supply of new refrigerant systems. Misjudge the adoption curve, and Trane faces either excess inventory of obsolete equipment or shortages of compliant products during peak season.
The IRA incentives further complicate this transition. Tax credits for high-efficiency heat pumps require not only energy performance but also refrigerant GWP below specific thresholds. Trane’s ability to capture these incentives depends on product availability and certification precision. If competitors secure EPA safety certifications or ENERGY STAR qualifications earlier, they capture the subsidy-driven demand surge. The regulatory tailwind becomes a headwind for those caught behind the transition curve.
Capital After the Trust
The March 2020 separation from Ingersoll Rand via Reverse Morris Trust, a transaction that allowed tax-efficient distribution of assets while merging Ingersoll Rand’s industrial businesses with Gardner Denver, left Trane Technologies as a pure-play climate control company with a specific capital structure and strategic mandate. The transaction required Trane to assume debt and establish an independent credit profile while maintaining investment-grade ratings to support the equipment financing essential to its commercial HVAC sales.
This corporate provenance matters for capital allocation. Unlike competitors with broader industrial conglomerate parents, Carrier remains tied to refrigeration and fire security, Johnson Controls maintains building controls and batteries, Trane is singularly exposed to thermal management. There is no unrelated business to subsidize HVAC downturns, no cross-selling into adjacent markets to smooth revenue. The pure-play structure demands disciplined capital deployment: either reinvestment in the core specification and service advantages, or return to shareholders via dividends and buybacks.
Since the spin, Trane has prioritized the former, investing in digital infrastructure for aftermarket capture and expanding the commissioned sales force. But the flexibility is finite. If the aftermarket growth stalls or if commercial construction enters a prolonged downturn, Trane cannot divest a peripheral division to maintain returns. The company must manage through the cycle with the same assets that drove the upturn. The Reverse Morris Trust created a focused competitor; it also created a concentrated bet.
The debt structure assumed in the separation requires consistent free cash flow generation to service obligations while funding the digital and sales force investments necessary for growth. If the abnormally high backlog masks underlying demand weakness, if the aftermarket growth slows, or if refrigerant transition costs exceed estimates, the capital allocation tension tightens. Trane must choose between maintaining the commissioned sales force, the fixed cost moat, and preserving margins, between funding TRACE development and returning capital, between acquiring independent service providers to accelerate aftermarket consolidation or allowing organic growth.
These choices are the substance of strategy. Trane has executed cleanly since the spin, growing share and expanding margins in a competitive oligopoly. But the structure of the separation, its finality, its concentration, means that execution errors compound without diversification. The company that emerges from the next construction cycle will look much like the one that entered it, for better or worse. There is no strategic pivot available, no hidden division to monetize. Trane Technologies is the commercial HVAC specification game, the residential dealer network, the transport refrigeration reliability, and the aftermarket service capture. The coherence is the risk.