Coupang: When Founder Rejected the Groupon Path

The Pivot Away from the Platform Mirage
In December 2014, Bom Kim was days away from personal liquidity. Coupang had filed to go public on a model that looked, to outside observers, like South Korea’s answer to Groupon, lash sales, third-party merchants, and a race to the bottom on price that would eventually collapse under its own weight. Kim pulled the offering. He told his board they would not become a coupon company that traded tomorrow’s margins for today’s growth. Instead, Coupang would build warehouses, hire thousands of full-time couriers, and stock inventory. The decision required abandoning tens of millions in personal wealth, maybe more, and betting the company on capital intensity in a market that was sprinting toward asset-light platforms.
That choice defined everything that followed. Coupang is not a marketplace connecting buyers and sellers; it is a retailer that happens to own the railroad, the stations, and the conductors. The economic engine runs on the conversion of South Korea’s geographic density into logistics velocity, captured through a membership subscription that bundles delivery, streaming, and food discounts. The model generates trust through first-party control of inventory and fulfillment, creating behavioral switching costs that platform competitors cannot replicate. Yet this engine is also a cage. The density that makes seven-hour delivery profitable is unique to the Korean peninsula. The market is nearly exhausted, twenty-one million active buyers in a country of twenty-two million households, and the capital required to reproduce this infrastructure elsewhere is prohibitive. Coupang’s durability rests on the fragile assumption that founder conviction can indefinitely defer the margin compression inherent in retail saturation, and that the cultural conditions enabling its trust-based moat will persist as the company matures into a public institution.
Density Is the Entire Economic Engine
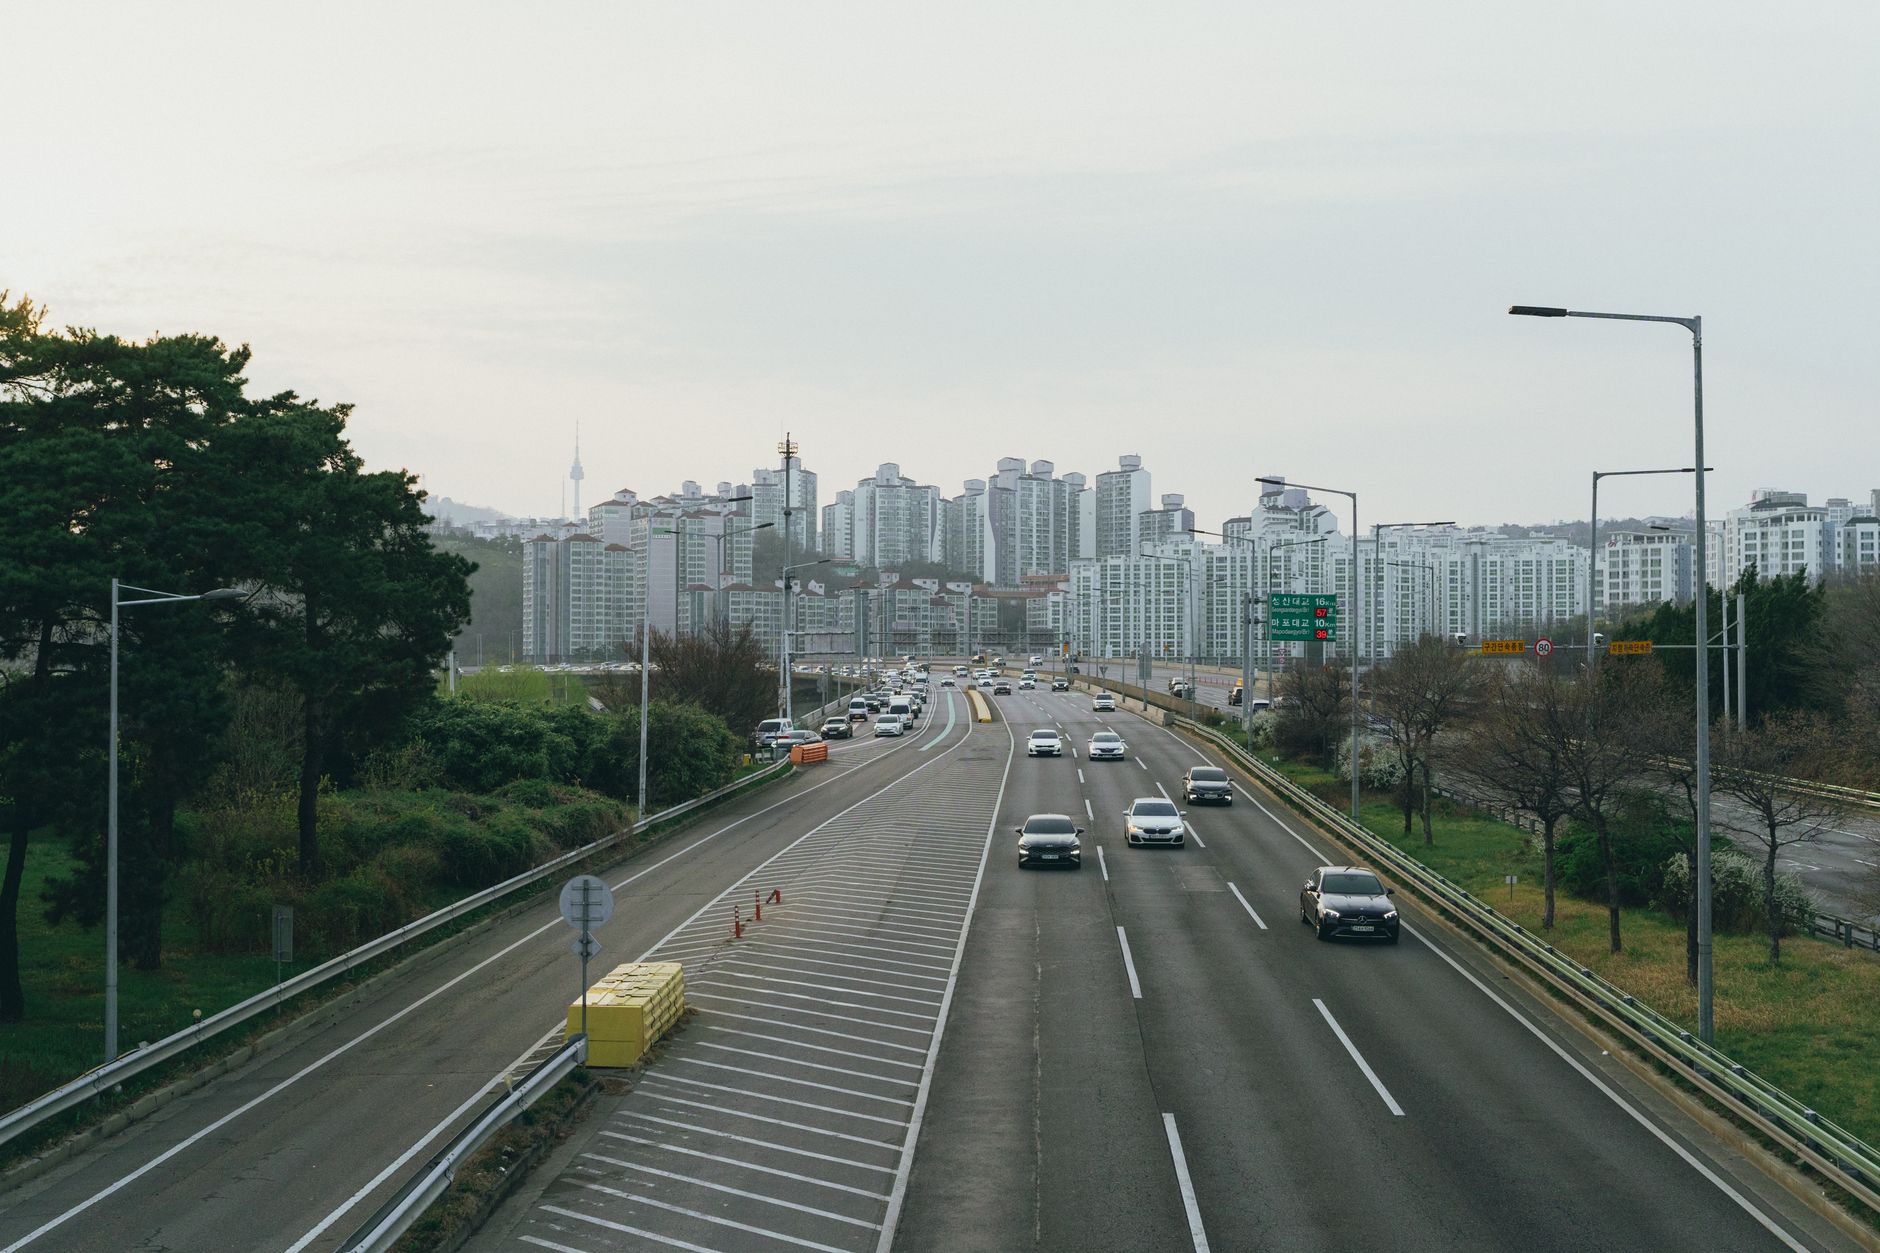
South Korea is not hospitable to sprawl. Seventy percent of the peninsula is mountainous, forcing the population into vertical concentration. Seventy percent of Koreans live in apartment complexes, many of them high-rises. This geography is the invisible input in Coupang’s financial statements. When a Rocket Man, Coupang’s term for its employed delivery force, enters a complex in Gangnam or Busan, he does not carry one package. He carries twenty. A single courier can serve an entire building in a single stop, dropping bags at doorsteps, leaving perishables in insulated cooler bags that sit unattended in hallways or outside doors, trusted to remain untouched.
This density collapses the cost of last-mile delivery. In the United States or Europe, where population spreads horizontally across suburbs and exurbs, same-day delivery requires sprawling networks of gig drivers covering vast distances for single items. The marginal cost per delivery stays high. In Seoul’s vertical corridors, the marginal cost approaches zero as volume rises. By 2018, ninety-nine percent of Coupang’s deliveries arrived within twenty-four hours; by 2019, the company offered seven-hour delivery on over five million items. Competitors like NAVER or SSG.com rely on third-party logistics providers. They cannot guarantee timing because they do not control the trucks. They cannot leave packages unattended because they do not control the trust relationship. The structural advantage is not merely speed; it is the unit economics of density that only an owned, integrated logistics network can exploit.
The capital requirements to build this were immense. Coupang burned through $1.5 billion in cash in 2021 alone, constructing warehouses, leasing aircraft, and hiring Rocket Men as full employees with benefits. The company reached profitability only in 2023. This is not a software margin business. It is a retail infrastructure business that happens to exist in a geography where infrastructure costs per customer are lower than anywhere else on earth. The constraint is absolute: without Korean urban density, the model does not function.
When the Subscription Hides the Margin
Coupang captures value through Rocket WOW, a membership program priced between seven and seven dollars and fifty cents monthly. Fourteen million households subscribe: oughly two-thirds of Coupang’s active buyer base. The membership bundles free delivery, access to Coupang Play (a streaming service), and discounts on Coupang Eats (food delivery). The data is stark: customers who use multiple services spend three times what they did in 2018, averaging $1,100 per year, and they churn at significantly lower rates.
This bundling creates a recurring revenue stream that insulates Coupang from the transactional volatility of pure retail. It also creates a strategic opacity. It is impossible to determine, from outside the company, which services within the bundle are profitable and which are loss-leaders subsidizing the others. Coupang Play streams content at significant cost. Coupang Eats competes in a food delivery market notorious for negative unit economics. If these services exist primarily to increase the perceived value of the shipping membership, they may be bleeding cash that the retail operation subsidizes. If unbundled, the value proposition weakens, and churn risk rises. If kept bundled, management loses the ability to optimize individual service lines, masking deteriorating economics behind aggregate growth figures.
The membership model shifts the competitive frame. NAVER and other marketplace competitors offer access to merchants; Coupang offers a lifestyle utility. The switching costs are behavioral. A subscriber who watches Coupang Play, orders groceries for dawn delivery, and uses Eats discounts is not merely a customer; they have outsourced their domestic logistics to a single provider. The danger is that this bundling obscures the true cost of retention. If the streaming content or food subsidies become too expensive, or if competitors unbundle more effectively, the entire edifice of loyalty may rest on economic foundations that cannot bear the weight.
The Cultural Infrastructure of Trust
Analysts often cite speed as Coupang’s moat. This misses the mechanism. Speed is a byproduct of density and infrastructure; the actual moat is trust, constructed through specific cultural and regulatory conditions that competitors cannot import.
Coupang operates a first-party inventory model. When a customer orders a television or a refrigerator, Coupang owns the unit in its warehouse, Coupang’s employees pack it, and Coupang’s couriers deliver it. If the customer returns it, they leave it outside their door in the original packaging, or in some cases unpackaged, for pickup. No post office visit. No merchant negotiation. No variability in policy. This consistency eliminates purchase hesitation for high-ticket items. Consumers explicitly state willingness to pay premium prices for Coupang’s reliability on expensive goods, even while they price-shop for cheaper items on NAVER.

This return policy relies on a specific cultural condition: South Korea’s low theft rate. Cooler bags containing fresh meat and produce sit in apartment corridors for hours without being stolen. This enables the operational efficiency of “drop and go” delivery, which in turn makes the seven-hour promise economically viable. Attempt this in São Paulo or Chicago, and the shrinkage would destroy margins. Additionally, South Korea’s Fair Trade Act prohibits manufacturers from displaying minimum advertised prices on electronics in physical retail, creating an artificial price floor in brick-and-mortar stores that gives e-commerce a structural advantage. Coupang did not create these conditions; it exploits them.
NAVER, Coupang’s largest competitor, operates a marketplace model connecting buyers with third-party merchants. Inherently, this introduces variability in packaging, delivery timing, and return policy. A marketplace cannot guarantee trust because it does not control the inventory. Coupang’s reliability is structural, not contractual. The underappreciated advantage is not the technology of the app or the speed of the vans, but the alignment of operational choices with cultural specificity that creates behavioral lock-in.
The Apparel Problem and the Saturation Ceiling
The density advantage has a corollary: there is nowhere left to grow. Coupang has achieved near-total penetration of the Korean market, with twenty-one million active buyers in a nation of twenty-two million households. Future growth must come from increasing spend per customer or conquering categories where Coupang remains weak.
Spend per customer has tripled since 2018, but this trajectory faces limits. The weak categories are apparel, cosmetics, and beauty, egments dominated by department stores like LOTTE and Shinsegae, or by specialized e-commerce players. In these areas, Coupang claims price parity with alternatives on roughly sixty percent of items, but loses price-sensitive consumers to NAVER and third-party merchants who avoid commission structures. The tension is acute. If Coupang cuts prices to compete on cosmetics and mid-priced fashion, margins compress further on an already capital-intensive model. If it maintains pricing, it cedes volume in the categories that represent the last frontier of wallet expansion.
To solve this, Coupang acquired Farfetch, the luxury fashion marketplace, for $500 million. Farfetch carried $4 billion in gross merchandise value and gave Coupang immediate access to high-end apparel relationships. The acquisition represents a fork in the road. Organic build in fashion requires years of brand relationships and trend forecasting; acquisition brings integration risk and dilutes returns on capital. Neither path guarantees success against specialized competitors who understand the aesthetic and cyclical nature of fashion retail that Coupang’s logistics-centric culture may not.
The saturation creates a valuation trap. With no new households to acquire, Coupang must become a story about increasing share of wallet and improving margins. But the weak categories are precisely the low-margin, high-variability segments where logistics excellence provides less advantage. The model works best on commodities and electronics; it works worst on taste-driven discretionary items. As Coupang pushes deeper into apparel, the risk is that it trades its reliability premium for inventory obsolescence and return rates that erode the very unit economics that made the business viable.
Geography Is Destiny
International expansion is the obvious escape from saturation, and it is structurally impossible. Coupang has tested Taiwan and explored the United States. Both efforts founder on the absence of Korean density. Taiwan’s urban form is different; its regulatory environment varies; its e-commerce culture does not prioritize the same delivery speed promises. The United States presents the geography problem in extremis. The suburban sprawl that defines American retail makes seven-hour delivery economically irrational without charging fees that consumers refuse to pay.
More fundamentally, the cultural infrastructure does not transfer. The low-theft environment that enables doorstep returns does not exist in most Western markets. The labor laws that allow for the Rocket Men employment model, full-time benefited couriers rather than gig workers, vary by jurisdiction. The capital required to build warehouse networks in less dense markets runs into the billions, with per-delivery costs two to three times higher than in Seoul. Without the density, the unit economics collapse. Without the cultural trust, the operational shortcuts disappear.
Coupang is therefore trapped in the geography that created it. The model is non-exportable not because of brand familiarity or marketing challenges, but because the physics and sociology that make it profitable are Korean specific. This is the defining structural constraint: the business is a perfect machine designed for a single market that it has already saturated. Every dollar spent on international expansion is a dollar spent attempting to violate the laws of distance and culture that make the domestic model work.
The High Cost of Founder Conviction
Capital intensity requires capital allocation discipline, and Coupang’s governance structure concentrates that discipline in one person. Bom Kim’s decision to pull the 2014 IPO, abandon the Groupon model, and pursue logistics ownership required a founder’s willingness to defer liquidity and ignore short-term metrics. That same conviction enabled the company to burn $1.5 billion in cash in a single year while building infrastructure that competitors would not or could not replicate.
As a public company, Coupang now faces the institutional pressure that comes with quarterly reporting. Shareholders demand profitability trajectories, margin expansion, and returns on capital. The founder’s control enables resistance to these pressures, Kim can prioritize long-term customer lifetime value over immediate EBIT, but it also creates governance risk. Founder-led decisions can be visionary or merely idiosyncratic. The Farfetch acquisition, the continued subsidy of Coupang Play, and the resistance to unbundling the membership are all decisions that require a specific theory of value creation that only the founder fully holds.
The economic variable here is time preference. A typical retail CEO, facing a saturated domestic market and capital-prohibitive international expansion, might optimize for cash flow, raise prices, and harvest the installed base. Kim appears determined to continue deploying capital into category expansion and service bundling, betting that the compounding effects of membership density will eventually outrun the costs of saturation. This is a bet on the durability of the trust moat and the stickiness of the bundle. If the founder’s conviction wavers, or if governance shifts toward institutional control, the strategic drift would likely manifest as margin compression, utting prices to grow share in apparel, reducing investment in Rocket Men reliability, or unbundling services to show profitability in individual lines.

Coupang stands at the intersection of these tensions: a logistics machine perfected for a geography that can no longer provide growth, a membership bundle that obscures its own economics, and a founder whose discipline built the moat but whose continued control is necessary to maintain it. The business is not a platform play or a technology story. It is a physical infrastructure company that captured a fleeting alignment of urban density and cultural trust, converting them into a consumer habit that is difficult to break but impossible to replicate. Whether that habit can sustain an ever-larger enterprise in a market without new customers remains the unanswered question, and the answer will depend on how long the founder’s hand remains steady on the capital allocation lever.
The Farfetch Bargain and the Apparel Paradox
The acquisition of Farfetch reveals the precise contours of Coupang’s category weakness. At $500 million, the price represented a rescue bid for a luxury marketplace that had burned through billions in venture capital attempting to bridge the gap between boutique fashion houses and digital distribution. Farfetch brought $4 billion in gross merchandise value and relationships with brands that Coupang’s logistics culture could never have cultivated organically. Yet the integration exposes a fundamental tension: Coupang’s operational excellence rests on standardization, predictability, and velocity, while fashion retail operates on scarcity, seasonal obsolescence, and taste-based curation.
Coupang’s infrastructure is optimized for items that do not spoil in the aesthetic sense. A Samsung refrigerator or a crate of diapers maintains its value across the seven-hour delivery window; a Balenciaga coat from Farfetch’s inventory enters a depreciation cycle the moment the season turns. The return rates in luxury fashion often exceed thirty percent, driven by fit inconsistency and buyer remorse, compared to the low-single-digit return rates on electronics and household goods that characterize Coupang’s core business. Each fashion return must be inspected, reconditioned, and re-inventoried, a process that consumes labor hours and warehouse space in ways that commodity goods do not.
The cultural mismatch runs deeper. Coupang’s merchandising algorithms prioritize availability and price stability; they treat inventory as a fluid resource to be moved efficiently through the pipeline. Fashion merchandising treats inventory as a narrative to be curated, with deliberate scarcity and brand positioning that resists the algorithmic flattening Coupang applies. When Coupang attempts to sell mid-priced cosmetics and apparel through its standard first-party channels, it competes against NAVER’s marketplace model, where thousands of third-party merchants specialize in micro-trends, K-beauty drops, and influencer-driven cosmetics cycles that change faster than Coupang’s warehouse procurement cycles can adapt.
The data illustrates the gap. Coupang claims price parity on approximately sixty percent of items against alternatives, yet concedes loss of price-sensitive consumers in apparel and cosmetics specifically. This is not a pricing problem; it is a selection problem. The consumer seeking a specific shade of lipstick released by a Korean beauty brand last Tuesday finds it on NAVER’s marketplace via a merchant who sourced it directly from the manufacturer that morning. Coupang’s first-party inventory model requires forecasting demand weeks in advance, purchasing stock, and holding it in warehouses. By the time the item reaches Coupang’s fulfillment center, the trend may have shifted, leaving the company holding depreciating inventory that must be marked down or written off.
Farfetch was supposed to solve this by providing access to luxury brands without inventory risk, arfetch operated on a marketplace model connecting boutiques with consumers, taking commission rather than holding stock. Yet Farfetch itself was bleeding cash when Coupang acquired it, struggling with the very problem Coupang now faces: the cost of customer acquisition in fashion exceeds the lifetime value unless the platform can own the customer relationship completely. Coupang’s bet appears to be that it can cross-pollinate Farfetch’s luxury relationships with its Rocket WOW membership, offering high-net-worth Korean consumers the same reliability on a $3,000 handbag that they receive on a grocery order.
Whether this works depends on whether luxury consumers want Coupang’s reliability more than they want the boutique experience. Luxury retail depends on unboxing rituals, personalized service, and the cachet of purchase environment. Coupang’s operational culture treats the $3,000 handbag as another item to be dropped in a cooler bag in an apartment hallway. The risk is that Farfetch’s brand partners, already skeptical of digital discounting, recoil from Coupang’s logistics-first aesthetic, or that consumers, offered Coupang’s reliability, discover that reliability matters less than selection when purchasing fashion. If the Farfetch integration fails to move the needle on apparel and cosmetics penetration, Coupang will have spent half a billion dollars to prove that its infrastructure cannot capture the discretionary categories that remain the last frontier of domestic growth.
The Rocket Men and the Labor Constraint
Beneath the technology narrative lies a labor model that is increasingly anomalous and increasingly expensive. Coupang employs its delivery drivers, Rocket Men, as full-time workers with benefits, health insurance, and guaranteed wages. In a market where competitors rely on gig economy contractors or third-party logistics providers, this represents both a structural advantage and a latent liability.
The advantage is control. Rocket Men wear Coupang uniforms, follow Coupang routing algorithms, and adhere to Coupang service standards. They can be trained to handle the specific protocols of unattended delivery, cooler bag placement, and high-rise building navigation that define the Coupang experience. They do not cherry-pick deliveries based on profitability, as gig drivers do, nor do they disappear during peak demand periods. This workforce stability enables the seven-hour delivery promise; without guaranteed labor availability, the system collapses during promotional periods or holiday rushes.
Yet the model carries fixed costs that variable labor does not. When order volume dips, the Rocket Men remain on payroll. When fuel prices spike, Coupang absorbs the margin compression rather than passing it to contractors. Most critically, as South Korean labor regulations tighten and minimum wages rise, Coupang faces cost increases that marketplace competitors avoid. NAVER’s logistics costs scale with volume; Coupang’s scale with headcount.
The density economics that make the Rocket Men model viable also create specific ergonomic pressures. The image of a single courier serving an entire high-rise with twenty packages masks the physical toll of the work. These workers navigate apartment complexes with heavy loads, often without elevators in older buildings, maintaining the pace required for seven-hour delivery windows. As the workforce ages and labor protections strengthen, the cost-per-delivery must rise, or the service standard must degrade. There is no technological solution to the physics of carrying a refrigerator up four flights of stairs; there is only the cost of the labor required to do it.
The fragility here is regulatory and demographic. If South Korea enacts stricter delivery driver protections, mandatory rest periods, weight limits on packages, or restrictions on the “drop and go” methods that enable efficiency, Coupang’s unit economics face immediate pressure. Competitors using third-party logistics simply pass these costs to their providers or shift to slower delivery models. Coupang, having built its brand on speed, cannot easily retreat to two-day delivery without destroying the trust moat it constructed. The Rocket Men are the physical manifestation of Coupang’s promise, but they are also a fixed-cost liability in a world moving toward variable labor models.
The Bundle’s Hidden Subsidy
The opacity of Rocket WOW’s economics deserves closer inspection. Fourteen million households pay between seven and seven dollars and fifty cents monthly for a bundle that includes unlimited delivery, streaming content, and food delivery discounts. At the midpoint, this generates roughly $1.2 billion in annual subscription revenue, ubstantial, but covering only a fraction of the logistics and content costs required to fulfill the promises.
Coupang Play, the streaming service included in the bundle, competes with Netflix and Disney+ for content rights in a market where Korean drama production costs have ballooned. Original content requires hundreds of millions in annual investment; licensed content requires recurring payments. Coupang Eats, the food delivery service, operates in a sector where even dedicated platforms struggle to achieve positive unit economics after accounting for driver subsidies and restaurant commissions. When bundled with retail delivery, these services disappear into the aggregate “membership value,” but they likely consume capital at rates that would alarm investors if reported separately.
The strategic logic holds that cross-usage reduces churn. Data shows that customers who use three or more services churn at rates significantly lower than those who use only one. The bundle creates a complex switching cost: to leave Coupang for NAVER, a subscriber must not only find a new place to buy diapers, but a new source for streaming content and food delivery discounts. Yet this logic assumes that the subsidy required to maintain the bundle remains constant or decreases as scale increases. In reality, content costs rise with competition, and food delivery economics deteriorate as the market saturates.
The danger lies in unbundling. If Coupang were forced, by regulatory pressure, shareholder demands, or competitive necessity, to separate these services and charge standalone prices, the value proposition fragments. Streaming alone at seven dollars monthly cannot compete with Netflix’s library. Food delivery discounts without the retail bundle lose their appeal. The bundle works because the true cost of each component is hidden; it fails if transparency is required.
Consider the scenario: suppose Coupang’s retail operations, stripped of the membership fee, operate at thin margins or slight losses, while the membership fee itself covers the losses in streaming and food delivery. In this case, Coupang is not a retailer with a membership program; it is a membership program that uses retail as a loss leader. The optics of this reversal would be severe. The company would be revealed as a capital-intensive media and logistics conglomerate rather than a retail innovator. The stock, valued on retail multiples, would need to be revalued on media or subscription metrics, likely downward given the capital intensity.
Moreover, the bundle creates a specific customer segmentation problem. High-income subscribers, who join primarily for the streaming and luxury retail access, effectively subsidize the frequent grocery shoppers who maximize the delivery benefit. As Coupang pushes into premium categories via Farfetch, it may attract subscribers who never use the grocery service, draining the cross-subsidy that makes the economics work. The bundle requires a specific mix of usage patterns to remain profitable; too many heavy users of the expensive components (delivery, streaming) without sufficient purchase of high-margin retail goods, and the model bleeds.
NAVER and the Platform Alternative
To understand Coupang’s vulnerability, one must understand what it is not. NAVER, the portal and search giant, operates the largest e-commerce marketplace in South Korea through its Smart Store platform. NAVER does not own warehouses. It does not employ drivers. It connects buyers with sellers, taking a commission on transactions and selling advertising to merchants who wish to appear in search results. It is, in classical terms, a platform.
NAVER’s model sacrifices reliability for selection. A consumer searching for a specific Korean beauty product on NAVER finds dozens of merchants offering it, often at prices lower than Coupang’s, with varying shipping speeds and return policies. The consumer must evaluate merchant ratings, shipping times, and authenticity guarantees independently. For high-consideration purchases, expensive electronics, appliances, this variability creates friction that drives consumers to Coupang’s guaranteed experience. For low-consideration, price-sensitive purchases, trendy apparel, cosmetics, novelty items, the variability is acceptable in exchange for lower prices.
NAVER’s advantage increases as transaction frequency rises in discretionary categories. The Korean beauty market operates on “drops”, imited edition colorways and collaborations that sell out within hours. NAVER’s merchants can list these immediately upon release, adjusting prices dynamically based on demand. Coupang’s first-party model cannot match this velocity; by the time Coupang has negotiated procurement, received inventory, and positioned it in warehouses, the trend has passed.
The competitive dynamic suggests a segmentation of the market that threatens Coupang’s growth. Coupang captures the “needs” retail, groceries, household goods, electronics, where reliability dominates. NAVER captures the “wants” retail, fashion, beauty, collectibles, where selection and price dominate. As Coupang saturates the needs market, its attempt to capture wants retail requires competing on NAVER’s terms (selection, price) while maintaining its own cost structure (logistics ownership). This is a structurally losing proposition unless the Farfetch integration fundamentally alters the selection available through Coupang’s reliable infrastructure.
The risk is bifurcation: Coupang becomes the utility for commoditized goods, earning utility-like margins, while NAVER captures the high-margin discretionary spending. In this scenario, Coupang’s $1,100 annual spend per customer plateaus or declines as discretionary spending shifts to platforms, leaving Coupang with expensive logistics infrastructure serving low-margin commodity categories. The density advantage becomes a density trap, nough volume to maintain the network, but not enough margin to justify the capital invested.
The Cohort Trajectory and Its Limits
The threefold increase in customer spend since 2018, from roughly $366 to $1,100 annually, represents the core bull case for Coupang. The narrative suggests that as customers mature within the Coupang ecosystem, they progressively outsource more categories of spending to the platform, increasing lifetime value and justifying the upfront acquisition and logistics costs.
This trajectory relies on specific temporal conditions that may not persist. The 2018-2023 period coincided with the maturation of Coupang’s logistics network, the introduction of Rocket Fresh grocery delivery, and the expansion of the Rocket WOW membership. Customers acquired during this period experienced a continuously improving service, aster delivery, more categories, better streaming content. Their increasing spend reflects both habit formation and service expansion.
For new customers today, entering a mature system, the experience is different. The logistics network is already built; there are no new speed improvements to discover. The grocery service is already available; there is no new category expansion to drive incremental spend. These customers enter at the $1,100 level rather than growing toward it. If the average spend per customer is to continue rising, it must come from price increases or share capture in weak categories like apparel, recisely the areas where Coupang faces structural disadvantages.
Moreover, the cohort data likely masks significant heterogeneity. Early adopters, urban apartment dwellers in Seoul, may have spending trajectories that plateau naturally as their needs are fully met. Late adopters, rural households or older consumers, may have lower baseline spending and less propensity to adopt ancillary services like streaming. As Coupang penetrates the final one million households in Korea, it is capturing the marginal, least-engaged consumers, potentially dragging down the average spend per user even as total revenue grows.
The compounding effect also assumes continued subsidy of the membership bundle. If Coupang were forced to raise Rocket WOW prices to cover the true cost of delivery and content, say, to fifteen or twenty dollars monthly, the usage patterns might shift dramatically. At higher price points, consumers become more deliberate about subscription value, potentially canceling during months of low usage or unbundling services. The threefold spend growth assumes a locked-in, low-friction relationship; higher prices introduce friction.
The bear case on cohorts suggests that the $1,100 figure represents a ceiling, not a trajectory. Having captured the household basics, groceries, electronics, household goods, there is simply no more wallet to capture outside of apparel and luxury, where Coupang lacks advantage. The infrastructure built to serve $1,100 per customer cannot easily be scaled down if spend plateaus; the fixed costs of the Rocket Men and warehouses remain. The business would then face the classic retail saturation problem: flat revenue on a high fixed-cost base, with margin pressure from the inevitable price competition that comes when growth stalls.
The Trust Decay Scenario
All of Coupang’s advantages rest on a final, fragile assumption: that the cultural conditions enabling its trust-based model will persist indefinitely. This assumption encompasses both the low-theft environment and the regulatory stability that permits its specific operational shortcuts.
The “doorstep trust” is not merely about crime statistics. It is about the social contract in Korean apartment complexes, where communal living creates mutual surveillance and social pressure that discourages theft. As housing patterns shift, or as economic inequality creates pockets of desperation, the viability of unattended delivery may erode. If theft of cooler bags or packages rises even marginally, Coupang faces a binary choice: maintain the unattended delivery model and absorb shrinkage costs that destroy margins, or switch to verified handoff delivery that eliminates the efficiency gains of the single-courier, multi-drop system.
Similarly, the regulatory environment that permits unpackaged returns, where customers leave items in hallway corridors for pickup, assumes a level of hygiene and building management that may not persist. A single incident of food spoilage in a shared hallway, leading to pest infestation or conflict with building management, could trigger regulatory review of delivery practices. Apartment complex associations, increasingly powerful in Korean urban governance, could ban unattended delivery or cooler bag storage, forcing Coupang into expensive building-by-building negotiations or into less efficient delivery models.
The trust moat is also vulnerable to quality control failures at scale. As Coupang expands its third-party marketplace component, necessary to compete with NAVER on selection, it introduces merchant variability into a system built on first-party reliability. A series of counterfeit goods scandals or shipping delays from third-party sellers could damage the brand’s reliability premium, creating the worst of both worlds: the capital costs of owned logistics and the reputational damage of marketplace inconsistency.
In this scenario, Coupang becomes not the reliable alternative to NAVER, but a more expensive version of the same unreliable experience, burdened with infrastructure costs that NAVER avoids. The switching costs that bind customers to Rocket WOW dissolve if the service no longer guarantees the reliability that justified the subscription. The fourteen million members, faced with a degraded experience and persistent membership fees, churn rapidly, reverting to NAVER for selection and to specialized apps for groceries and delivery.
This is the terminal risk: not that Coupang is displaced by a better logistics network, no competitor can afford to build one, but that the cultural and regulatory foundation of its density advantage shifts beneath it, turning its operational perfection into an expensive anachronism. The business would survive, but as a diminished utility, its growth story concluded, its capital intensity revealed as a burden rather than a moat. The founder’s hand on the lever would then face its final test: whether to harvest the business for cash, or to deploy yet more capital into a model that has reached its natural limit.