
Fanatics: Manufacturing Speed as Competitive Advantage

When a star quarterback is traded at the NFL deadline, a peculiar manufacturing sequence begins. Within hours, jerseys bearing his new team’s colors appear on Fanatics-powered websites, ften before the player has boarded the private jet to his new city. This is not inventory shuffling. These garments do not exist in a warehouse when the trade is announced. They are manufactured, printed, and shipped in the lag between news breaking and credit card authorization. The company calls this V-commerce: real-time production triggered by demand signals rather than forecasting algorithms.
To the consumer, it looks like logistics excellence. To Michael Rubin, who bought the business back from eBay’s GSI Commerce in 2011 for a modest sum and has since grown it to roughly $3 billion in revenue, it is the load-bearing wall of a structure that is still half-built. Fanatics does not merely sell sports merchandise. It is attempting to construct a closed loop in which exclusive rights to 900 sports properties, proprietary manufacturing capacity, and an 81-million-user database reinforce one another to capture an expanding share of the sports economy. The gross margins, approximately 40 percent, against 15 to 20 percent for traditional e-commerce, suggest the model works in isolation. Whether it works as a platform is the question that will determine if Fanatics becomes a permanent fixture of sports commerce or a cautionary tale about overreach.
The Inventory Problem That Isn’t
Most retail operations die by the forecast. Buy too much inventory, and margin evaporates in clearance bins. Buy too little, and revenue walks to competitors. Fanatics solved this by reversing the sequence. Approximately half of its core commerce merchandise is produced through vertical integration, factories and print facilities it owns or controls directly, allowing the company to manufacture in response to actual demand rather than predictive models. When a rookie unexpectedly breaks a record, or when a veteran is traded, the system produces the goods after the event has occurred.
This operational choice creates economic effects that compound. First, the elimination of inventory risk removes the margin tax that crushes traditional apparel retail. Second, the compression of distribution layers, no wholesalers, no middlemen, captures value that would otherwise leak to intermediaries. Third, and most critically, it enables product exclusivity. Because Fanatics manufactures on demand, it can offer designs and variations that never appear on Amazon or in stadium stores. The exclusive product creates the traffic; the traffic feeds the database; the database improves the manufacturing forecasts.
Competitors struggle to replicate this not because they lack capital, but because the moat is operational and temporal. Building real-time manufacturing capacity requires years of supply chain engineering, relationships with textile suppliers willing to operate on compressed timelines, and data science capable of predicting demand spikes minutes after a game ends. Amazon’s generalist logistics infrastructure, optimized for moving existing inventory efficiently, cannot easily pivot to producing garments that did not exist yesterday. The manufacturing advantage is defensible precisely because it is boring and capital-intensive, requiring sustained investment during years when the payoff is uncertain.
Yet this advantage is also a cage. Fanatics has committed to a model that requires continuous heavy investment, $250 million annually in marketing alone, over $1 billion since 2016, while maintaining manufacturing capacity that must be fed with volume to achieve efficiency. The company is deliberately in “investment mode,” deprioritizing margin expansion to capture market share. This is not a phase. It is a structural necessity. The manufacturing infrastructure only achieves its 40 percent gross margins at scale; scale requires customer acquisition; customer acquisition requires spending that depresses near-term profitability. If the company stops investing, the flywheel slows, unit economics deteriorate, and the advantage bleeds away. The constraint is absolute: Fanatics cannot optimize for profit until it has achieved dominant scale, but achieving that scale requires betting that the capital markets, or a prospective public offering, will continue to fund the burn indefinitely.
The League Partnership as Faustian Bargain
The manufacturing capacity would be worthless without the rights. Fanatics holds exclusive, long-term deals, often twenty years or more, with the NFL, NBA, MLB, NHL, and over 900 properties across eleven countries. These rights are not merely commercial agreements; they are structural barriers to entry that prevent Amazon or other well-capitalized competitors from simply outbidding their way into the market. When leagues renew with Fanatics, they do so because the company has demonstrated an ability to grow the merchandise total addressable market: royalties paid to partners have increased twentyfold since 2006.
The alignment appears perfect. Leagues receive guaranteed payments regardless of sales channel, and in some cases hold equity stakes in Fanatics. As the company grows, so do league revenues. But alignment is a function of category, and Fanatics is no longer content to remain a commerce company. It is expanding into sports betting, NFTs, digital collectibles, and data monetization, ategories where the league’s interests may diverge sharply from Fanatics’ profit maximization.
In merchandise, the league and Fanatics want the same thing: more jersey sales. In betting, the league wants integrity, fan engagement, and a slice of the handle without reputational risk. Fanatics wants the customer data, the recurring revenue, and the cross-selling opportunity. If Fanatics uses its 81-million-user database to drive betting adoption, leagues may grow uneasy about how their fans are being monetized, or who controls the relationship. If Fanatics’ betting operations generate regulatory scrutiny, sports betting faces fragmented state-by-state regimes in the United States, the leagues may demand concessions or separation that impair the platform strategy.
The fragility lies in the renegotiation trigger. If Fanatics successfully builds a betting or NFT business worth billions, leagues will inevitably reassess whether they granted rights too cheaply, or whether they should have retained data ownership as a condition of those 20-year deals. A competitor, DraftKings, a traditional media company, or even a league-owned entity, could offer leagues direct equity in new verticals or higher royalty rates, testing the durability of Fanatics’ exclusive relationships. The company has structured deals to align incentives, but it has not solved the principal-agent problem. Fanatics is becoming a platform; leagues may decide they prefer vendors.
Capital as Strategy
The risk of league defection or category failure would normally suggest a defensive posture: consolidate the core, harvest cash flows, diversify carefully. Fanatics has done the opposite. Rubin has deployed capital with the aggression of a company that believes the window for establishing infrastructure is narrow and closing. The $250 million annual marketing spend has driven aided brand awareness to 60 percent, but it has also created a dependency. The company adds eight million new customers annually, maintaining a database of 57 million active customers who generate forty million transactions per year. This growth requires continuous fuel. Slow the marketing engine, and customer acquisition costs rise as competitors capture the marginal fan. Reduce technology investment, and the real-time manufacturing advantage degrades.
This is not mismanagement. It is a recognition that sports commerce is winner-take-most. The company that captures the fan relationship owns the data; the company that owns the data can cross-sell new categories at acquisition costs that competitors cannot match. But the strategy assumes that capital will remain available on acceptable terms, and that the core commerce business will remain healthy enough to fund speculative expansion into trading cards and betting while those categories mature. If the core business slows, if consumer spending on apparel shifts, or if a recession compresses discretionary purchases, the company lacks the margin cushion to absorb pressure without restructuring. Conversely, if Fanatics cuts investment to demonstrate profitability, it risks ceding market position to better-capitalized competitors or reducing the consumer experience that justifies the premium pricing.
The leadership function here is purely economic. Rubin’s decision to operate in permanent investment mode is a capital allocation choice that treats the business not as a cash generator but as a capture mechanism for latent demand in the sports economy. The culture is built for speed and scale, not efficiency. This works while growth rates justify the burn. It becomes existential if growth stalls.
Integration at the Edge
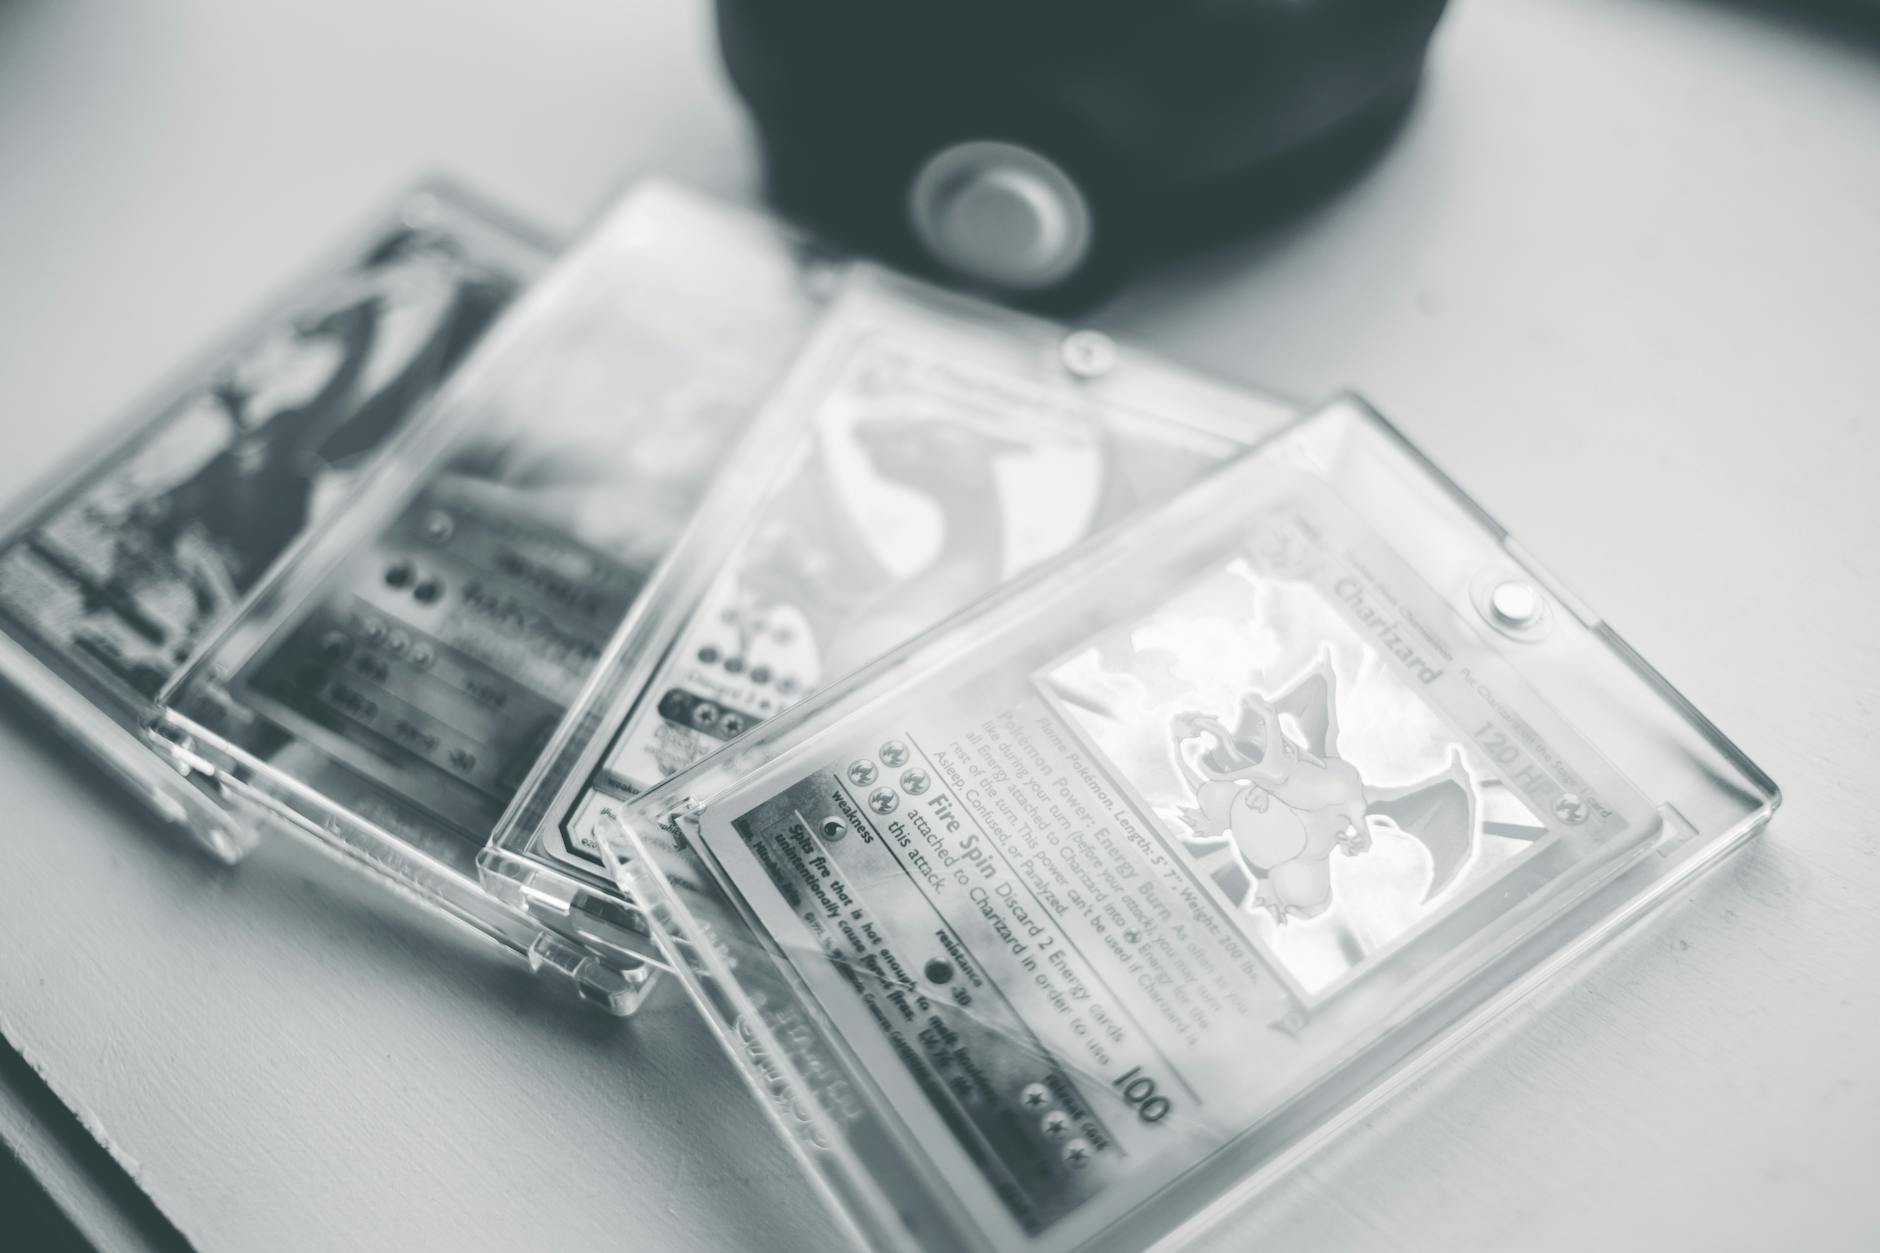
The most precarious expansion is into trading cards. Fanatics acquired Topps, historically the incumbent in baseball cards, and is attempting to restructure an industry built on multi-layer wholesale distribution into a direct-to-consumer model. The logic is familiar: eliminate the intermediaries, capture the margin, control the customer relationship. The execution is unprecedented. Trading cards are not apparel. They involve grading, authentication, insurance, and secondary market dynamics that require fundamentally different operational capabilities than printing jerseys on demand.
The company has no proven playbook for integrating trading card manufacturing at scale, nor for operating secondary market platforms that require trust and liquidity mechanisms alien to commerce. If Fanatics over-integrates, attempting to own manufacturing, grading, and exchange for collectibles, it creates operational complexity and capital intensity in a category with different cyclical dynamics than apparel. If it under-integrates, relying on third-party grading services or marketplaces, it leaves margin on the table and weakens the strategic rationale for the acquisition.
Moreover, the trading card market may be a poor fit for the V-commerce model. Cards derive value from scarcity and condition; unlimited on-demand production could collapse the collectible premium that drives the category. Fanatics must navigate a narrow passage: modernize distribution without destroying the scarcity economics that make cards valuable. The MLB rights, which Fanatics acquired early from Topps (originally held until 2026), provide the content. Whether they provide a business model remains uncertain.
The Database Trap
At the center of the platform thesis sits the 81-million-user proprietary database, ransaction histories, behavioral signals, cross-category engagement data. This asset is theoretically the key to unlocking value in betting, NFTs, and collectibles. Fanatics assumes it can cross-sell these new categories to existing commerce customers at lower acquisition costs than standalone competitors, compounding customer lifetime value across multiple revenue streams.
This assumption faces three challenges. First, regulatory fragmentation in sports betting may prevent Fanatics from leveraging the database fully. State-by-state restrictions could limit how customer data is used for targeting, or impose compliance costs that erode the margin advantage. Second, leagues may demand data governance concessions as a condition of rights renewal, particularly if they perceive Fanatics’ data monetization as competing with league-owned fan engagement initiatives. If leagues insist on owning or controlling the fan data generated through merchandise sales, the cross-selling thesis collapses.
Third, and most subtle, is the risk of category fatigue. The database is valuable only if the same customer who buys a jersey also wants to bet on the game and collect NFTs. If these categories appeal to distinct psychographics, or if aggressive cross-selling alienates customers who prefer transactional simplicity, the unit economics of expansion fail to justify the investment. The company assumes that fan identity is monolithic, hat the person who buys the jersey wants to live inside Fanatics’ ecosystem for all sporting activities. This may be true for the most engaged fans, but the marginal customer, the eight million new additions annually, may resist the enclosure.
The Moment of Truth
Fanatics is attempting to build a full-stack sports platform in an industry historically organized around fragmented, specialized vendors. The bet is that vertical integration in manufacturing, combined with exclusive rights and proprietary data, creates a moat deep enough to justify massive upfront investment, and that the company can expand from commerce into adjacent high-margin categories before leagues reassert control or manufacturing complexity overwhelms execution capacity.
The structural advantages are real: the 40 percent gross margins, the real-time production capability, the locked-in rights deals, and the database scale are genuine barriers to entry. But they are contingent. The manufacturing advantage assumes continued scale and operational excellence in categories beyond apparel. The rights advantage assumes leagues will not renegotiate terms as Fanatics captures value in betting and digital assets. The data advantage assumes regulatory forbearance and customer acquiescence to cross-selling.
The company has grown from $250 million in revenue to roughly $3 billion in just over a decade by solving a specific problem, inventory risk in sports merchandise, at massive scale. The next decade requires solving a different problem: platform governance. Fanatics must manage league partners who are also shareholders, navigate regulatory mazes that vary by state and country, and integrate manufacturing capabilities into businesses like trading cards where the V-commerce model may not apply. It must do all this while maintaining the investment pace necessary to defend its market position, without the margin cushion that would allow it to retreat into profitability if growth slows.

The thesis holds only if the flywheel continues to accelerate: more rights lead to more customers, more customers improve manufacturing efficiency, better manufacturing enables exclusive product, exclusive product drives database growth, and the database enables new high-margin categories. If any spoke breaks, if a major league defects, if manufacturing costs overrun, if betting regulations fragment the market, or if fans reject the platform enclosure, the structure does not merely slow. It unwinds. In sports, momentum is everything until it isn’t. Fanatics is betting that it can outrun the physics of its own ambition.
The trading card acquisition reveals the friction most clearly. When Fanatics purchased Topps for approximately $500 million in 2022, it inherited not merely a brand but an industrial archaeology: decades of wholesale relationships with hobby shops, a grading infrastructure dependent on third-party authentication, and a secondary market that operates on scarcity principles fundamentally incompatible with real-time manufacturing. The baseball card ecosystem functions because Bowman Chrome prospect cards are printed in finite runs, sealed in wax packs, and distributed through a network of local card shops that serve as community hubs. Fanatics’ impulse, eliminate the layers, sell direct, capture the margin, assumes that cards are merely another SKU in the apparel logic. They are not.
The economics of collectibles depend on artificial scarcity manufactured through print runs and pack odds. A rookie card holds value because collectors know only five hundred specimens exist in gem mint condition. Fanatics’ V-commerce model, by contrast, derives its 40 percent gross margins from the elimination of scarcity, from the ability to produce inventory precisely when demand materializes. These are opposing magnetic fields. If Fanatics applies apparel logic to cards, printing on demand when a prospect gets called up from the minors, it destroys the speculative value that drives the category. If it respects the scarcity model, it cannot leverage its manufacturing advantage, and the acquisition becomes a traditional wholesale business with the same intermediary costs Fanatics was built to eliminate.
The operational complexity compounds through the grading bottleneck. Unlike a jersey, which ships directly to the consumer in a polybag, a trading card requires authentication and condition assessment before it achieves liquidity. The industry relies on third-party graders, PSA, Beckett, SGC, who operate as independent arbiters of value. Fanatics has hinted at vertical integration here as well, potentially bringing grading in-house to capture that margin layer. But grading is not manufacturing. It is liability-intensive reputation management. A misgraded card can destroy thousands of dollars in collector value and generate litigation. The specialized labor required, trained examiners working under magnification, does not scale with the same velocity as screen-printing operations. If Fanatics attempts to automate grading or compress timelines to match its apparel velocity, it risks the authentication errors that would poison the Topps brand. If it maintains the slow, careful processes the category demands, it cannot achieve the throughput necessary to justify the acquisition price.
The NFT experiment demonstrated this category mismatch in real time. Fanatics launched Topps NFTs in 2021, attempting to port the digital collectibles model to blockchain infrastructure. The initial drops generated speculative fervor, with packs selling out in minutes. Then the broader NFT market collapsed, and Fanatics discovered that digital collectibles lack the physical constraints that create genuine scarcity in cardboard. Without the manufacturing bottleneck that limits physical card supply, digital assets proved too easy to produce, too difficult to authenticate as genuinely rare, and too exposed to regulatory uncertainty regarding securities law. The company has since pivoted toward “digital collectibles” without the blockchain mechanism, but the lesson persists: the V-commerce model that conquered apparel requires physical constraints to function. In purely digital categories, where replication is costless and scarcity is performative rather than material, Fanatics possesses no operational advantage. It is merely another content licensor competing with video games, social media, and league-owned platforms for attention.
This limitation exposes the broader fragility of the platform thesis. Fanatics assumes that its 81-million-user database provides a low-cost acquisition channel for any sports-related category. But the data shows purchase history for hats and jerseys, not propensity for speculative gambling or digital asset collection. The cross-selling assumption relies on a theory of the sports fan as a monolithic economic agent, omeone whose identity is sufficiently wrapped in team loyalty that they will accept Fanatics as the gateway for betting, banking, and investing. This may hold for the top decile of engaged consumers who buy authentic jerseys and subscribe to league passes. It likely fails for the marginal customer acquired through Facebook advertising during playoff season, who purchases a discounted t-shirt and never returns to the site. As Fanatics saturates the core apparel market, the marginal customer becomes the average customer, and the database quality degrades.
The league alignment tension operates on a slower fuse but carries greater explosive force. Consider the specific mechanics of the NFL deal, reportedly extending through 2028 with renewal options. In the early years, the partnership produced mutual benefit: Fanatics guaranteed minimum royalties that exceeded prior licensing revenues, while the league received equity upside in a rapidly appreciating private company. But we are approaching the midpoint of these 20-year agreements, and the economic landscape has shifted. When Fanatics signed these deals, it was a merchandise company. Now it is a betting operator, a digital wallet provider, and a data aggregator. The leagues granted rights to sell polyester shirts. They did not anticipate granting rights to monetize fan behavior across casino gaming and financial services.
The renegotiation risk materializes in year twelve or fourteen, when the NFL’s contract comes up for discussion in an environment where sports betting generates $100 billion in annual handle and Fanatics’ sportsbook is capturing market share using data derived from jersey sales. The league will face a choice: renew with Fanatics at terms that reflect the expanded enterprise value, or fragment the rights by category, granting betting access to DraftKings or ESPN BET while retaining data rights for a league-owned platform. The original contracts likely contain change-of-control provisions and performance minimums, but they almost certainly do not contain provisions granting leagues equity in new business lines that did not exist when the agreements were drafted. Fanatics has structured itself as a platform precisely to capture value in these adjacent categories. The leagues will eventually recognize that they granted the platform rights too cheaply, or that Fanatics’ control of the fan relationship threatens their own direct-to-consumer ambitions.
The NFL’s recent launch of NFL+, its proprietary streaming and fan engagement platform, signals this awakening. If the league can own the direct relationship, streaming games, selling tickets, operating fantasy leagues, it no longer requires Fanatics as the intermediary for fan data. The merchandise rights become separable from the identity layer. When that separation occurs, Fanatics reverts to being a vendor with manufacturing capabilities, not a platform with proprietary access. The twenty-year contracts that appear to lock in competitive advantage may become straitjackets, binding Fanatics to legacy economics while the league extracts itself from the data provisions.
The regulatory environment for sports betting adds another vector of constraint that undermines the database advantage. Fanatics operates its sportsbook under the assumption that its existing customer file provides a unified acquisition channel. But gaming regulation in the United States fragments precisely along the lines that make such unification illegal or impractical. In New York, promotional credits for betting must be segregated from retail merchandise offers to prevent cross-subsidization that violates gaming commission rules. In California, where betting remains illegal, Fanatics cannot leverage its customer data to pre-position users for future legalization without violating privacy provisions regarding gambling inducements. In Ohio, the gaming commission requires that sportsbook operators maintain separate data infrastructure from non-gaming affiliates to prevent money laundering through merchandise purchases.
Each state imposes a compliance tax that erodes the supposed synergy between commerce and betting. The database that generates 40 percent margins on apparel cannot be freely deployed for gaming acquisition. Customer acquisition costs in regulated betting markets remain high precisely because the data moat is partially drained by regulatory requirements. Fanatics must build separate compliance infrastructure for each jurisdiction, duplicating costs that the platform model was supposed to eliminate through shared overhead. The result is not a unified sports economy but a balkanized operation where the left hand (commerce) cannot legally know what the right hand (betting) is doing.
Beyond the regulatory barriers, the operational complexity of expanding manufacturing into hard goods and collectibles threatens the very margin structure that funds the company’s growth. Apparel V-commerce works because textiles are forgiving. A cotton blend can be screen-printed, shipped, and returned with minimal loss if the consumer rejects the product. Trading cards, by contrast, are condition-sensitive assets where a bent corner destroys value. Authentication, insurance, and secure shipping add cost layers that do not exist in apparel. If Fanatics attempts to integrate these functions to capture margin, it enters businesses, logistics for high-value collectibles, insurance underwriting, grading arbitration, where it has no operational history and where mistakes destroy brand equity overnight.
The NFT failure provided a preview. When Fanatics launched its blockchain collectibles platform, it discovered that the customer service burden for digital asset disputes, wallet errors, transaction failures, speculative losses, far exceeded anything in physical retail. The company was equipped to handle “where is my jersey” inquiries. It was not equipped to handle “my Ethereum transaction failed and I lost $4,000 on a virtual Mickey Mantle” complaints. The infrastructure required to support speculative financial products differs categorically from that required for consumer goods. As Fanatics pushes further into betting and collectibles, it will find that each new category requires specialized compliance, customer service, and risk management capabilities that dilute the supposed efficiencies of the platform model.
There is also the temporal problem of the twenty-year contract. In year one, the deal provides certainty: guaranteed supply, exclusive access, locked-in economics. By year fifteen, it becomes a liability. Consumer preferences shift. The licensed apparel market may contract as younger fans express loyalty through digital skins in video games rather than physical jerseys. If the total addressable market for merchandise shrinks while Fanatics remains contractually obligated to pay minimum royalties to leagues, the company faces a squeeze where fixed costs rise against declining revenue. The long-term rights that prevent Amazon from entering simultaneously prevent Fanatics from exiting. It is committed to the physical merchandise business even as the culture moves toward digital expression.
Amazon, meanwhile, waits. The e-commerce giant has not pursued sports licensing aggressively because the category requires specialized manufacturing and rights management that conflict with Amazon’s generalist logistics model. But if Fanatics stumbles, if manufacturing quality degrades, if league relationships fracture, if the betting expansion fails, Amazon could acquire a distressed competitor or simply outbid for rights in a renegotiation scenario. Fanatics’ moat depends on continuous operational excellence. It is not protected by network effects or switching costs that lock in consumers; a fan can as easily buy a jersey from Amazon as from Fanatics if the rights become available. The exclusivity is contractual, not technological, and contracts expire.
The vertical integration that generates 40 percent gross margins also creates capital intensity that becomes dangerous in a rising interest rate environment or economic downturn. Fanatics has invested over a billion dollars in manufacturing infrastructure, marketing, and technology. These are sunk costs that require volume to justify. In a recession, when discretionary spending on licensed apparel contracts by 20 or 30 percent, Fanatics cannot simply reduce inventory purchases as a traditional retailer might. It owns the factories. It must either idle capacity and absorb fixed costs, or produce into a collapsing market and destroy pricing discipline. The V-commerce model assumes steady or growing demand. It has not been stress-tested against sustained contraction in sports consumption.
The company’s culture, built for speed and acquisition, may prove ill-suited to the stewardship businesses that are now central to its strategy. Trading card collectors are preservationists, archivists, and historians. They value slowness, provenance, and tradition. Fanatics is built for velocity, for the trade deadline rush, for the immediate satisfaction of the impulse purchase. These are incompatible operating systems. As Fanatics attempts to serve both the fan who wants a jersey shipped in two hours and the collector who spends months hunting for a 1952 Topps Mickey Mantle, it risks alienating both constituencies. The platform strategy assumes that all sports consumption can be harmonized under one corporate identity. The reality is that betting, collecting, and apparel shopping attract different psychographics with different expectations of trust, speed, and permanence.
Ultimately, Fanatics is conducting an experiment in industrial organization: whether a company can simultaneously own manufacturing, rights management, retail distribution, gambling operations, and financial services without collapsing under the weight of conflicting regulatory regimes, incompatible customer expectations, and divergent margin structures. The 40 percent gross margins in apparel fund investments in categories where margins are thinner and risks are higher. The database asset is less transferable than the valuation assumes. The league partnerships are more fragile than the twenty-year terms suggest. And the V-commerce model, while brilliant for polyester garments, may prove inapplicable to the scarcer, more regulated, more contingent categories where Fanatics is now placing its bets.
The company has built a remarkable machine for capturing the sports economy at its most liquid and predictable. Whether that machine can be retooled to handle the illiquidity of collectibles, the volatility of betting regulation, and the inevitable renegotiation with league partners who have grown wise to its platform ambitions remains the defining question. For now, the momentum carries forward, fueled by $250 million in annual marketing spend and the sheer will to outrun complexity. But complexity has a way of catching up, particularly when the contracts are long, the manufacturing is fixed, and the leagues are watching.
The fixed-cost structure creates an asymmetry that favors competitors during contraction. Traditional retailers like Dick’s Sporting Goods or even Amazon’s third-party marketplace operate on variable cost models, hey purchase inventory only when consumer demand materializes, and in downturns, they simply reduce orders. Fanatics cannot. Its owned manufacturing facilities in Florida and Texas carry depreciation schedules and labor commitments that persist regardless of whether the Cowboys make the playoffs or the trading card bubble deflates. When demand drops, the 40 percent gross margin compresses not gradually but catastrophically, as underutilized capacity converts from competitive advantage into balance sheet deadweight.
Consider the specific scenario now emerging as interest rates normalize. Fanatics has raised capital at valuations predicated on perpetual growth investment: ffectively, the company has been priced as a technology platform rather than a capital-intensive manufacturer. If the next funding round or public offering requires demonstrating a path to profitability, the operational adjustments available are limited and painful. Marketing cuts would immediately slow customer acquisition, threatening the database growth required to justify the betting expansion. Manufacturing capacity cannot be easily idled without violating league commitments to merchandise availability. The $250 million annual marketing spend is not discretionary brand building; it is the fuel for the flywheel. Remove it, and the 8 million new customers annually become 3 million, and the database stops compounding.
This capital structure trap reveals the true fragility of the vertical integration moat. It is only a moat while the company is attacking. In defense, during market contraction or competitive pressure, it becomes a fort under siege. The leagues, observing this vulnerability, may accelerate their timeline for renegotiation. If the NFL perceives that Fanatics is trapped in fixed-cost obligations while merchandise sales soften, it has leverage to demand equity in the betting division or data rights that Fanatics cannot afford to refuse. The twenty-year contract becomes not a protection but a ransom note, with the league extracting concessions from a company that cannot threaten to walk away without destroying its own valuation.
The trading card acquisition thus looks less like strategic expansion and more like a desperate attempt to diversify revenue before the core business faces its inevitable cyclical test. But cards are cyclical in different ways than apparel, moving with speculative asset bubbles rather than seasonal sports calendars. Fanatics is now exposed to both the recession risk of discretionary retail and the volatility of collectibles markets, with a capital structure designed for neither. When the music stops, the company will find itself holding not a platform, but a collection of expensive factories, long-term royalty obligations, and a database that cannot be monetized fast enough to cover the burn. And in that moment, the leagues will be watching not as partners, but as creditors deciding whether to call the loan.