
Fastenal: The Inventory Bank Thesis
The Inventory Bank
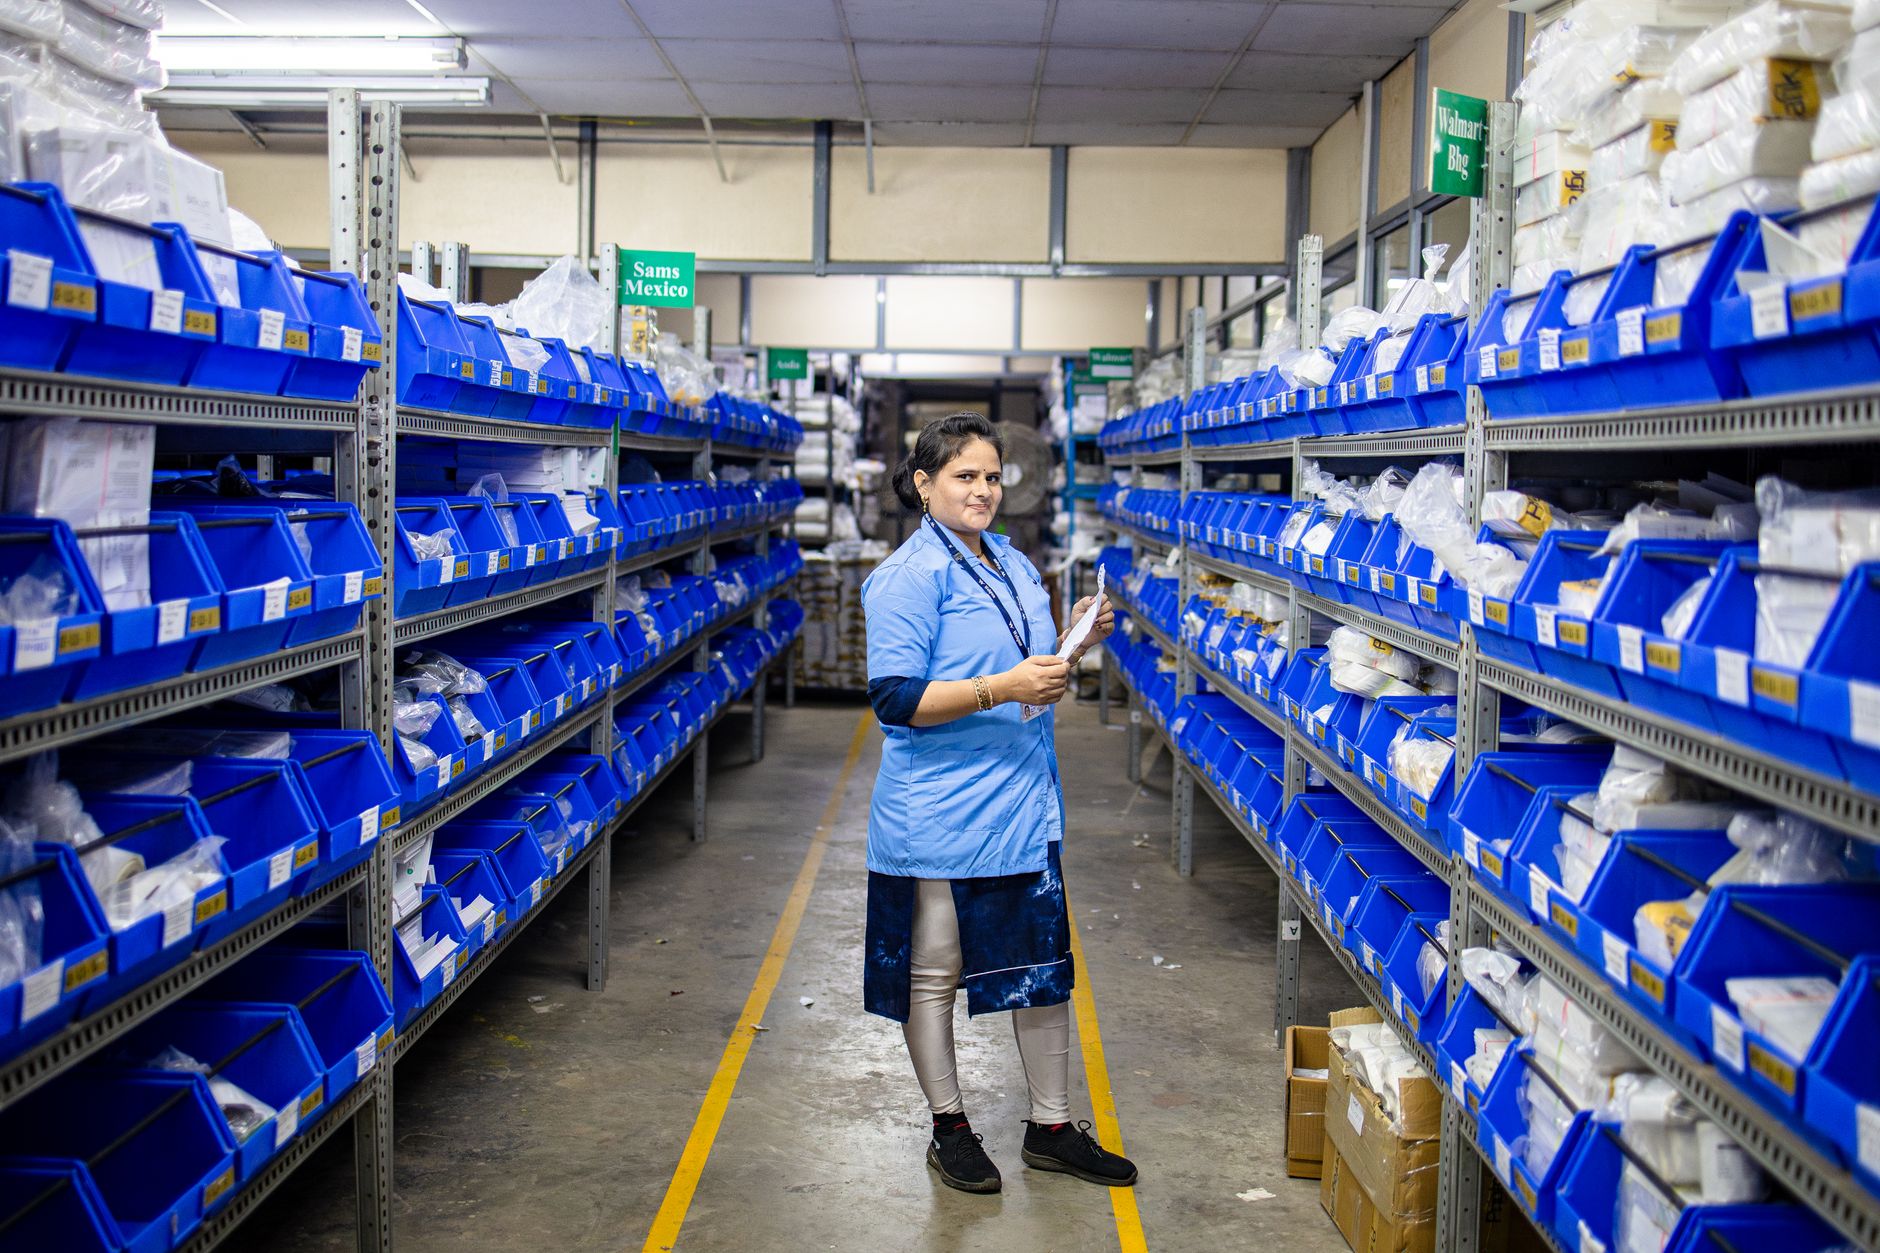
To understand why a company selling screws, gloves, and janitorial supplies commands a fifty-billion-dollar market capitalization and generates returns on capital exceeding thirty percent, one must look past the merchandise to the balance sheet. Fastenal is not, in any meaningful sense, a distributor. It is a bank that accepts deposits of inventory risk and pays its depositors: he industrial manufacturers and construction firms that comprise its customer base, ot in interest, but in reclaimed hours and reduced working capital. The company holds approximately ninety thousand SKUs on its own books so that its customers do not have to, charging a twenty percent EBIT margin for the service of immediate availability. This margin is not extracted from the sale of fasteners; it is the rent paid for the elimination of procurement friction.
The mechanism is straightforward but economically potent. A manufacturing plant requiring specialty bolts could manage its own supply chain, egotiating with multiple vendors, maintaining safety stock, tracking consumption, and absorbing the administrative burden of reordering. Or it can allow Fastenal to install an employee on its factory floor, stock a crib of inventory on Fastenal’s dime, and replenish bins automatically via RFID-enabled sensors. In choosing the latter, the customer reduces its procurement labor by half, cuts inventory holdings by more than a third, and eliminates the waste and theft that typically consume twenty percent of industrial supplies. Fastenal, meanwhile, earns a consistent twenty percent operating margin, two to three times that of peer industrial distributors, while turning its inventory rapidly enough to generate those exceptional capital returns.
This model creates a peculiar capital structure. Fastenal grows by increasing its working capital, not by building factories or acquiring heavy equipment. Each new Onsite location, a dedicated facility within a customer’s operation, requires Fastenal to fund inventory on its balance sheet with no contractual lock-in from the customer. The company now operates over two thousand such Onsites, up from roughly one thousand a decade ago, and these locations contribute forty percent of revenue. Yet the balance sheet intensity is not a bug but the feature that creates switching costs. Once Fastenal’s inventory is physically embedded in a customer’s workflow, once its employees attend the customer’s production meetings and manage the replenishment cadence, the relationship becomes operationally sticky. The customer could switch to a lower-priced distributor, but doing so would require rebuilding the procurement infrastructure Fastenal has dismantled: cost that typically exceeds the savings from cheaper unit prices.
The Geography of Frugality
The durability of Fastenal’s returns depends on a cultural attribute so specific it functions as a structural moat: the company’s institutionalized aversion to corporate excess. This is not philanthropy or branding. It is an operating requirement that enables the company to serve markets where rational competitors cannot generate acceptable returns. Half of Fastenal’s revenue originates in municipalities with populations under five hundred thousand, owns where the industrial base might support a single branch but not the overhead of a typical corporate distribution facility.
In these small markets, Fastenal operates with a frugality that would embarrass most public companies. Branch managers occupy low-rent industrial spaces, not storefronts. The chief executive and chief financial officer share hotel rooms on the road. The founder, Bob Kierlin, still visits headquarters several times weekly in suits purchased for sixty dollars. This austerity is not performative; it is load-bearing. It allows a Fastenal branch to break even on two hundred thousand dollars in monthly revenue while competitors, burdened by higher real estate costs and corporate overhead, require significantly more volume to justify their presence. The result is geographic density in markets competitors cede by default. Replicating this would require a sustained, decades-long commitment to suppressing per-unit economics in favor of market coverage: trade-off that conflicts with the growth metrics and margin expectations that govern most publicly traded industrial distributors.
The frugality extends to labor. Ninety-five percent of branch managers and above, including the entire executive team, are internal promotions. This is not merely a human-resources preference. It is an economic imperative that preserves the entrepreneurial autonomy essential to the model. Fastenal’s branches operate as independent profit centers with no standardized playbook. A manager in rural Wisconsin might choose to emphasize metalworking tools to serve the local paper mill, while a branch in Texas focuses on safety equipment for oilfield services. This adaptability allows the company to capture premium pricing through local expertise, but it requires employees who understand the specific industrial ecology of their territory rather than executives enforcing national standardization.
The Discipline of Failure
Fastenal’s growth is constrained by a statistical reality that would terrify most sales organizations: seventy-two percent of new accounts generate no business within five years, and only two percent ever become financially meaningful. This is not a failure of execution but a defining structural feature of the business. The company sells into industrial environments where procurement relationships take years to mature. A new manufacturing plant might take three years to reach production volume sufficient to justify an Onsite. During that gestation period, Fastenal funds inventory and dedicates personnel with no guarantee of return.
This dynamic imposes a brutal capital discipline. Because the company cannot buy growth, because most new relationships will fail, it must remove unprofitable customers and underperforming vending machines with the same aggression it applies to acquisition. An Onsite that fails to reach spend thresholds is shuttered; a vending machine that dispenses insufficient volume is pulled. This culling protects the twenty percent EBIT margin that serves as an internal key performance indicator, but it creates a persistent tension between growth and margin integrity. The company has closed forty percent of its traditional branches over the past decade even as it expanded its Onsite network, accepting lower absolute revenue per location in exchange for relationship depth.

The two-percent rule shapes every strategic decision. It forces Fastenal to decline business that might dilute margins even if it would boost top-line growth. It requires patience with capital allocation that quarterly-earnings-oriented competitors cannot afford. And it ensures that the company’s expansion remains tethered to actual customer demand rather than speculative market entry. When Fastenal opens an Onsite, it is betting that the specific customer will grow into the relationship: wager that fails more often than it succeeds, but which, when successful, generates returns that compensate for the losses.
Embedding Without Contracts
The Onsite model represents the logical extension of Fastenal’s economic engine: total physical and operational integration into the customer’s business. With two thousand Onsites generating an average of one hundred thousand dollars per month, half the revenue of a traditional branch but with deeper penetration, the company has effectively become the procurement department for major industrial and technology manufacturers. The relationship is intimate. Fastenal employees attend production planning meetings, monitor consumption patterns, and manage the complex taxonomy of indirect materials that manufacturing engineers prefer not to contemplate.
Yet this embedding occurs without contractual protection. Fastenal maintains no formal agreements that lock customers into multi-year commitments. A national account such as Amazon, which accounts for a low single-digit percentage of revenue but remains a material concentration, could theoretically develop in-house supply chain capabilities or shift to a competitor with minimal notice. The switching costs are operational, not legal. They derive from the data Fastenal accumulates about consumption patterns, the inventory it holds on-site, and the procurement hours it has eliminated from the customer’s organization. Should a customer choose to internalize these functions, Fastenal’s dedicated employees and on-site inventory become stranded assets.
This fragility is amplified by the capital intensity of the model. Each Onsite requires upfront investment in inventory and dedicated labor. If a customer’s business contracts, whether through recession, automation reducing labor and supply needs, or strategic consolidation, the Onsite may never reach the minimum spend threshold required for profitability. With seventy-two percent of new accounts failing to generate material business, the capital deployed to Onsites carries a high failure rate. The model works only if the winners generate sufficient returns to offset the losers, a dynamic that requires continuous growth in customer output to ensure that enough Onsites mature into profitable relationships.
The National-Local Tension
Serving national accounts, who comprise half of revenue, while maintaining branch-level entrepreneurialism creates a structural tension that Fastenal manages through deliberate inconsistency. A national manufacturer such as a major automotive or aerospace firm requires standardized service across dozens of locations, approved supplier lists, and centralized billing. Fastenal satisfies these requirements through its national account infrastructure. Simultaneously, it empowers individual branch managers to run independent profit-and-loss statements, negotiate local pricing, and adapt product mixes to regional industrial bases.
This hybrid approach risks service degradation. A branch manager in Ohio might prioritize a local machine shop over the national directives of a coastal manufacturing conglomerate, creating friction in the account relationship. Conversely, excessive standardization would destroy the local expertise that justifies Fastenal’s premium pricing. The company resolves this not through policy but through culture. The internal promotion ladder, ninety-five percent of leadership rises from within, ensures that regional managers possess the operational intuition to balance national compliance with local opportunity. They understand that the premium Fastenal commands depends on solving specific problems, a unique fastener specification for a local wind turbine manufacturer, a safety protocol for a regional chemical plant, that no national contract could anticipate.
The Price of Availability
The entire edifice rests on a fragile assumption: that industrial customers will continue to value supply chain optimization and immediate availability over the lowest possible unit price. Fastenal’s twenty percent EBIT margin is defensible only so long as customers accept that the elimination of procurement labor, inventory carrying costs, and waste is worth paying two to three times the margin of a traditional distributor. This assumption faces pressure from multiple vectors. Amazon Business and other digital platforms offer price transparency and rapid delivery that challenge Fastenal’s value proposition for standardized items. Local distributors with lower cost structures, unburdened by Fastenal’s balance sheet intensity, can undercut on price for customers willing to manage their own procurement.
The bear case for Fastenal is not that it will be disrupted by technology, but that it will be commoditized by price competition. If customers begin to view fasteners and maintenance supplies as undifferentiated commodities to be sourced at lowest cost, Fastenal’s margin compresses toward the industry mean. The company’s defense is the depth of its operational integration: he data from RFID-enabled bins, the dedicated Onsite employees, the years of consumption history that make switching costly. But these switching costs depend on the customer continuing to value the service layer. Should economic pressure force manufacturers to prioritize cash conservation over procurement efficiency, Fastenal’s inventory financing model transforms from a convenience into an expensive luxury.
Culture as Balance Sheet
The economic variables that determine Fastenal’s future are not merely financial. They are cultural. The company’s ability to maintain frugal operations in small markets, to cull unprofitable customers without sentiment, and to preserve entrepreneurial autonomy at scale depends on a governance structure that treats leadership continuity as a capital asset. Bob Kierlin, who founded the company in a small Minnesota town in 1967, still writes internal memos and maintains an office at headquarters. The executive team shares hotel rooms and measures success by branch-level profitability rather than aggregate market share.
This culture functions as an operating lever with direct financial consequences. If new management were to prioritize growth over margin discipline, the frugal cost structure would erode. Branches would migrate to higher-rent locations to chase prestige accounts. Onsites would be retained despite poor economics to preserve customer relationships. The internal promotion ladder would give way to external hires from larger distributors, importing bureaucratic processes that destroy local adaptability. Each of these shifts would increase the minimum viable market size, forcing Fastenal to abandon the small-town geography that generates half its revenue and provides the foundation for its returns.
The culture also protects against the temptation to reduce inventory holdings to free working capital for faster growth. Fastenal could improve its cash conversion cycle by shifting inventory risk back to customers through consignment arrangements or vendor-managed inventory programs. Doing so would liberate capital for expansion, but it would simultaneously reduce switching costs and erode the relationship depth that justifies premium pricing. Only a management team acculturated to patience, and immunized against the pressure to maximize short-term capital efficiency, would decline such an opportunity.
The Follower’s Gambit
Fastenal’s international expansion, now seventeen percent of revenue, exposes the limits of its model. The company entered Europe and Asia not by identifying underserved local markets, but by following existing customers such as Amazon into foreign territories. This strategy avoids the market development risk of entering unknown geographies, but it creates a different vulnerability. In these markets, Fastenal faces no equivalent competitor; there is no local distributor with the same inventory-financing model to acquire or learn from. The company must build infrastructure from scratch, leasing space, hiring local talent, funding inventory, without the demographic density of American industrial towns to support the frugal branch economics.
If these international customers develop local supply chain partnerships or if European and Asian competitors emerge with lower cost structures, Fastenal’s capital investment becomes stranded. The follow strategy works only if the customers themselves grow sufficiently to justify the infrastructure, and if they remain committed to Fastenal’s service model rather than adapting to local procurement norms. Unlike in the United States, where fifty years of density creation provides a defensive moat, Fastenal’s international position remains provisional. It is building supply chains in markets where it has not yet proven that the small-market, high-service model can replicate the returns of its domestic operations.
The company has indicated a long-term target of fifteen thousand Onsite locations, a sevenfold increase from current levels. Achieving this while maintaining thirty percent returns on capital requires that the two-percent success rate holds, that customers continue to pay for availability, and that the culture of austerity survives leadership transition. Fastenal’s future is not determined by the demand for fasteners, which will persist, but by the durability of the economic friction, between manufacturers’ need for immediate supply and their inability to manage it efficiently, that has allowed a nuts-and-bolts business to generate software-like returns.
The Onsite employee represents the most concentrated form of Fastenal’s capital deployment, yet this capital walks out the door each evening without a non-compete clause binding it to the balance sheet. When Fastenal places an employee inside a customer’s facility, typically a “Site Manager” or “Onsite Specialist”, it commits roughly $75,000 to $100,000 in annual compensation, plus the carrying cost of inventory valued between $50,000 and $200,000 depending on the complexity of the operation. This employee does not merely deliver goods; they attend daily production meetings, monitor kanban systems, adjust safety stock levels based on seasonal demand, and essentially function as an outsourced procurement officer embedded within the customer’s organizational chart. The economic bet is that this human presence creates sufficient operational friction, ersonal relationships, tacit knowledge of the customer’s production schedules, familiarity with the specific torque requirements of a particular assembly line, hat the customer will not disintermediate Fastenal even when competitor pricing undercuts by five or ten percent.
Yet this is precisely where the model’s fragility concentrates. Unlike a vending machine or a software license, the Onsite employee can be hired away by the customer. In fact, the career path often follows exactly this trajectory: a Fastenal Site Manager spends three years learning the nuances of a customer’s operation, developing relationships with plant managers and maintenance supervisors, and then receives an offer to join the customer’s internal supply chain team at a higher salary plus equity. Fastenal has no contractual mechanism to prevent this; the employment relationship remains at-will, and the customer’s plant is the Site Manager’s workplace. When this occurs, Fastenal loses not merely the revenue stream but the institutional knowledge embedded in that individual: he specific cadence of a customer’s maintenance cycles, the informal workaround for a legacy ERP system, the political dynamics between engineering and purchasing departments. A competitor can then hire this same individual, acquiring the relationship map that took Fastenal years to chart.
The company mitigates this through cultural conditioning rather than legal constraint. Site Managers are promoted from within the branch system, individuals who have already absorbed the frugal ethos and who view the Onsite role not as a stepping stone to corporate procurement but as the culmination of a career in industrial distribution. They are compensated on branch-like P&L metrics, incentivized to grow the account’s spend rather than to optimize their own salary. Yet as the company scales toward its target of fifteen thousand Onsites, the talent pool thins. The individual who thrives managing inventory for a rural agricultural equipment manufacturer may lack the sophistication for a high-tech semiconductor fabrication facility. The cultural filter that selects for entrepreneurial patience becomes harder to maintain at scale, and the risk of talent arbitrage, where Fastenal trains the personnel that its customers eventually poach, intensifies.
The Consumption Data as Collateral
Beneath the human layer lies a technological infrastructure that Fastenal has constructed specifically to make the relationship sticky beyond the tenure of any individual employee. The FAST Bin system, industrial storage units equipped with RFID tags and Bluetooth sensors, monitors consumption in real time, transmitting data to Fastenal’s replenishment algorithms without human intervention. When a maintenance technician removes a safety glove or a specific grade of bolt, the bin detects the weight change or RFID exit and triggers an automatic reorder. This is not merely a convenience; it is a form of data lock-in that rivals the contractual obligations Fastenal explicitly avoids.
The proprietary nature of this infrastructure derives from Fastenal’s vertical integration into vending machine manufacturing. Unlike competitors who purchase dispensing equipment from third parties, Fastenal acquired its supplier, allowing it to customize hardware specifically for industrial environments, amp manufacturing floors, dusty construction sites, high-security clean rooms. The machines communicate consumption patterns that create a dataset no competitor possesses: granular visibility into which SKUs move at what velocity during specific production cycles, seasonal variations in maintenance activity, and correlation between output levels and consumable usage. A competitor could undercut Fastenal’s pricing on individual fasteners, but they cannot replicate the predictive replenishment cadence optimized through years of customer-specific data.

This creates a switching cost that is technical rather than legal. To displace Fastenal, a competitor must not only match pricing but convince the customer to abandon a replenishment system that has eliminated stockouts and reduced working capital requirements. The customer would need to rebuild inventory buffers, retrain employees on manual reordering processes, and absorb the administrative burden that Fastenal’s automation has eliminated. The data, in this sense, functions as collateral securing the economic relationship.
However, this technological moat depends on continued investment in integration at a pace that matches customer IT evolution. As industrial facilities upgrade to IoT-enabled enterprise resource planning systems, as RFID standards shift from passive to active tags, as cybersecurity requirements tighten around networked devices, Fastenal must perpetually reinvest in its hardware and software infrastructure. A failure to keep pace, if competitors develop cloud-native replenishment systems while Fastenal’s vending machines remain dependent on legacy communication protocols, transforms the data advantage into a technical debt liability. The customer remains locked in not to a superior system, but to an obsolete one, creating the conditions for a disruptive displacement when the technical gap becomes too wide to ignore.
The Margin Erosion Scenario
To stress-test Fastenal’s economic engine, consider a scenario where the twenty percent EBIT margin, the internal benchmark maintained across branches, Onsites, and automated replenishment channels, begins to compress toward the industry mean of six to eight percent. This compression would not require technological disruption or managerial failure. It would require only a shift in customer procurement priorities from total cost of ownership to unit price minimization, a shift that typically accompanies industrial recession or sector consolidation.
Imagine a regional construction conglomerate, historically a Fastenal Onsite customer, facing liquidity constraints after a cyclical downturn in commercial real estate. The CFO mandates a fifteen percent reduction in indirect procurement spending. The plant manager, who values the Fastenal relationship, is overruled by procurement officers tasked with demonstrating immediate cost savings. They benchmark Fastenal’s pricing against Amazon Business and a consortium of local distributors, discovering that certain commodity fasteners and safety gloves are available at twenty percent lower unit cost, albeit with longer lead times and minimum order quantities.
In this scenario, Fastenal faces an asymmetric choice. It can reduce pricing to match competitors, sacrificing the margin that funds its frugal branch network and Onsite infrastructure. Or it can maintain pricing, accepting the loss of the account and the stranded inventory and personnel that accompany it. The company’s historical response has been the latter: active culling of unprofitable relationships. But at scale, with two thousand Onsites and forty percent of revenue dependent on deeply embedded relationships, the option to walk away becomes constrained. The stranded assets, dedicated employees, customer-specific inventory, FAST Bins integrated into production lines, represent sunk costs that create pressure to discount rather than abandon.
If this dynamic repeats across multiple accounts simultaneously, if a recession triggers broad-based procurement austerity, Fastenal’s margin discipline faces its most severe test. The company could find itself trapped between maintaining its twenty percent target and accepting volume declines that underutilize its fixed cost base. The frugal cost structure that enables small-market profitability becomes a prison if revenue falls below the threshold required to cover even those minimal expenses. Unlike a technology company with zero marginal cost of goods sold, Fastenal cannot scale down incrementally; each branch and Onsite carries a fixed cost floor below which operations become irrational.
The bear case intensifies when considering the alternative financing models competitors might deploy. A regional distributor could offer consignment inventory, holding stock on the customer’s premises without charging until consumption occurs, without requiring the dedicated employee presence that drives Fastenal’s cost structure. This would replicate Fastenal’s working capital benefit while avoiding the labor cost premium. Or a large e-commerce platform could offer dynamic discounting algorithms that optimize pricing across thousands of SKUs in real-time, undercutting Fastenal’s standardized markup on commodity items while capturing margin only on specialty fasteners. Fastenal’s defense against these models, the operational integration and data lock-in, erodes if customers cease to value these services sufficiently to pay the premium.
The Capital Velocity Constraint
Fastenal’s growth is ultimately constrained by the velocity of its own balance sheet. Each new Onsite requires approximately $150,000 to $300,000 in working capital deployment, split between inventory and the initial operating losses incurred before the account reaches spend thresholds. With a stated target of fifteen thousand Onsites, more than seven times the current footprint, the implied capital requirement approaches $2.25 billion to $4.5 billion in incremental working capital alone, excluding the fixed asset investments in branch networks required to support these remote operations.
This capital intensity creates a natural governor on growth that protects the business from overextension but also limits optionality. Unlike a software company that can serve infinite additional customers with minimal incremental capital, Fastenal must choose each year which Onsites to fund, which branches to open, and which international markets to penetrate. The discipline of allocating capital to only the two percent of accounts that will become meaningful, while withdrawing it from the seventy-two percent that fail, requires a forecasting accuracy that becomes harder to maintain as the company moves into unfamiliar industries and geographies.
The constraint becomes acute in international markets, where Fastenal cannot rely on the demographic density of American industrial towns to generate the branch-level economics that subsidize Onsite experimentation. In Europe or Asia, establishing the infrastructure to support a single Onsite may require capital commitments an order of magnitude larger than in the United States, given the lack of existing branch networks to provide logistical support. If the customer being followed into these markets, say, an American technology manufacturer building facilities in Southeast Asia, delays production ramp-up or modifies its supply chain strategy, Fastenal faces the choice of funding unprofitable operations longer than the American model tolerates, or withdrawing and forfeiting the market position.

Moreover, the working capital model depends on Fastenal’s cost of capital remaining below the implicit interest rate customers would pay to finance their own inventory. If rising interest rates increase Fastenal’s borrowing costs, or if customers develop access to cheaper financing through asset-backed lending or supply chain finance programs, the economic rationale for Fastenal’s inventory-holding service weakens. The company would need to either absorb higher carrying costs, compressing margin, or pass them to customers through higher pricing, accelerating the shift toward self-managed procurement.
The Cultural Succession Problem
Bob Kierlin’s continued presence, writing memos, visiting branches, modeling the $60 suit, functions as a governance mechanism more reliable than any board committee. It signals to branch managers and Site Managers alike that the frugal, patient, relationship-oriented approach is not merely a historical artifact but a continuing requirement for advancement. Yet Kierlin is in his eighth decade, and the leadership pipeline, while deep with internal promotions, faces the inevitable dilution that accompanies scale.
The risk is not that new management will consciously abandon the model, but that they will optimize it. A new CEO, facing investor pressure to accelerate growth toward the fifteen-thousand-Onsite target, might relax the culling discipline, allowing marginal accounts to persist longer in hopes that they eventually mature. This would boost short-term revenue and employee morale, no Site Manager enjoys shuttering an operation they built, but would erode the margin that funds the entire system. Alternatively, management might seek to “leverage” the balance sheet by reducing inventory holdings, pushing consignment models that shift risk back to customers while retaining the service revenue. This would improve return on capital in the short term but would eliminate the switching costs that make the model defensible.
The cultural variable also affects talent retention at the branch level. As the company grows, the path from branch employee to manager lengthens. The individual who joined Fastenal expecting to run their own P&L within five years may face a decade-long apprenticeship as the pyramid narrows at the top. If compensation structures fail to retain these individuals, if the stock options and profit-sharing that historically substituted for high base salaries become less attractive as the company matures, Fastenal loses the entrepreneurial personnel who make the decentralized model function.
The Commoditization Pressure Point
The most acute threat to Fastenal’s model may come not from competitors replicating its service, but from customers internalizing its value proposition. As manufacturing firms invest in their own supply chain digitization, implementing AI-driven procurement systems, IoT-enabled inventory management, and direct supplier marketplaces, they may discover that the friction Fastenal eliminates can be eliminated internally at lower total cost. A large national account, having observed Fastenal’s Onsite operations for a decade, might reverse-engineer the model: hire the Site Manager away, purchase vending machines from the open market, and negotiate directly with fastener manufacturers.
Fastenal’s defense against this internalization is the fragmentation of its supply base. The company sources from thousands of small manufacturers, aggregating their output into the coherent offering that customers value. A single manufacturer cannot easily replicate this breadth; a customer cannot efficiently manage relationships with nine hundred fastener suppliers. Yet if consolidation occurs in Fastenal’s supply base, if large industrial conglomerates acquire the niche manufacturers that produce specialized fasteners, the aggregation function becomes less valuable. The customer could then deal directly with a consolidated supplier base, using Fastenal’s historical purchasing data, which the customer owns, to negotiate direct relationships.
This dynamic is already visible in certain product categories. As safety equipment and janitorial supplies, now representing significant revenue shares, become standardized and subject to corporate purchasing mandates, Fastenal faces procurement departments armed with reverse auction platforms and benchmark pricing data. The local relationship that justified premium pricing in the branch model carries less weight when the national procurement office in Chicago mandates supplier selection based on total contract value. Fastenal’s response, deploying national account managers to match the customer’s organizational altitude, requires a different skill set than the branch entrepreneurship that built the company, and a different cost structure that may not sustain the twenty percent margin.
The model persists, for now, because the fragmentation of industrial supply chains is structural, not cyclical. Manufacturing requires too many specific variations of too many components for any single customer to optimize procurement internally across all categories. Fastenal’s value lies not in owning the manufacturing, but in bearing the complexity cost that customers cannot economically internalize. Yet this value proposition assumes a stable equilibrium in the division of labor between manufacturer and distributor. Should that equilibrium shift, hould additive manufacturing reduce fastener variety, should modular construction standardize building components, should AI procurement agents reduce the search costs of managing multiple suppliers, astenal’s inventory bank becomes a stranded asset, holding stock of items that customers no longer need in the volumes or varieties that justified the balance sheet intensity.