Goosehead Insurance: How Market Share Survives Catastrophe
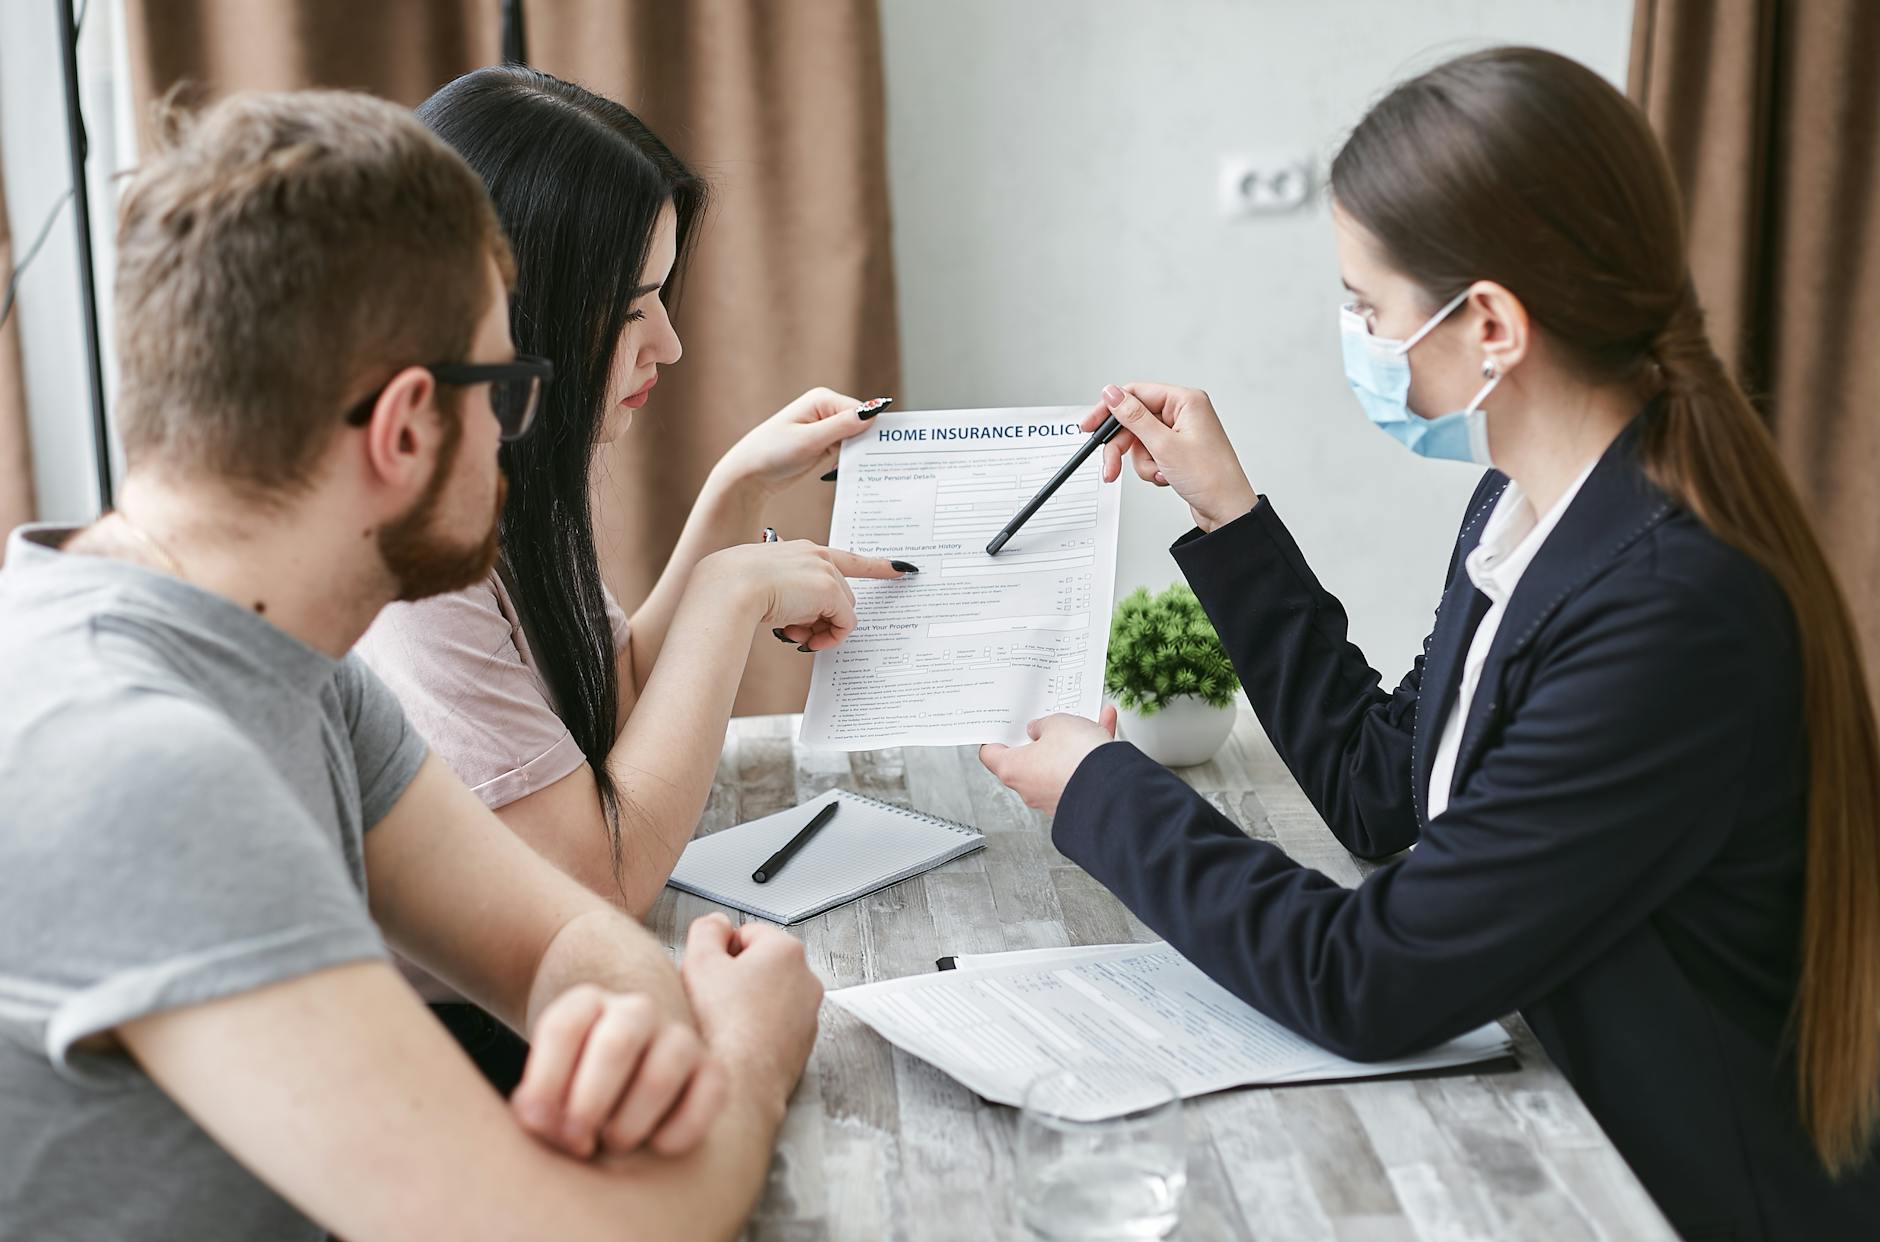
In the spring of 2023, fifteen severe storms tore through Texas, inflicting twenty to fifty billion dollars in damage. For Goosehead Insurance, the largest independent agency in the state with an eighteen percent market share, this was not merely a weather event. It was a stress test of the entire economic architecture. Carriers, reeling from losses, restricted underwriting capacity. Product availability constricted. Suddenly, the agents who had built their practice on offering choice among two hundred carriers found themselves with fewer viable options. Referral partners, mortgage loan officers and real estate agents who had been feeding Goosehead eighty percent of its new business, began to lose confidence. If Goosehead could not deliver competitive quotes quickly, clients defected to captive carriers, and the delicate web of unpaid loyalty began to fray.
This moment revealed the essential fragility of a model that otherwise appears invincible. Goosehead had grown revenue twenty-nine percent year-over-year while expanding EBITDA margins from fourteen percent to thirty-two percent between 2021 and 2024. It had achieved productivity metrics that dwarf industry benchmarks, orporate agents producing at 2.8 times standard rates, franchise veterans at 1.9 times. Yet all of this performance rests upon a single, unsettled question: whether mortgage professionals will continue to prioritize the speed and affordability of Goosehead’s service over the immediate economic gratification of selling leads to the highest bidder.
The Alchemy of Unpaid Distribution
Goosehead operates as a high-velocity intermediary in the home purchase transaction, capturing fourteen percent commission on new business and twelve percent on renewals while bearing zero underwriting risk. This is not, in itself, unique. The insurance brokerage model has existed for centuries. What distinguishes Goosehead is the source of its velocity: a referral network of loan officers and real estate agents who receive no direct payment for sending clients Goosehead’s way.
Eighty percent of new business flows through these unpaid channels. The remaining twenty percent arrives through client referrals: ratio that inverts the traditional independent agency model, where word-of-mouth typically dominates. This dependency creates a peculiar power dynamic. The referral partners control the spigot, yet they have no contractual obligation to Goosehead. They direct homebuyers to the company not because of financial incentives but because Goosehead solves specific, acute problems: delivering insurance binders within one hour and offering access to two hundred carriers when competitors present only three or four. In a transaction where missing a closing date costs thousands and emotional stakes run high, speed and choice become currencies more valuable than cash.
The model generates a self-reinforcing cycle that resembles a distribution monopoly built on gratitude rather than contracts. Referral partners send volume to Goosehead because the service quality protects their own relationships with homebuyers. High lead flow allows Goosehead agents to specialize and increase productivity. Superior productivity funds the centralized service infrastructure that maintains the one-hour binder standard. Better service deepens referral partner loyalty, which increases lead flow further. Competitors attempting to replicate this network face a cold-start problem: without the volume, they cannot justify the service infrastructure; without the infrastructure, they cannot win the referral partners.
Yet this architecture contains a structural constraint that shapes every strategic decision. Because the referral partners are unpaid and uncontracted, they remain economically promiscuous. They can switch allegiance instantly if a competitor offers direct payments, if captive carriers improve their product availability, or if Goosehead’s service quality slips during scaling. The company does not own its distribution; it rents it daily through performance. This creates a permanent operating imperative: the service advantage must remain not just superior but visibly, dramatically superior to any alternative that might offer financial inducements to the referral partners.
The Separation That Multiplies
Beneath the referral network lies a less visible but equally decisive structural advantage: the rigid separation of sales and service functions. In traditional agencies, agents handle both prospecting and policy maintenance, forcing a choice between hunting and farming that usually results in mediocre performance at both. Goosehead’s corporate and franchise agents focus exclusively on sales, quoting, binding, and closing, while a centralized service team manages renewals, claims, and ongoing client maintenance.
This separation allows Goosehead to hire young, sales-focused talent that might struggle in the hybrid role required by traditional shops. The results are stark. Corporate agents achieve productivity 2.8 times industry benchmarks; experienced franchise producers hit 1.9 times. These are not marginal improvements but categorical differences that compound over time. A producer focused solely on sales can process more transactions, develop deeper expertise in carrier appetites, and maintain the velocity required to satisfy referral partners’ expectations.
The durability of this advantage stems from operational embedding. Reconfiguring a traditional agency to match this model would require rebuilding compensation structures, retraining staff, and surrendering short-term revenue during the transition, rganizational trauma that most agencies cannot survive. Goosehead’s centralized service team also achieves economies of scale in claims advocacy and renewal processing that distributed models cannot match, driving the company’s ninety-eight percent premium retention rate despite industry volatility.
However, this separation creates its own tension. Because agents never handle renewals, they lack ongoing relationships with clients. The business depends entirely on the initial transaction and the centralized team’s ability to maintain loyalty. If the service team fails, if claims handling frustrates clients or if renewal shopping reveals better rates elsewhere, the retention advantage evaporates, and the high-cost acquisition model becomes economically unsustainable. The productivity gains of specialization assume that retention remains mechanically high; the model works only if the back office performs flawlessly while the front office sells aggressively.
The Mathematics of Franchise Discipline
Goosehead’s scaling mechanism relies on a franchise system that converts distribution growth from a capital-intensive real estate play into a variable-cost recruitment exercise. As of late 2024, the company operates eleven hundred franchises employing twenty-one hundred producers, having shifted emphasis away from the corporate agent force that peaked at five hundred in 2022. The economics are attractive: franchises retain the majority of new commissions and half of renewal commissions, while Goosehead captures twenty percent of new business and fifty percent of renewals without bearing the fixed costs of agent employment.

The capital efficiency is remarkable. Between 2022 and 2024, average producers per franchise increased from 1.5 to 1.9. Management has calculated that adding a producer to an existing high-performing franchise generates value equivalent to launching nearly two new franchises, because established operations possess lead flow, referral partner relationships, and operational momentum that new entrants lack. Franchise new business productivity rose forty-nine percent in 2024 despite only seven percent growth in total franchise producers: clear signal that density, not just scale, drives returns.
Yet franchises are independent business owners with misaligned incentives. A franchisee optimizing for personal profitability might cut service corners, delay binder delivery, or mishandle a high-stakes closing in ways that damage Goosehead’s brand and alienate referral partners. Because the referral network is shared, one bad experience with a franchise agent can poison a loan officer’s perception of the entire system, quality control becomes a systemic risk rather than a localized issue.
The company’s response to this tension between scale and quality reveals leadership functioning as a hard economic variable rather than a soft cultural asset. Between 2022 and 2024, Goosehead culled more than three hundred underperforming franchises and reduced corporate agent headcount from five hundred to a low of two hundred seventy-five before selectively ramping again. This was not gentle pruning but surgical removal of capacity that failed to meet productivity or service standards. The housing market contracted during this period, existing home sales dropped from 5.5 million to roughly four million annually, yet Goosehead expanded margins from fourteen percent to thirty-two percent EBITDA while maintaining twenty-nine percent revenue growth.
This operational ruthlessness, treating underperforming agents and franchises as economic liabilities to be eliminated rather than relationships to be nurtured, directly drove the margin expansion. It also demonstrates the governance required to maintain the unpaid referral model. Referral partners tolerate Goosehead’s dominance only because the quality remains consistently high. The culling was a capital reallocation decision: removing low-productivity distribution to protect the high-productivity core that sustains the referral network’s confidence.
The Assumption of Permanent Superiority
All of this performance rests upon a fragile long-term assumption: that referral partners will indefinitely prioritize client affordability and closing speed over direct financial compensation from insurance carriers. The model assumes that loan officers and real estate agents will continue to view Goosehead’s one-hour binders and two-hundred-carrier choice as superior to whatever captive carriers or competing independents might offer, including cash payments for leads.
This assumption faces pressure from multiple directions. Captive carriers, state Farm, Allstate, Farmers, are investing heavily in digital quoting platforms that compress their own binder times. As these carriers improve their product availability and service velocity, the gap between Goosehead’s offering and the captive alternative narrows. Simultaneously, competitors are emerging who recognize the value of the home purchase moment and are willing to pay referral partners directly for lead flow, converting Goosehead’s unpaid advantage into a paid auction.
The 2023 Texas storms illustrated how quickly the assumption can crack. When severe weather losses forced carriers to restrict underwriting capacity, Goosehead could not offer competitive quotes in its largest market. Referral partners, facing angry clients who could not close without insurance, began routing business elsewhere. The ninety-eight percent premium retention rate and eighty-four percent client retention, metrics that make the renewal economics so attractive, depend entirely on product availability. When carriers constrict, retention plummets, and the compounding value of the renewal book evaporates.
Geographic concentration amplifies this risk. Texas represents eighteen percent of Goosehead’s market share and serves as the proving ground for its model. The company has begun diversifying, opening an Arizona office in late 2024, but insurance regulation and carrier appetite vary by state. A regulatory decision in Texas or a carrier exit from the state market would inflict damage disproportionate to the national footprint. The unpaid referral model works only when the product works; when carriers retreat, the economic engine seizes.
The Rule of 60 and the Hard Ceiling
Goosehead management targets what they term the “Rule of 60”, ustaining twenty percent revenue growth and forty percent EBITDA margins indefinitely. With less than one percent national market share and only five percent penetration of the home purchase channel, this ambition seems mathematically achievable. The market is vast, and Goosehead’s current share is minuscule.
Yet structural constraints complicate the path. The home purchase channel itself is finite, cyclical, and currently depressed. Existing home sales have contracted significantly from their 2021 peaks, and while Goosehead has offset volume declines by increasing market share of transactions, there are limits to how much share one company can capture before triggering regulatory scrutiny or carrier pushback. Insurance regulators tend to view dominant distribution channels with suspicion, and carriers may resist ceding too much volume to a single intermediary that could one day dictate terms.
Expanding beyond the home purchase channel into auto, umbrella, or life insurance, the typical adjacency play for property-casualty agencies, requires different capabilities. Auto insurance, for instance, demands integration with DMV databases and different quoting workflows; life insurance requires medical underwriting expertise and a sales process measured in weeks rather than hours. Goosehead’s productivity advantages and referral partner relationships are specific to the transactional velocity of home purchases. Attempting to replicate them in slower, more complex product lines may result in merely average performance, eroding the capital efficiency that justifies the current valuation.
The franchise model itself may face scaling limits. While adding producers to existing high-performing franchises creates value, eventually the referral partner relationships in a given territory saturate. A franchise in Dallas cannot indefinitely absorb new producers if the local loan officer network has finite referral volume. At some point, growth requires new franchise territories, which lack the density advantages of mature markets and may drag down system-wide productivity metrics.
The Weather Variable
Goosehead’s story is ultimately one of contingent mastery: business that has optimized every variable within its control while remaining hostage to several outside it. The company has built a machine that converts the anxiety of homebuying into a self-reinforcing distribution advantage, achieving productivity and retention metrics that seem to defy the industry’s gravity. It has demonstrated that operational discipline, expressed through the ruthless culling of underperformers, can drive margin expansion even during housing contractions.
Yet the model remains exposed to the weather, both literal and metaphorical. When storms devastated Texas, they revealed that Goosehead’s control ends at the carrier’s underwriting appetite. When referral partners face a choice between unpaid loyalty and paid alternatives, the company’s advantage depends on their continued preference for service over revenue: preference that economic theory suggests should erode over time as the market matures and competitors learn to match Goosehead’s speed.
The business will continue to grow, likely at impressive rates, as long as the home purchase channel remains active and carriers remain willing to write business through its platform. But it operates in a narrow margin of error. A sustained period of product unavailability, a systematic campaign by carriers to buy referral partner loyalty directly, or a quality control failure at scale could unwind the network effects that currently protect its economics. The unpaid referral partner remains the keystone; remove that stone, and the arch collapses, regardless of how efficiently the stones beneath it have been arranged.
The unpaid referral partner remains the keystone; remove that stone, and the arch collapses, regardless of how efficiently the stones beneath it have been arranged.
The Data Bargain
Beneath the surface of agent productivity and referral relationships lies a quieter negotiation over who owns the client intelligence. Goosehead has invested heavily in proprietary technology: digital agent that matches coverage to clients using only three data points in under two minutes, a comparative rater that aggregates pricing across two hundred carriers, and a quote-to-issue platform that binds policies without leaving the Goosehead ecosystem. These tools generate a valuable secondary asset: tens of millions of quote records, behavioral patterns, and pricing elasticity data that reveal exactly how consumers shop for insurance during the emotional pressure of a home purchase.
This data repository represents a latent competitive advantage, feeding machine learning models that theoretically improve conversion rates and carrier matching over time. Yet the durability of this technological moat depends on a fragile détente with the carriers themselves. As Goosehead grows, now writing $3.8 billion in premiums, it accumulates information that carriers desperately want but cannot legally obtain directly. Carriers know their own pricing, but they do not know, with granular precision, how their quotes compare to competitors in real time across thousands of micro-markets, or which coverage configurations consumers actually select when presented with choice.
The tension emerges as carriers modernize their own distribution technology. Progressive, Geico, and the major mutuals are building direct-to-consumer platforms that bypass agencies entirely. Meanwhile, the standard carriers that rely on Goosehead, regional specialists, surplus lines writers, and mid-tier national firms, increasingly demand API integration that grants them real-time access to Goosehead’s quote flow. They want to see the competitive landscape as Goosehead sees it, to adjust pricing algorithms dynamically. In exchange, they offer preferred capacity commitments or bonus commission structures.
This creates a strategic prisoner’s dilemma. If Goosehead shares its data to secure carrier capacity, particularly in constrained markets like post-storm Texas, it trains the algorithms that will eventually disintermediate its own value proposition. A carrier that knows precisely how to price against two hundred competitors no longer needs an intermediary to explain market positioning; they can go direct to the consumer or offer referral partners their own comparative tools. Conversely, if Goosehead refuses data sharing, carriers may restrict capacity, lengthen approval times, or favor competing agencies that operate as transparent conduits. The technology advantage persists only if it remains proprietary while the carriers remain dependent. Once carriers achieve technical parity, or worse, gain access to Goosehead’s accumulated intelligence, the comparative rater becomes a commodity and the digital agent merely a skin on top of carrier APIs.
The Maturation Problem
The franchise model that enables capital-efficient scaling contains a temporal bomb that ticks silently during the first three years of operation and grows audible thereafter. A new franchisee enters the system motivated by the promise of entrepreneurship: build a book of business, serve clients, and eventually enjoy the passive income of renewal commissions. The economics are compelling at the outset, oosehead provides the referral relationships, the technology, the brand recognition, and the centralized service infrastructure, taking twenty percent of new business commissions and fifty percent of renewals in exchange.
But as a franchise matures, the value equation inverts. Consider a producer who has built a $3 million premium book over five years. At renewal, that book generates approximately $360,000 in commissions (assuming twelve percent). Goosehead takes half, $180,000, for providing technology and brand support that the franchisee now barely notices, while the franchisee handles the local referral partner relationships personally. The loan officers send business to the producer, not to the Goosehead brand. The franchisee begins to calculate: if they went independent, they could capture that full $360,000, minus perhaps $50,000 in overhead for their own comparative rater and service staff. The $130,000 annual difference funds considerable independence.
This mathematical reality drove the 2022-2024 culling, but not entirely. While Goosehead removed three hundred underperforming franchises, those who failed to meet productivity minimums, the more insidious risk comes from the high-performing franchisee who achieves escape velocity. A top producer in Dallas or Houston, handling forty new transactions monthly with a mature renewal book, reaches a scale where the corporate infrastructure becomes a tax rather than a service. If such a franchisee defects, they do not merely reduce Goosehead’s revenue; they take their referral partner relationships with them, potentially poaching loan officers and real estate agents to a new independent shop or a competing network.
The quality control issues that triggered the recent culling stem partly from this maturation pressure. Franchisees facing the temptation to defect often cut service quality to boost short-term cash flow, reducing staff or delaying binder submissions to scrape margin before an exit. One mishandled closing, a binder promised within one hour that arrives in four, causing a delay in funding, can poison a loan officer’s relationship with that franchisee and, by extension, with Goosehead. The centralized service team mitigates this, but the new business transaction remains the franchisee’s domain. When the economic alignment between corporate and franchisee frays, the referral partner network bears the cost, and the brand suffers damage that no amount of technology can repair.

The Retention Mirage
The headline numbers, ninety-eight percent premium retention and eighty-four percent client retention, suggest a business of extraordinary stability, an annuity-like stream of recurring revenue that justifies high valuation multiples. Yet the gap between these two figures reveals a more complex and fragile reality. The fourteen-percentage-point difference represents clients who technically remain with Goosehead but do not technically remain loyal. These are the shoppers.
When renewal notices arrive with rate increases, which they inevitably do in an era of climate-driven underwriting losses, these fourteen percent of the base do not quietly accept the new premium. They call the service center demanding re-marketing. They require the comparative rater to run fresh quotes across the two hundred carrier panel. They consume service labor hours, centralized service team capacity that costs real money, to find equivalent coverage at lower prices, often with different carriers. Goosehead retains the premium revenue, but not the client relationship. The client stays because Goosehead shops for them, not because they exhibit genuine brand loyalty.
This distinction matters enormously for the renewal economics. True retention, eighty-four percent, generates passive income with minimal service cost. The “retained” fourteen percent generates active income requiring ongoing labor inputs and technology utilization. In years when carrier capacity is plentiful and rates are stable, this service cost is buried in the operating expense line. But in years like 2023, when Texas carriers restricted underwriting and raised rates by twenty to forty percent following the storm losses, the shopping volume spikes. The centralized service team, designed for efficient maintenance, faces a deluge of re-marketing requests. Service costs per retained dollar escalate, compressing the margin on renewal business precisely when new business volume is already under pressure from the same capacity constraints.
Furthermore, the contingent commissions, the bonus payments carriers make to agencies based on the profitability of their books, depend on this retention mix remaining favorable. When catastrophic losses hit a state like Texas, carriers pay reduced or zero contingent commissions even if premium volume remains flat. Goosehead’s renewal book, while large, is not a fixed annuity; it is an adjustable-rate instrument tied to weather patterns, carrier underwriting cycles, and the service capacity required to maintain the illusion of ninety-eight percent retention. The true economic yield is closer to the eighty-four percent figure, with the remainder representing a high-touch, low-margin service business masquerading as passive recurring revenue.
The Platform Consolidation
The most underappreciated threat to Goosehead’s model does not come from competing insurance agencies or even from carriers building direct channels. It comes from the structural consolidation of the referral partners themselves. The mortgage industry is concentrating rapidly: United Wholesale Mortgage, Rocket Mortgage, and a handful of large banks are capturing increasing shares of origination volume. Real estate agents are aggregating under platform brokerages like eXp Realty and Compass, which provide technology infrastructure and lead management at scale.
In a fragmented market, Goosehead’s model thrives because individual loan officers and agents possess discretion. They can choose to send a client to Goosehead, to a captive carrier, or to a competing independent agency based on personal relationships and recent service quality. As the industry consolidates, however, these individual decisions become algorithmic. A large mortgage platform routing thousands of loans monthly does not rely on loan officer discretion; it builds integrated insurance marketplaces that automatically present three to five options to the borrower at the point of application. The loan officer becomes an interface, not a decision-maker
A large mortgage platform routing thousands of loans monthly does not rely on loan officer discretion; it builds integrated insurance marketplaces that automatically present three to five options to the borrower at the point of application. The loan officer becomes an interface, not a decision-maker. When United Wholesale Mortgage processes a loan through its BOLT platform, or when Rocket Mortgage guides a borrower through its native application, the insurance selection is prepopulated based on algorithmic matching of coverage needs, pricing, and speed of binder issuance. The individual loan officer who once sent clients to Goosehead because she trusted the one-hour service guarantee is now executing software instructions. The relationship advantage dissolves into API latency.
This transition from human referral to platform integration represents an existential reframing of Goosehead’s distribution economics. The unpaid referral model assumes that mortgage professionals act as independent economic agents who value service quality over direct compensation. But platforms do not possess loyalty; they possess cost-benefit analyses. When a mortgage aggregator controls ten thousand loan officers, the calculus changes from “which insurance agent helps me close this deal smoothly” to “which insurance integration reduces my fall-through rate by basis points and generates ancillary revenue.” Platforms can demand revenue-sharing agreements that independent loan officers cannot. They can build captive insurance agencies or white-label partnerships that capture the commission internally. They can preference carriers who pay for placement in the digital marketplace, converting Goosehead’s organic referral flow into a paid auction where the highest bidder, often a direct writer with lower overhead, wins the click.
The geographic concentration that makes Goosehead vulnerable to Texas weather also makes it vulnerable to platform concentration. Texas is not merely Goosehead’s largest market; it is the epicenter of independent mortgage banking, home to United Wholesale Mortgage and a dense network of independent loan originators who have historically valued the speed and choice Goosehead provides. As these originators consolidate under platform umbrellas, or as the platforms themselves build direct-to-consumer insurance capabilities, the independent agency model faces disintermediation not through technological obsolescence but through vertical integration. The platform owns the customer before the customer knows they need insurance. By the time the borrower reaches the closing table, the coverage is already bound through an integrated portal, and Goosehead’s agents are competing for the residual twenty percent of transactions that fall outside the platform’s capture radius.
This consolidation dynamic extends to real estate brokerages. Compass, with its technology-heavy agent platform, and eXp Realty, with its cloud-based infrastructure, are systematically reducing the agent’s role to that of a local guide within a national transaction machine. These brokerages increasingly offer affiliated insurance services at the point of listing or contract acceptance. When a Compass agent opens a transaction in the company’s proprietary platform, the system prompts for insurance referrals through preferred partners who have paid for that placement. The agent’s discretion, once the guardian of Goosehead’s referral pipeline, is overridden by corporate partnership agreements. The eighty percent referral volume that currently flows through individual relationships becomes subject to procurement decisions made at headquarters, where Goosehead competes not on service speed but on revenue share percentages and integration fees.
The bear case, then, is not that Goosehead’s service quality degrades or that carriers restrict capacity in Texas, but that the very structure of the home purchase transaction becomes platformized in a way that renders the independent agency model structurally irrelevant. If the mortgage application of 2027 includes an embedded insurance marketplace that quotes and binds coverage using the same data fields already collected for underwriting the loan, the consumer never experiences the “shopping” moment that Goosehead’s two-hundred-carrier panel is designed to capture. The comparative rater becomes a backend pricing engine invisible to the borrower; the agent becomes a customer service representative handling claims for a policy sold by software. In this scenario, Goosehead’s productivity advantages, its 2.8x corporate agent metrics, become meaningless because the transaction volume migrates to zero-touch digital binding. The company is left with the renewal book, a declining asset as platformized insurance offerings improve their own retention through seamless policy servicing and automatic re-shopping algorithms.
The fragility of the model becomes most apparent when examining the contingent commission structure that supplements Goosehead’s core economics. Carriers pay these profit-sharing bonuses, typically two to four percent of premium, based on the loss ratio of the business Goosehead places. In stable weather years, this is found money, padding EBITDA margins that already expanded from fourteen to thirty-two percent. But contingent commissions are the first expense carriers cut when catastrophic losses accumulate. The 2023 Texas storms did not merely restrict new business capacity; they vaporized the contingent commissions Goosehead had booked as operating income. When fifteen severe storms cause twenty to fifty billion dollars in damage, the profit-sharing pool dries up regardless of how efficiently Goosehead’s service team operates. The company bears the fixed cost of the centralized infrastructure, salaries for the service team, technology maintenance, franchise support systems, while the variable bonus income that justifies that infrastructure disappears.
This asymmetry reveals the true risk profile of the renewal book. While the ninety-eight percent premium retention figure suggests stability, the profitability of that book is uncorrelated with Goosehead’s operational excellence and perfectly correlated with meteorological patterns and carrier pricing cycles. A franchisee in Houston who maintains perfect service standards and ninety NPS scores generates the same revenue as one who cuts corners when hailstorms devastate the region’s roofs and carriers slash contingent commissions to zero. The operational discipline that drove margin expansion between 2021 and 2024, culling underperforming agents, reallocating capacity to top franchises, compressing service costs, cannot optimize away the weather. The twenty-nine percent revenue growth and thirty-two percent EBITDA margins are, in part, artifacts of a benign loss environment punctuated by localized disasters that have not yet triggered systemic carrier withdrawals.
The technology moat, meanwhile, faces erosion from an unexpected vector: carrier direct investment in comparative rating capabilities. As carriers modernize their legacy policy administration systems, they are increasingly capable of providing real-time pricing adjustments to large distribution partners. Goosehead’s proprietary advantage lies in its ability to normalize data across two hundred disparate carrier systems, but as carriers standardize around API-first architectures, that normalization becomes commoditized. A mortgage platform or real estate portal can increasingly access carrier pricing directly, bypassing the agency layer entirely. The digital agent that matches clients to coverage in two minutes using three data points becomes redundant when the mortgage lender already possesses those three data points and can query carriers directly. Goosehead’s technology is defensive moat only so long as carriers remain technologically fragmented and platforms remain uninterested in insurance distribution. Both conditions are deteriorating.
The franchise model, for all its capital efficiency, compounds these risks rather than mitigating them. Franchisees are independent business owners with finite time horizons. When they perceive that platform consolidation is redirecting lead flow, or that carrier capacity constraints are compressing their ability to quote competitively, they have incentives to harvest their renewal books rather than invest in service quality. A franchisee facing declining new business volume can reduce staff, delay binder submissions, or push clients toward carriers paying higher commissions rather than those offering best coverage. Each such decision degrades the referral partner experience, but the franchisee captures the short-term revenue while the corporate entity bears the long-term brand damage. The 2022-2024 culling addressed historical underperformance but did not resolve the structural misalignment between franchisee incentives and the long-term health of the referral network.
Ultimately, Goosehead has built a machine of remarkable precision for capturing value at a specific moment in the home purchase process: moment that is being systematically dismantled by platform consolidation, carrier vertical integration, and climate volatility. The Rule of 60 aspiration assumes that the company can continue expanding its share of a channel that is simultaneously contracting in volume and becoming more competitive as platforms extract tolls for access. The unpaid referral model works only in a fragmented market of independent actors; it collapses when those actors aggregate into platforms that monetize their distribution power directly. The technology advantage persists only while carriers remain technologically unsophisticated; it erodes as carriers build direct API connections to the source of the transaction. The renewal economics appear stable only while weather patterns permit; they deteriorate instantly when catastrophic losses trigger the contingent commission provisions that wipe out profitability. The business is a high-performance engine running on fuel that is becoming scarcer and more expensive, ot because Goosehead is executing poorly, but because the territory it conquered is being redivided around it.