Tesla: When Architecture Becomes Engineering
The Building Becomes the Insulation
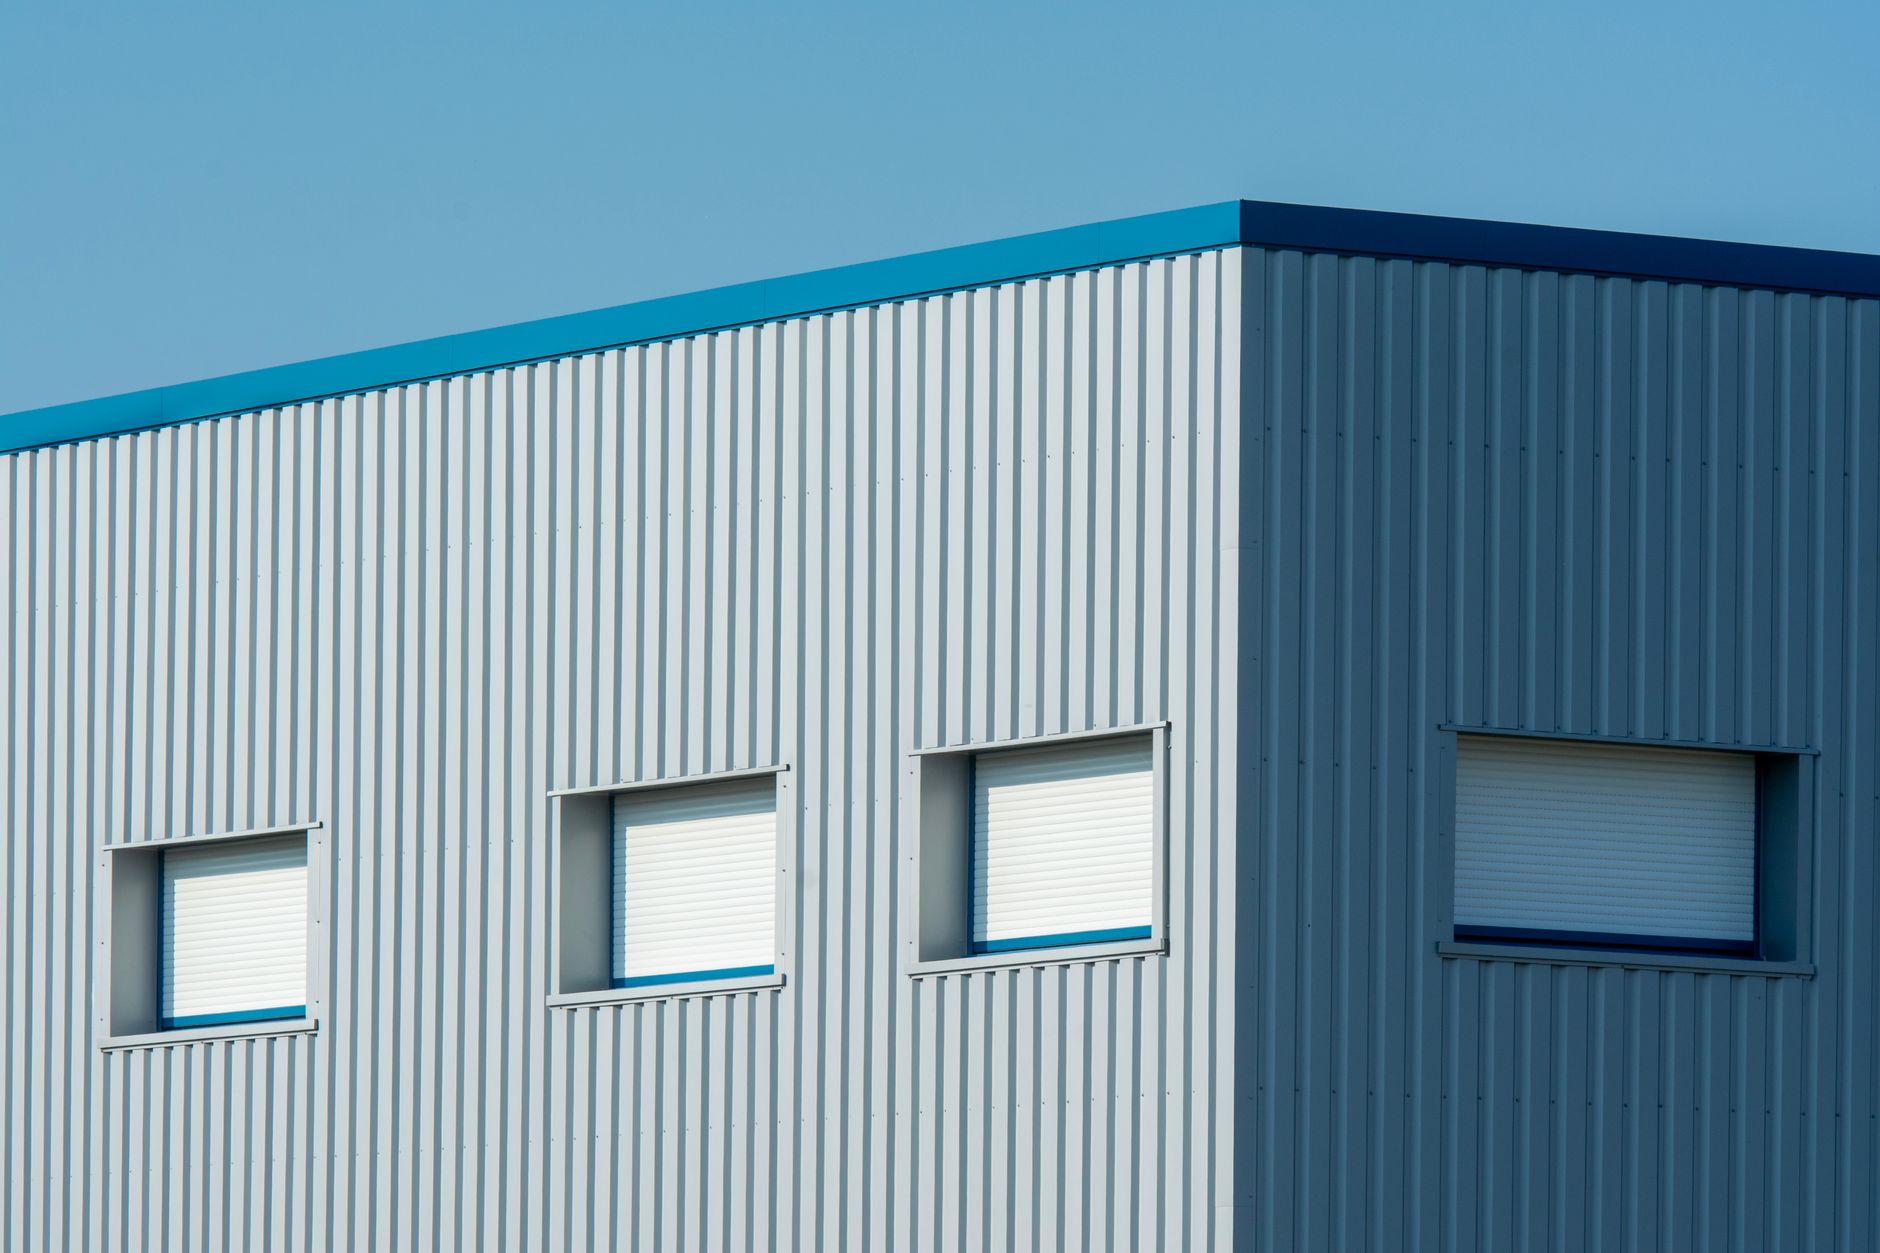
In the Nevada desert outside Reno, the Tesla Gigafactory rises from the floor of the high plains as a monumental exercise in thermal arithmetic. The structure is not merely wrapped in insulation; it is insulation, andwich panels of polyurethane foam core pressed between steel faces, spanning forty feet without internal support while maintaining a thermal resistance that keeps the desert heat from bleeding into precision battery assembly. When architects specify the envelope for facilities like this, or for Apple’s circular headquarters in Cupertino, or for the Emirates Stadium in London, they do not request “insulated panels.” They specify Kingspan. By name.
This is the economic engine of Kingspan Group, the Irish manufacturer that has transformed from a €120 million agricultural trailer business at its 1980s IPO into a €13 billion industrial concern. Kingspan does not sell commodities. It sells the resolution of a binding constraint: the architectural requirement that modern commercial buildings simultaneously bear structural load and achieve thermal efficiency standards that would have seemed impossible a generation ago. The product is a polyurethane or mineral compound core laminated between steel or plywood, functioning as both wall and insulation. The business model is to manufacture these panels at roughly thirty percent gross margins while capturing the specification decision at the earliest stage of design, elling direct to architects who then mandate Kingspan into the procurement chain, bypassing the price competition of distributors for sixty-six percent of revenue.
The compounding mechanism operates on three frequencies. First, organic growth from rising insulation penetration in underpenetrated markets: the United States has moved from roughly ten percent penetration to twenty percent in thirteen years, accelerating toward European levels of sixty to sixty-five percent. Second, the systematic acquisition of regional insulation producers with sales below €100 million, onto which Kingspan overlays its proprietary QuadCore product chemistry and direct-to-architect sales model while leaving local management in place and local brands intact. Third, margin stability, pproximately ten percent operating margins maintained through disciplined pricing power and geographic diversification that allows the pass-through of steel and chemical input costs over medium-term cycles. The structural tailwind is corporate net-zero commitments: forty percent of corporate emissions derive from building energy efficiency, forcing procurement decisions toward Kingspan’s products regardless of the economic cycle.
A Federation, Not an Empire
The defining structural constraint shaping every strategic decision at Kingspan is the tension between decentralized regional autonomy and centralized product standardization. The company operates in seventy countries with twenty thousand employees, but it is not a unified manufacturing colossus in the style of a Nucor or Saint-Gobain. It is a federation of regional specialists, knit together by a specific integration playbook that sacrifices economies of scale in favor of acquisition absorption capacity.
Each acquired region sources raw materials locally and manufactures differently. The Irish headquarters resists the urge to consolidate plants, standardize supply chains, or impose unified ERP systems. This is not negligence; it is the mechanism that preserves the ten percent operating margins. Centralized manufacturing would create stranded assets during regional downturns and alienate the local management teams whose relationships with regional architects constitute the acquired value. Yet this decentralization leaves margin upside on the table, nused scale economies in purchasing, inefficiencies in production scheduling, and slower competitive response in any single market where a centralized competitor might move faster.
The model demands a peculiar form of capital allocation discipline. Kingspan maintains leverage below 1.2x EBITDA (currently at 1.4x, slightly above target), deploys small deal teams rather than investment banking armies, and refuses acquisitions larger than €500 million. Return on capital employed hovers around fifteen percent despite the amortization burden of serial acquisitions. This is the cost of the federation: the company could likely extract higher margins by consolidating, but consolidation would break the cultural mechanism that allows Kingspan to absorb small regional players without indigestion. The constraint is binding. In 2008, the company nearly failed under excessive leverage; the memory of that trauma now prevents the optimization that might otherwise seem obvious.
Specification by Name
The underappreciated structural advantage lies not merely in the product chemistry, hough the QuadCore formulation, with its superior R-value and fire resistance, is patented and sufficiently guarded that Kingspan refuses to manufacture in China due to intellectual property concerns. The deeper moat is the specification network. Architects designing marquee projects specify Kingspan by name in the construction documents, creating a halo effect that cascades down to mid-tier commercial and industrial construction. This is not branding in the consumer sense; it is technical specification with legal and professional liability implications. Switching costs are high not because of contract terms, but because the architect’s professional reputation rests on the thermal performance of the envelope.
Competitors cannot easily replicate this. Nucor, the primary rival in insulated metal panels, approaches the market as a steel company diversifying downstream. Saint-Gobain and Owens Corning operate in different insulation categories, mineral wool and fiberglass, lacking the structural panel integration. Kingspan’s direct sales force, embedded in architectural firms for thirty years, creates a relationship density that distributor-dependent competitors cannot match. When Tesla builds its gigafactories, the procurement team receives thermal performance mandates from sustainability officers; the architects translate those mandates into Kingspan specifications. The product becomes the default choice not through marketing expenditure, but through the technical impossibility of achieving the required U-values (thermal transmittance coefficients) with alternative materials at comparable structural spans.
The Net-Zero Put Option
The most fragile long-term assumption underlying Kingspan’s valuation is that corporate net-zero commitments will remain binding and enforceable regardless of economic conditions. The company’s growth thesis assumes that Microsoft, TSMC, Tesla, and Starbucks will continue to reduce building emissions annually according to published sustainability targets, creating insulation demand that persists through recessions. If these commitments become discretionary, if a severe downturn causes corporations to defer capital expenditure on energy efficiency or if ESG mandates lose regulatory teeth, the structural tailwind becomes a headwind, and Kingspan reverts to the cyclical patterns of ordinary building materials.
This assumption is currently being tested in real-time. The U.S. penetration rate has risen one percent annually for thirteen years, but this depends on building codes tightening and energy prices remaining sufficiently high to justify insulation premiums. If natural gas prices collapse or regulatory enforcement stalls, the organic growth engine stalls with it. The company’s bet is that net-zero has shifted from marketing aspiration to procurement mandate, driven by the forty percent emissions figure and the public accountability of major corporate emitters. But public accountability is a political variable, not a physical constant. The 10% operating margins assume continuous demand; a reclassification of building efficiency from “strategic priority” to “deferrable cost” would compress margins as Kingspan competes for refurbishment work, urrently twenty-three percent of revenue and significantly more price-sensitive than new-build specification.
The Acquisition Playbook as Cultural DNA
What competitors cannot replicate is not the strategy of buying regional insulation producers, but the specific organizational capability of integrating them without destroying them. Kingspan’s acquisition playbook is a cultural artifact: small deal teams evaluate targets against a fifteen percent ROCE hurdle, post-acquisition management retains autonomy, local brands remain in place, and Kingspan products are overlaid onto existing distribution rather than replacing the acquired catalog entirely. This is not financial engineering; it is a repeatable operational discipline embedded in the company’s decision-making architecture.
Saint-Gobain, CRH, and other building materials conglomerates pursue acquisition-driven growth, but they typically impose centralized procurement, rebrand acquired assets, and optimize for short-term synergy extraction. Kingspan’s approach sacrifices short-term efficiency for long-term absorption capacity. The discipline is enforced by family ownership: Eugene Murtagh Sr., the founder now in his eighties, still controls over fifteen percent of shares. Eugene Murtagh Jr. has served as chief executive since 2006. The ownership structure enables patience that public market pressures might otherwise prohibit. When acquisition targets become scarce or valuations spike in high-growth markets like the United States, Kingspan’s response is to wait rather than overpay: restraint that protects returns on capital but risks allowing competitors to establish footholds in underpenetrated regions.
When the Cost Pass-Through Fails
The margin stability that defines Kingspan’s investment thesis, thirty percent gross, ten percent operating, is not automatic. It depends on three-month order visibility and the ability to pass through input cost inflation for steel, polyurethane, and chemicals. In a deflationary recession or a price war, this mechanism breaks. The company’s 2008 near-death experience, triggered by excessive leverage and a collapse in commercial construction, remains the governing trauma. Management is now gun-shy, potentially missing strategic acquisitions to preserve balance sheet integrity, yet simultaneously exposed to margin compression if commodity prices spike during a demand downturn.
The vulnerability is asymmetrical. In growth periods, the direct-to-architect model protects pricing power because the specification decision precedes the procurement budget. In recessions, however, the twenty-three percent refurbishment segment becomes a larger share of revenue, and refurbishment customers buy through distributors rather than direct specification. This channel shift exposes margins to commodity volatility without the protection of architectural stickiness. If steel prices rise while construction starts fall, Kingspan cannot pass costs through to price-sensitive refurbishment contractors the way it can to architects specifying Tesla’s next factory. The operating leverage in the manufacturing footprint, designed for scale, becomes a liability when capacity utilization drops.
The Third Eugene
The ultimate economic variable in Kingspan’s model is neither the chemistry of QuadCore nor the penetration rates of the American Midwest, but the continuity of family governance across generational transition. The third Eugene Murtagh, in his forties and positioned to succeed his father, has not yet been tested as chief executive during a crisis. The acquisition discipline, the leverage restraint, the tolerance for decentralized inefficiency, hese are cultural traits transmitted through family control, not professional management incentives. If the third Gene lacks the founder’s instinct for acquisition timing or the second Gene’s crisis memory, the business could drift toward the conglomerate model of competitors: over-leveraged, over-centralized, and stripped of the federation model that generates fifteen percent returns on capital.
This is not a character study; it is a capital allocation analysis. The fifteen billion euro market capitalization assumes the continuation of a specific decision-making pattern: small acquisitions, patient integration, no debt above 1.2x EBITDA, and direct architect relationships maintained despite the temptation to scale through distributors. Professional management, hired without the Murtagh family’s multi-generational equity stake, might optimize for quarterly earnings, consolidate manufacturing, and overpay for growth in Asia. The business has survived two generations but has not yet proven it can survive a third under stress. The federation of regional insulation specialists, united by proprietary chemistry and family discipline, remains an experiment in permanent organization: structure that works until it doesn’t, contingent on the durability of net-zero mandates and the judgment of the next Eugene.
The Channel Conflict That Does Not Yet Exist
The sixty-six percent direct-to-architect model is not merely a sales strategy; it is a margin architecture. When Kingspan’s specification managers sit with architectural firms in London, Melbourne, or Chicago, they are not selling price. They are selling thermal performance guarantees, structural span capabilities, and the liability protection that comes with specifying a product that has already been validated on Apple’s headquarters. This relationship insulates pricing from the commodity dynamics that plague the thirty-four percent of revenue that moves through distributors. Yet this protection creates a binding constraint on growth velocity.
Distributors, regional building supply houses, industrial roofing contractors, refurbishment specialists, offer scale without relationship density. They purchase inventory, carry credit risk, and extend Kingspan’s reach into the fragmented refurbishment market where no single architect controls the specification. The temptation to expand this channel is constant, particularly in the United States where geographic dispersion makes direct coverage expensive. But distributors commoditize. They stock competing panels from Nucor or regional steel fabricators, they negotiate on price rather than performance, and they introduce channel conflict that erodes the architect-direct premium. If a contractor can source “equivalent” insulation from a distributor at fifteen percent less, the architect’s specification becomes a preference rather than a mandate, and the thirty percent gross margin begins its slide toward the twenty percent characteristic of commodity steel.
Kingspan has managed this tension by treating distribution as a capacity release valve rather than a growth engine. When direct sales teams are saturated or when refurbishment demand spikes, distributor volume fills plant capacity. But the company refuses to invest in distributor-exclusive product lines or volume rebates that would shift the mix beyond the one-third threshold. This is a decision to sacrifice top-line growth for margin integrity. The risk is that competitors with purer distribution models, Nucor, with its steel service centers and mill-direct relationships, may capture share in the U.S. Midwest or Southeast where construction volumes are high but architect density is low. Kingspan’s response has been to acquire local manufacturers in these regions and install direct sales forces locally, maintaining the model at the cost of acquisition capital rather than margin points. It is a capital-intensive solution to a channel problem, sustainable only if the fifteen percent ROCE hurdle continues to clear.
The Chemistry of Conversion
The transition from QuadCore to OPTIM core, the next-generation thermal barrier currently rolling out across acquired plants, illustrates the operational fragility hidden within the growth narrative. QuadCore represented a step-change in thermal efficiency, a proprietary blend of polyurethane formulations and blowing agents that achieved higher R-values per inch than competitors’ mineral wool or standard PUR systems. OPTIM core promises further improvement, potentially extending Kingspan’s technical lead. But the manufacturing conversion is not a software update.
Each acquired plant, optimized for its legacy regional product, must be retrofitted with new foaming equipment, chemical handling systems, and quality control protocols. The capital requirement is significant, but the operational risk is greater. During conversion, plants lose capacity. Supply chains must be rerouted. Local management teams, retained precisely for their regional expertise, must be retrained on chemistry they did not develop. If the rollout delays, or if the new core suffers field-performance issues during the transition, Kingspan risks losing specification on marquee projects to competitors with stable, if inferior, supply.
This tension is acute because the competitive moat depends on continuous innovation. The patent on QuadCore will eventually expire; the chemistry will be reverse-engineered. Kingspan must maintain a product generation lead to preserve the architect specification premium. Yet the federation model that enables acquisition absorption complicates product standardization. A centralized manufacturer could mandate conversion across all plants simultaneously, accepting the downtime as a strategic cost. Kingspan must negotiate conversion plant by plant, respecting the autonomy that makes acquisitions viable while trying to achieve the economies of scale that justify the R&D expenditure. The result is a staggered rollout that cedes temporary advantage in specific markets. When Nucor or a regional competitor launches a comparable thermal product in a specific geography during a Kingspan conversion window, the specification battle becomes a price battle, and the federation structure reveals its liability.
The Anatomy of a Acquisition
To understand how the economic engine actually functions, consider the acquisition of a hypothetical regional insulation manufacturer in the American Southeast, et us call it ThermaPanel, a $60 million revenue business serving industrial warehousing and cold storage facilities in Georgia and Alabama. ThermaPanel operates two plants, sources steel from domestic mills, and sells primarily through a network of roofing contractors. Its margins are eighteen percent gross, six percent operating. It is family-owned, the founders aging out, with no succession plan.
Kingspan’s deal team, three people, not twenty, evaluates ThermaPanel against the fifteen percent ROCE hurdle. They do not value the company on strategic synergy or market expansion narrative. They model the cash flows from overlaying QuadCore chemistry onto ThermaPanel’s existing steel supply relationships, converting the sales force from contractor-relationship managers to specification managers targeting architects in Atlanta’s commercial construction boom, and maintaining the ThermaPanel brand for existing contractor business while introducing the Kingspan brand for architect-specified new build.
Post-acquisition, the ThermaPanel CEO remains. The ERP system, likely an aging AS/400 or regional accounting package, remains. The steel supplier relationships remain, though Kingspan’s purchasing consortium now negotiates chemical inputs at better rates. Over eighteen months, Kingspan specification managers are hired locally, trained in Dublin on thermal performance engineering, and embedded with Atlanta architectural firms. ThermaPanel’s plants begin producing QuadCore panels alongside legacy product, using the existing steel laminating lines but adding Kingspan’s proprietary foaming equipment in a corner of the facility. The conversion requires six months of downtime on one line, during which the other line runs double shifts to fulfill contractor backlog.
If successful, ThermaPanel’s gross margins migrate toward twenty-eight percent on the architect-specified volume, while contractor business stabilizes at twenty percent. Operating margins expand toward ten percent as the specification mix increases. The acquired management team, now equity-incentivized in the Kingspan structure, identifies three adjacent markets for de novo expansion. The ROCE on the $45 million purchase price clears the hurdle by year three. If unsuccessful, f the specification managers cannot crack the Atlanta architect community, if the chemical conversion causes quality failures, if the founder’s departure triggers a talent exodus, ingspan owns a commodity panel manufacturer with eighteen percent gross margins and a limited growth trajectory. The federation model prevents the forced integration that might have caught these problems early; the autonomy that enables absorption also enables silent failure.
The Margin Compression Scenario
The bear case for Kingspan is not a catastrophic bankruptcy but a slow regression to the mean of building materials. Imagine a scenario beginning in late 2025: a synchronized global downturn reduces commercial construction starts by thirty percent. Simultaneously, geopolitical disruption in chemical supply chains spikes isocyanate prices, the primary input for polyurethane, by forty percent. Steel prices, volatile but trending down in recession, fail to offset the chemical shock.

In this environment, Kingspan’s three-month order visibility provides insufficient runway for price increases. Architects, facing project cancellations, lose their budget authority; procurement officers at Tesla or Microsoft, facing cash conservation mandates, challenge specifications and demand value-engineering alternatives. The direct-to-architect channel loses its pricing protection first. Kingspan attempts to pass through chemical costs, but contractors, now empowered by excess capacity, push back. The company faces a choice: lose volume to maintain margins, or cut prices to keep plants running.
If Kingspan chooses volume, the ten percent operating margin compresses toward five percent as fixed manufacturing costs spread across fewer panels. The leverage ratio, currently at 1.4x EBITDA, creeps toward 2.5x as EBITDA contracts. Debt covenants, historically loose due to the company’s conservative reputation, tighten. The acquisition pipeline freezes, ot for strategic discipline, but because credit markets close for cyclical building materials companies and internal cash flow is consumed by interest coverage.
More dangerously, the channel mix shifts toward refurbishment. New commercial construction, down thirty percent, forces Kingspan to chase the twenty-three percent refurbishment segment that now becomes forty percent of revenue. Refurbishment customers buy through distributors, not direct specification. The thirty percent gross margin becomes a memory; the company achieves twenty-two percent on distributor volume, and the operating margin settles at six percent, espectable for a commodity manufacturer, catastrophic for a company priced for fifteen percent ROCE and continuous acquisition growth. The stock re-rates from a growth premium to a cyclical multiple. The federation model, designed for absorption, reveals itself as an inability to cut costs centrally. Regional managers, protecting their fiefdoms, resist plant closures or headcount reductions. The family ownership, committed to long-term stability, refuses to sell assets at cyclical lows, trapping capital in underperforming regions.
This scenario is not theoretical. It is the 2008 experience refined. Then, Kingspan faced a similar collapse in commercial construction, saw leverage spike, and survived only by emergency equity issuance and asset sales at distressed prices. The current management, led by the second Eugene, carries that memory as trauma. But trauma can become paralysis. If the third Eugene, untested by crisis, faces this scenario and lacks the founder’s willingness to make brutal cuts, closing plants, firing regional managers, abandoning the federation model temporarily for survival, the company does not fail, but it normalizes. It becomes Saint-Gobain with an Irish accent: a decent building materials company trading at eight times earnings, not twenty.
The Regulatory Assumption in Practice
The penetration rate mechanics in the United States expose the specificity of Kingspan’s net-zero bet. When Kingspan entered the U.S. market in earnest in the early 2000s, insulation penetration in commercial construction stood at roughly ten percent. Today it stands at twenty percent. This one-percent-per-year growth has been driven not by market forces alone, but by the tightening of ASHRAE standards, the adoption of stretch codes in Massachusetts and California, and the LEED certification requirements that became de facto mandates for corporate headquarters construction.
For penetration to reach forty percent, approaching European levels, requires continuation of this regulatory tightening. It assumes that energy codes in Texas, Florida, and the Midwest will tighten to match California’s Title 24 standards. It assumes that natural gas prices will remain sufficiently high to justify the capital expenditure premium of high-performance envelopes. It assumes that the Inflation Reduction Act’s green building tax credits survive political transitions and are not diluted by administrative rulemaking.
Most critically, it assumes that corporate net-zero commitments translate into binding procurement standards. When Microsoft commits to carbon-negative operations by 2030, it creates a cascade of building efficiency requirements for its data centers and offices. But if Microsoft, facing a recession and shareholder pressure, extends that deadline to 2035, or shifts focus to carbon offsets rather than operational efficiency, the demand for Kingspan’s premium panels softens. The specification remains on the drawings, but the project is value-engineered to standard insulation with greater mechanical heating and cooling capacity, heaper upfront, more carbon-intensive operationally, but financially rational if carbon accounting becomes flexible.
Kingspan’s growth thesis requires that carbon accounting remains rigid. This is a political and cultural variable, not a technological one. The company sells to procurement officers who are evaluated on ESG metrics. If those metrics are relaxed, if the “E” in ESG becomes discretionary during a recession, the forty percent of corporate emissions that come from buildings ceases to drive specification decisions. The thermal efficiency advantage of QuadCore becomes a nice-to-have rather than a need-to-have, and Kingspan’s pricing power evaporates into the general building materials market.
The Geography of Diversification
The transformation of Kingspan’s geographic footprint, from eighty percent UK/Ireland in 2005 to eighty percent international today, represents a specific risk distribution strategy that is often mischaracterized as growth for growth’s sake. In 2005, Kingspan was a regional Irish manufacturer with a sterling cost base and a UK-dependent revenue stream. The 2008 crisis demonstrated the fragility of this concentration. The shift to the Americas, Australasia, and continental Europe was not merely expansion; it was insurance against single-market construction cycles.
But this diversification creates complexity that tests the federation model. The U.S. market requires UL certification, different fire-testing protocols than Europe, and relationships with steel mills in the domestic supply chain. The Australian market demands cyclone-rating structural performance. Central and Eastern European markets require price points that challenge the thirty percent gross margin target. Kingspan has addressed this by acquiring local specialists who already possess the certifications and relationships, the ThermaPanel model, but this means the company operates not as a unified global manufacturer, but as a portfolio of regional specialists sharing a brand and a chemistry.

The risk is that scale economies in R&D, particularly in the transition to OPTIM core, are diluted across incompatible regulatory environments. A thermal breakthrough validated for European fire codes may require eighteen months of retesting for U.S. code acceptance. The federation, autonomous in manufacturing, cannot leverage centralized R&D speed. Competitors with unified global product platforms, particularly Asian manufacturers with state-supported standardization, may move faster in specific markets, undercutting Kingspan’s technical lead with “good enough” performance at lower cost.
The Silence of the Third Generation
The succession question is not merely about personality or competence; it is about the preservation of a specific decision-making heuristic. The first Eugene built the company through opportunistic acquisition and product innovation, betting the trailer business on insulation panels. The second Eugene survived the 2008 deleveraging crisis, embedding the trauma of excessive leverage into the company’s financial architecture. The third Eugene must prove capable of maintaining the tension between growth and discipline without the legitimizing authority of having survived a near-death experience.
What would reveal his competence? Not the continued execution of small acquisitions, hat is a mechanical process now embedded in the organization. Competence would be demonstrated by restraint when the model is tested: by refusing to overpay for a $400 million U.S. target when competitors bid $600 million, even if this means ceding the Midwest market for a decade; by closing a federation plant that has become structurally unprofitable despite the regional manager’s protests; by accelerating the OPTIM core conversion despite the short-term margin hit, betting that technical leadership matters more than quarterly earnings.
Failure would look different: a pivot to distributor-heavy growth to satisfy analyst demands for top-line acceleration; a “strategic” acquisition of a $1 billion non-insulation business that diversifies revenue but breaks the ROCE model; a centralized ERP implementation that “rationalizes” the federation and destroys the acquisition integration capability. The third Eugene does not need to be a visionary. He needs to be a steward of constraint: manager who understands that Kingspan’s advantage is not scale but specificity, not growth velocity but growth selectivity.
Whether this transmission succeeds is unknowable in advance. Family ownership provides the time horizon for such stewardship, but it does not guarantee the wisdom. The Murtagh family’s continued control of fifteen percent of shares, sufficient to block hostile takeovers but not sufficient to fund growth without external capital, creates a governance equilibrium that is stable until it is not. If the third generation lacks the founder’s instincts, or if family dynamics introduce conflict between branches of the ownership structure, the professional management team will default to the metrics of ordinary building materials companies: EBITDA growth, margin expansion through cost cutting, and eventually, consolidation by a larger industrial conglomerate that dissolves the federation into a division.
The Permanent Experiment
Kingspan stands as a test of whether industrial companies can maintain federation structures indefinitely, or whether the logic of scale eventually forces centralization. Its sixty-year history suggests that the model is durable but not inevitable. The company has survived because it identified a specific technical niche, structural insulation panels, where specification complexity justified a direct sales model, and where regulatory trends favored continuous thermal efficiency improvement. It has grown by resisting the temptation to become a conglomerate, accepting the operational inefficiencies of decentralization in exchange for the strategic flexibility of acquisition absorption.
But the experiment continues under increasingly challenging conditions. Input cost volatility, channel pressure, generational transition, and the political durability of net-zero mandates all test the model’s boundaries. The company is not a monopoly; it is a specialized competitor in a large market, differentiated by relationships and chemistry rather than by network effects or regulatory capture. Its margins are premium but not excessive, its growth steady but not explosive, its culture distinct but not immutable.
The valuation assumes continuity: that the federation will absorb the next fifty regional manufacturers, that the third Eugene will govern like the second, that architects will specify Kingspan by name for the next generation of gigafactories and corporate campuses. If any of these assumptions fail, the business does not collapse; it normalizes. It becomes a competent manufacturer of insulated panels, worth perhaps half its current market value, generating cash but not compounding it. The current premium is a bet on the permanence of a specific organizational form: bet that, in the industrial economy, federation can survive empire.